This is generally a good report for the Fed and potentially good news for mortgage rates, but there is an important wrinkle.
July retail sales fell 0.6%, versus expectations for a 0.1% gain. It was the first monthly decline in nine months. More importantly, the control group, which is used as an input into GDP calculations, fell 0.4%.
What does it mean?
1. The consumer is starting to slow down. Consumer spending has been one of the stronger parts of the economy. A significant miss like this suggests households may be becoming more cautious with their money.
2. This adds to the argument that the economy is cooling. Put this together with the weak July jobs report—23,000 jobs lost and the downward revisions to May and June, and we have several indicators pointing toward a softer economy.
3. That’s potentially good news for the Fed. The Fed has been concerned about inflation, but it also has a mandate to support employment. If inflation is coming down while employment and consumer spending are weakening, the argument for keeping rates elevated becomes less compelling.
4. And that’s where mortgage rates come in. The Fed doesn’t directly set mortgage rates, but expectations for future Fed policy influence Treasury yields and mortgage-backed securities. A cooling economy can ultimately create a more favorable environment for mortgage rates.
But here’s the catch…
The market didn’t simply look at the headline and say, “Great, rates are going down.” Some of the weakness was influenced by lower gasoline prices, the timing of Amazon Prime Day moving into June, and other temporary factors. Retail sales are also measured in dollar terms and aren’t adjusted for inflation.
So I would characterize today’s report as:
Weak consumer + weak jobs + cooling inflation = increasingly difficult argument for Fed rate hikes.
But it doesn’t guarantee lower mortgage rates immediately. The market still has to weigh inflation expectations, Treasury supply, geopolitical risk, and what the Fed believes the data means.
For your mortgage commentary, the clean takeaway is:
The Consumer Is Finally Showing Some Cracks. Retail sales were expected to rise 0.1%. Instead, they fell 0.6%. Combine that with weak employment numbers and cooling inflation, and the economy is sending the Fed a pretty clear message: the consumer is slowing down.
That’s exactly what we need to see if we’re looking for a path toward lower Fed rates and eventually, lower mortgage rates.
Have a fantastic weekend and always feel free to reach out to our team.
The Bureau of Labor Statistics (BLS) released its July Jobs Report this morning, and it came in much weaker than expected. The economy lost 23,000 jobs, compared to expectations for an 80,000-job gain. In addition, payrolls for May and June were revised lower by a combined 103,000 jobs, reinforcing the view that the labor market has been slowing for several months.
In my opinion, this is exactly the type of data the Federal Reserve needs to acknowledge. The labor market is no longer showing the same level of strength it did a year ago.
The Fed’s dual mandate is to promote maximum employment and price stability. As inflation has moderated and the labor market has softened, the argument for maintaining, or even raising the federal funds rate becomes less compelling.
We also saw just how sensitive the bond market is to geopolitical headlines.
Mortgage rates had been improving over the past week, helped by renewed optimism surrounding a potential ceasefire agreement with Iran. Then, yesterday, reports surfaced that Iran and Oman were discussing changes to transit through the Strait of Hormuz, including the possibility of restricting U.S. and Israeli passage. Whether such restrictions could actually be implemented is highly uncertain, but the headline alone was enough to unsettle investors and temporarily push bond yields higher.
For borrowers waiting on the sidelines, today’s jobs report is encouraging. It doesn’t guarantee lower mortgage rates tomorrow, but it does strengthen the longer-term case that rates have room to move lower as the economy continues to cool.
As I mentioned earlier this week, a few Federal Reserve members stated that the labor market remains robust and even voted in favor of raising the Fed funds rate. Looking at the recent data, I struggle to see the same level of strength.
Tomorrow’s Bureau of Labor Statistics (BLS) jobs report will be a key market-moving event and could play an important role in shaping the Fed’s thinking on whether to hike, hold, or eventually lower the Fed funds rate.
Recent employment data has pointed toward a labor market that is slowing rather than accelerating:
ADP reported only 44,000 jobs added in July.
Revelio Labs estimated approximately 79,000 new jobs, with 28,000 of those in healthcare, suggesting job growth may be concentrated in a limited number of sectors.
ZipRecruiter, one of the nation’s largest job platforms, noted in its recent earnings report that while the first quarter was relatively stable, hiring activity softened noticeably in the second quarter.
Interesting trends beneath the surface. Hiring rates and quit rates have fallen to levels not seen in many years. That aligns with what job platforms are reporting: fewer openings and a more cautious hiring environment.
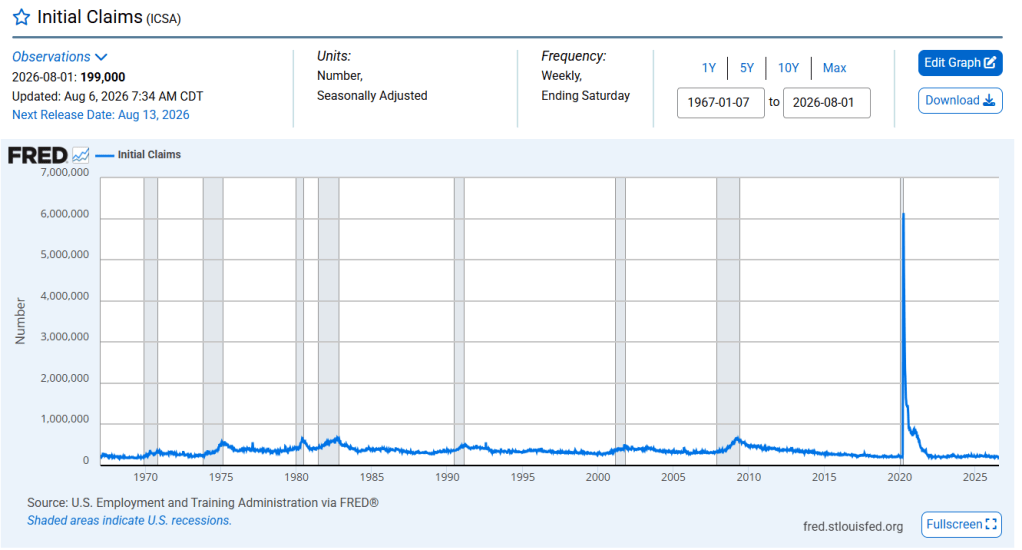
At first glance, lower jobless claims and fewer layoffs may suggest a healthy labor market, but it is important to dig deeper. Employers appear to be holding onto existing workers after years of labor shortages, resulting in fewer new job openings. At the same time, workers may be less willing to leave their current jobs because finding a new opportunity has become more difficult.
In other words, the labor market may not be strong…it may simply be frozen.
That is why tomorrow’s BLS report is so important. It will help answer a key question: Is the labor market truly resilient, or is it gradually losing momentum beneath the surface? The answer could have a significant impact on bond markets, mortgage rates, and the Federal Reserve’s next move.
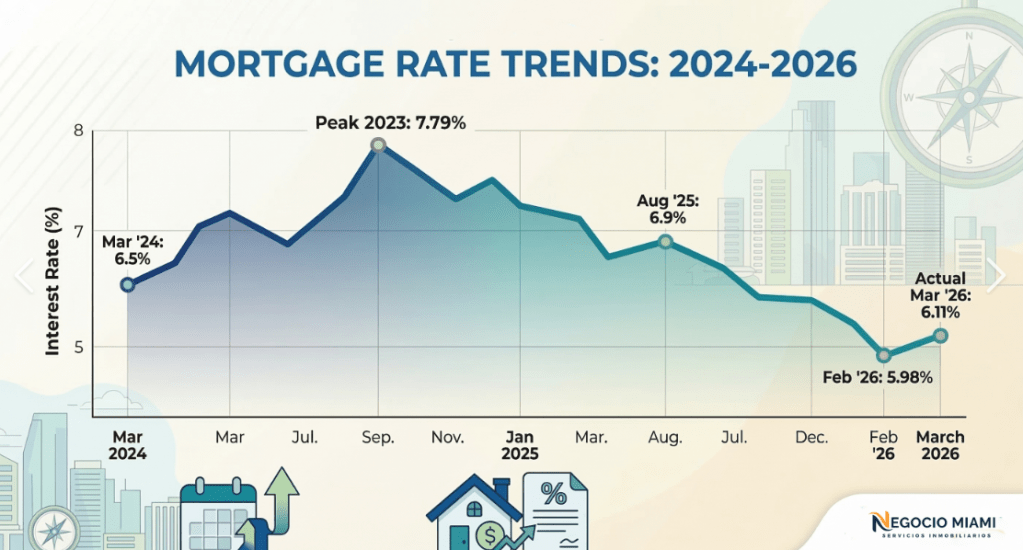
Let’s remember what the market looked like before the Iran conflict began. Mortgage rates had finally moved below the 6% for the first time in many years.
After years of borrowers sitting on the sidelines with rates in the high 6s, 7s, and even 8% range, we were starting to see a meaningful wave of refinance opportunities. Many homeowners were positioned to lower their monthly payments by hundreds and in some cases thousands of dollars.
Then, from Friday into Monday at the end of February, when the first bombings took place, the market reacted quickly and decisively. Investors did not like the uncertainty, and the bond market responded almost immediately. Mortgage rates moved higher as markets priced in additional risk.
Since then, it has felt like a roller coaster one day bringing renewed optimism and the next day putting deals back on hold. The constant swings have created frustration for borrowers, real estate professionals, and lenders alike. The whiplash has made many of us wonder when we can finally get off this ride.
The good news is, we may be approaching that opportunity. Here is my opinion on why (it’s a long read my apologies):
First, markets do not like uncertainty. The Iran conflict created a significant risk premium as investors reacted to concerns around oil prices, inflation, global stability, and economic disruption. Historically, once geopolitical events move from an unknown outcome toward a resolution or a clearer path forward, markets often begin to reverse those initial reactions. A reduction in uncertainty could provide relief to the bond market, which is one of the biggest drivers of mortgage rates.
Second, inflation remains the key piece of the puzzle. The Federal Reserve has been clear that sustainable progress on inflation is what will determine the pace of future rate cuts. If energy prices stabilize, supply chain concerns ease, and inflation continues moving lower, the market will likely begin pricing in additional Fed easing. Lower inflation expectations generally create a more favorable environment for mortgage-backed securities and mortgage rates.
Third, the political environment may become an important factor as we move toward the midterm elections. Regardless of political affiliation, voters continue to express frustration around the cost of living, housing affordability, and higher interest rates. Rising mortgage rates, elevated insurance costs, and overall affordability challenges are issues that directly impact households. Historically, when affordability becomes a major concern for voters, policymakers tend to place more focus on economic stability and measures that support growth.
The reality is that the economy is sending mixed signals. Employment has shown signs of slowing, consumers are feeling pressure from higher costs, and housing affordability remains one of the biggest challenges facing Americans. Those conditions may create more pressure for policymakers to support a lower-rate environment if inflation continues to cooperate.
I know I’ve said this before, but it’s worth repeating because it’s fundamental to understanding where mortgage rates are headed.
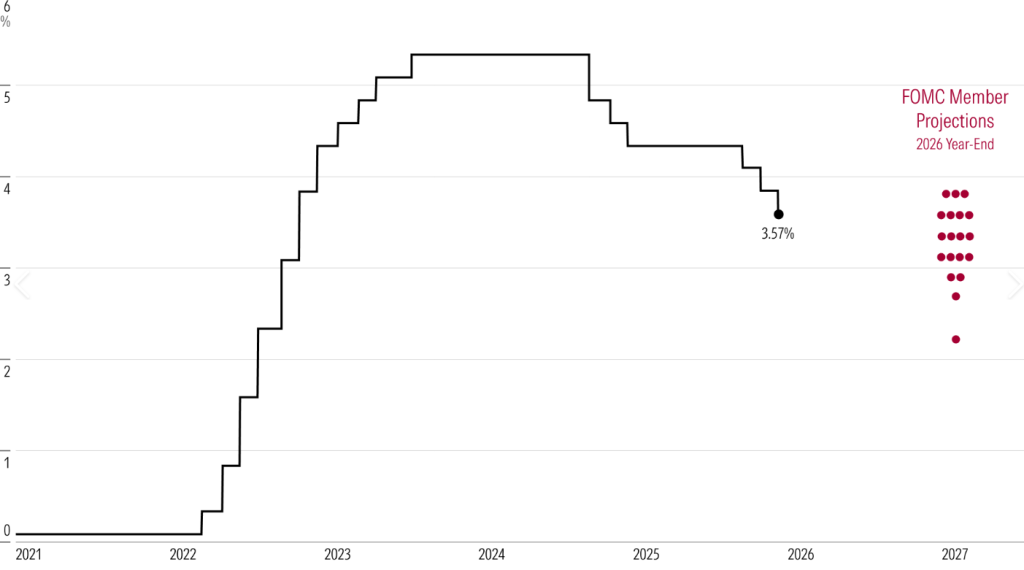
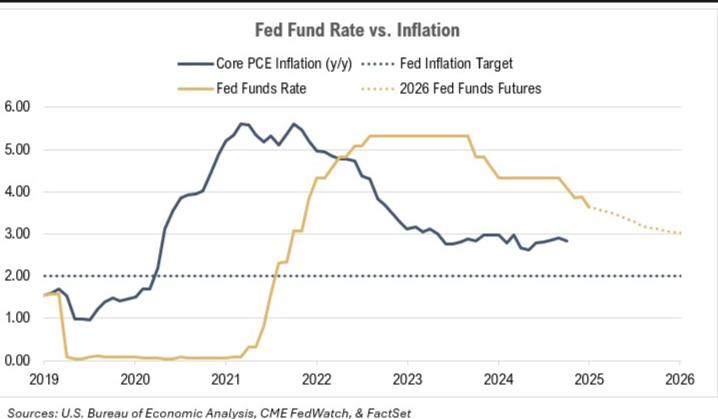
The Federal Reserve’s primary tool for fighting inflation is the Federal Funds Rate. By raising this rate, the Fed makes borrowing more expensive throughout the economy. It affects businesses looking to borrow money to expand, invest in new equipment, or hire employees. It also impacts consumers through higher borrowing costs on products like credit cards, auto loans, and home equity lines of credit.
The goal is simple: when borrowing becomes more expensive, consumers and businesses tend to spend less. That slower demand helps reduce inflationary pressure and eventually brings price growth back under control.
Here’s the challenge with today’s economy.
The Federal Reserve’s primary tool is raising or lowering short-term interest rates. That works well when inflation is being driven by an overheating economy, too much consumer demand chasing too few goods and services.
But that’s not what we’re seeing today.
Higher interest rates won’t produce more oil. They won’t lower gasoline prices caused by geopolitical tensions. They won’t grow more food, reopen supply chains, or reduce the cost of insurance. Those are supply-side issues that monetary policy has very little control over.
In fact, many parts of the economy are already slowing. Housing activity has softened, business investment has become more cautious, and consumers are feeling the effects of higher borrowing costs. These are signs of an economy that is responding to restrictive monetary policy, not one that’s overheating.
The concern is that if the Fed keeps rates too high for too long while inflation is increasingly driven by supply-side factors, it risks slowing the economy more than necessary. That’s why investors are watching inflation data so closely. If inflation continues to ease without a strong economy, it may support the case for lower interest rates and a healthier housing market.
The challenge for the Fed is recognizing the difference between demand-driven inflation and supply-driven inflation. Using the same tool for both doesn’t always produce the same results.
Pip: Mortgage rates, Fed minutes, oil prices, and a Fed chair who apparently has to talk the board out of hiking rates — welcome to the bond market's version of a group project where nobody agrees on the deadline.
Mara: Today we're working through posts from Jackkammer covering two connected territories: where the Fed actually stands on rates, and what falling oil prices are and aren't doing to inflation and the bond market.
Pip: Let's start with the Fed's internal divide.
The Fed's Split on Rates
Mara: The question here is simple but consequential — when Fed policymakers look at the same economic data, are they actually reaching the same conclusions about what to do next?
Pip: The June 17 meeting minutes answer that pretty directly. Setting up the numbers: "Eight members favored no rate cuts this year, one favored a single cut, and nine projected one rate hike."
Mara: So the upshot is that the Fed is almost perfectly split between holding steady and tightening further — which is not a committee that's going to move quickly in either direction.
Pip: A nearly even split on a body that's supposed to set unified policy — that's a faculty meeting with trillion-dollar consequences.
Mara: What the post calls constructive is that most members still expect inflation to keep easing as oil prices decline and tariff pressures fade. Existing home sales missed expectations, falling 2.4% in June to 4.09 million, and the labor market is softening gradually but holding. The post flags that U.S.-Iran tensions are driving real volatility in Treasury markets, which flows directly into mortgage rate swings.
Pip: Which brings us to the oil side of this — because the Fed's inflation outlook depends heavily on what energy prices actually do.
Oil Prices, Gas Prices, and the Gap Between Them
Mara: The tension in this territory is that falling oil prices are supposed to relieve inflation pressure — but the relief isn't arriving evenly or quickly across the economy.
Pip: The post on Fed chair Kevin Warsh puts the gap in concrete terms: "Oil prices have retraced 98% of their recent increase, but gasoline prices have only fallen back about 46%, and the bond market has recovered just 30%."
Mara: What this means in practice is that consumers and the bond market are both lagging behind what crude oil is already telling us. The structural reason is straightforward — gas prices spike fast when oil rises, but they come down slowly. OPEC+ announcing production increases should accelerate that normalization.
Pip: And that's where Warsh becomes the actual story.
Mara: Right. The post draws a clear contrast: some Fed voting members are pushing for rate hikes, while Warsh has signaled that's not the direction he's taking things. The framing is that Warsh is willing to look at forward-looking data rather than reacting to lagging indicators — which, given how slowly gasoline and bond markets are catching up to oil, matters quite a bit for where rates land.
Pip: Patience as monetary policy. Novel concept.
Mara: The post's conclusion is cautiously optimistic — encouraging signals from both an inflation and bond market perspective, with the reminder that markets move in cycles and the data, watched carefully, points toward improvement.
Pip: So the Fed is divided, oil is ahead of gas prices, and the bond market is somewhere in the middle, catching up.
Mara: The thread connecting both segments is timing — when signals arrive, when markets respond, and whether policymakers read the data forward or backward. Worth watching as those gaps close.
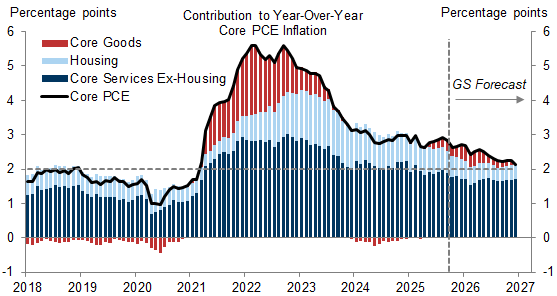
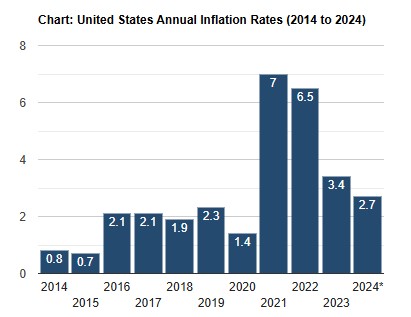
The Consumer Price Index (CPI) measures changes in the prices paid by typical consumers for a “basket” of goods and services. This basket represents everyday expenses, such as food, housing, and transportation.
The key figure often discussed—currently 2.7%—represents the year-over-year change in the cost of that same basket of goods and services.
The sharp spike in inflation during 2021 was largely a reaction to the economic disruptions caused by the COVID-19 pandemic. In 2020, spending slowed significantly due to widespread restrictions, closures of restaurants, hotels, airlines, and reduced travel overall. This near-deflationary period was followed by a dramatic rebound when restrictions eased.
Government intervention also played a role. Massive financial stimulus, including programs like PPP (Paycheck Protection Program) and other incentives, pumped billions of dollars into the economy to sustain businesses and households.
This created a “perfect storm.” As people emerged from lockdowns en masse—comparable to being released from a “chicken coop”—the sudden surge in demand for goods and services outpaced supply, driving prices higher.
The Bond Market reacted as expected with the 10-year treasury auction (monthly) at 1pm ET. High demand means lower Mortgage rates.