Softer economic data out of Europe is helping European 10-year yields move sharply lower, which in turn is helping global yields moderate.
France is talking Quantitative Easing (QE), or in real English, buying bonds. Not just a few billion here and there, but a systematic plan to buy tens of billions of bonds to help lower interest rates.
Reminder: Quantitative Tightening (QT) is what central banks have been doing for the last four years, reducing their bond holdings to shrink their balance sheets.
Quick reminder from yesterday’s post: To keep the same monthly payment you would have had when rates were 6.25%, today’s home price would need to be about 12% lower than it was last March.
Example: a $500K home last March would need to sell for about $440K today to keep the payment the same.
A big part of the bond market volatility, even with underlying weakness in the economic data: bonds initially rallied following the cooler PCE report and much weaker jobs report, but those gains have evaporated.
It’s unclear why, but one possibility is Japan. They are the largest foreign holder of our debt, and they’re dealing with a weakening currency. The weaker it gets, the more expensive imports become, and they import a lot.
The other challenge, which we saw a few years ago when rates touched 8%, is the mortgage spread: the difference between the 30-year fixed rate and the 10-year Treasury yield. The wider the spread, the more volatility and risk the market is pricing in.
Part of the reasoning is that borrowers with high rates will refinance as soon as they can. Investors holding those mortgage bonds get paid back early, losing the high interest they were counting on, so they demand a higher return up front to make up for it.
How to Tackle High Interest Rates
A $100K loan at 6.25% has a principal and interest payment of about $615. At 7.5%, that payment is $699.
The question: How much smaller does the loan need to be at 7.5% to keep the payment at $615? About $88K. That’s a $12K reduction per $100K borrowed.
Scale that up: the payment on a $500K loan at 6.25% is the same as on a $440K loan at 7.5%, a $60K difference. It’s very likely that the home you looked at last spring is $60K less today.
If you want to have your cake and eat it too, with a lower home price and lower rates, you might be waiting a long time. Shift your mindset just a bit: focus on the total payment, not just the rate.
Fed President John Williams: “There is no need for urgency, and the Fed has time to gather more information.”
Translation: A rate hike is unlikely.
Personal Consumption Expenditures (PCE) came in at 0.3% last month, one-tenth lighter than expected. Year-over-year, it dropped from 3.7% to 3.4% headed in the right direction at this point.
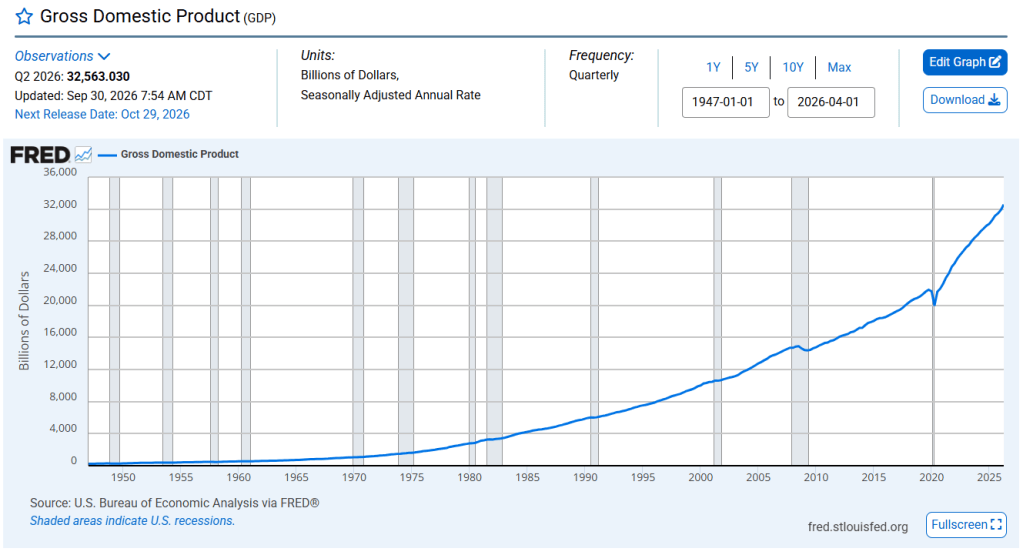
Q2 GDP came in at 2.2%, versus the 1.5% expected.
The ADP Employment Report showed 90,000 jobs created, versus 70,000 expected.
Mortgage applications were down, as expected, with rates still on the rise. Refinances made up 38% of transactions, with most being cash-out.
That’s a bit of a worrying sign. With rates as high as they are, and over one-third of applications being cash-out refinances, something is up. Time will tell.
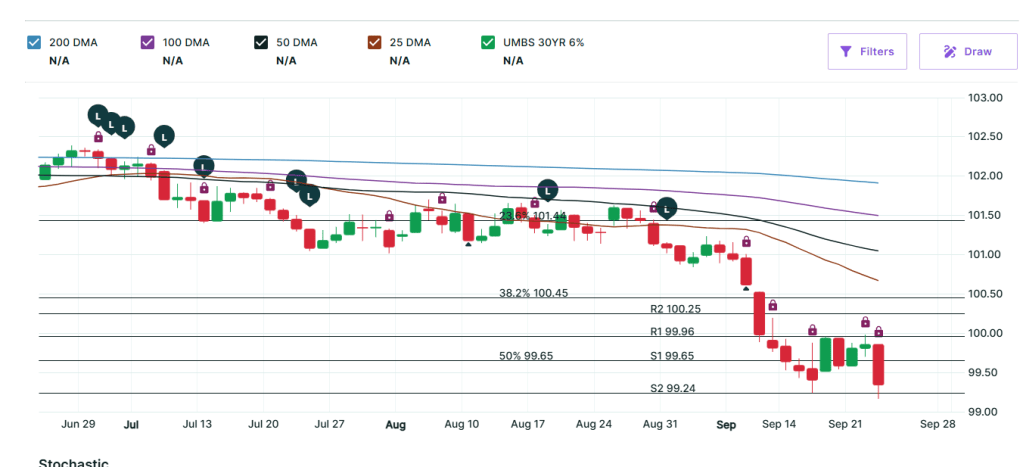
Mortgage Bonds are continuing lower, with yields higher, meaning mortgage rates keep climbing.
The housing market is stable for now, the way a Jenga tower is stable right before someone pulls the wrong piece. Rising rates mean shrinking approval amounts, and that pressure has to land somewhere, namely home values, as buying power quietly evaporates.
Until tariffs are removed, the Iran conflict ends, and fuel prices drop, we’re stuck standing on a chair missing a leg. Something has to give. Or everything does, all at once, which is the outcome nobody wants.
Job openings in August fell 256,000 to 7.08 million, missing estimates of 7.23 million. The labor market, politely declining to cooperate.
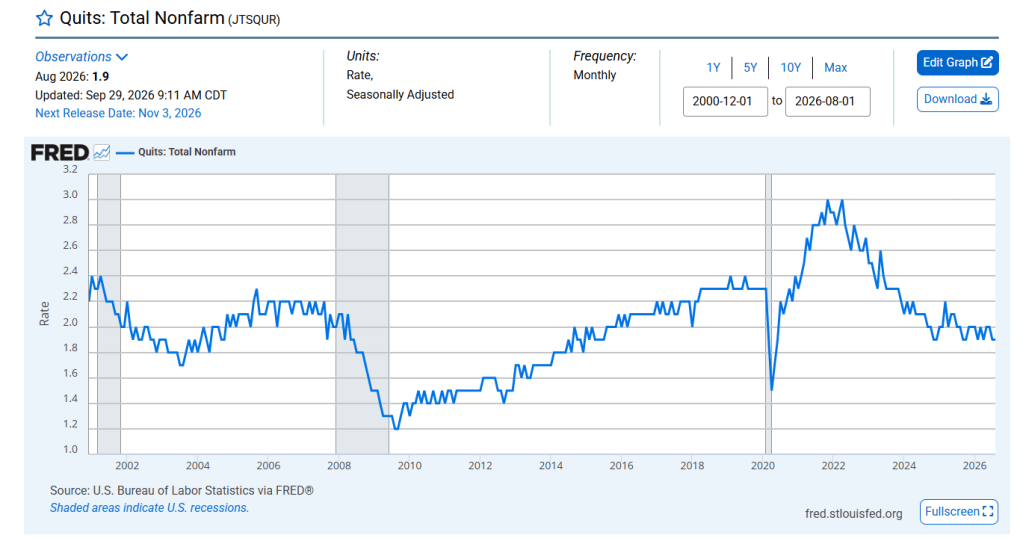
The telling number is the quits rate, still stuck at 1.9%, a measure of people confident enough to voluntarily change jobs. This low, it’s basically everyone deciding to sit very still, a strong signal of a weak job market.
The S&P Global Manufacturing report showed the economy running hotter than expected, triggering expectations for more policy tightening.
Comments on inflation regarding average input costs for goods and services, which surged higher (oil) hit their highest level since 2022.
Comments from Iran’s President at the UN, which were inflammatory.
Fed Governor Michael Barr also contributed to the bond selloff, stating that further rate hikes are likely to be needed.
Suffice to say, it was a bad day yesterday, and today is shaping up to be the same.
Some good news: New Home Sales, signed contracts on new homes rose 6.4% in August, with an annualized rate of 684,000, much stronger than the 620,000 estimate.
Part of this may be due to builders incentivizing buyers with massive rate buydowns and lower prices to move inventory.
If rates remain high, a lot of buyers will stay on the sidelines. Inventory is up, and most markets are softening, meaning there are opportunities to snag a great home at a fantastic price, which can help offset higher interest rates.
Threats of annihilation toward Iran, viewed by the markets as an escalation, sent oil prices and yields higher (meaning higher mortgage rates).
A representative who met with Iran described the discussion as very productive, lasting three hours. Later today, the Iranian President will be speaking at the UN, we’re watching this closely.
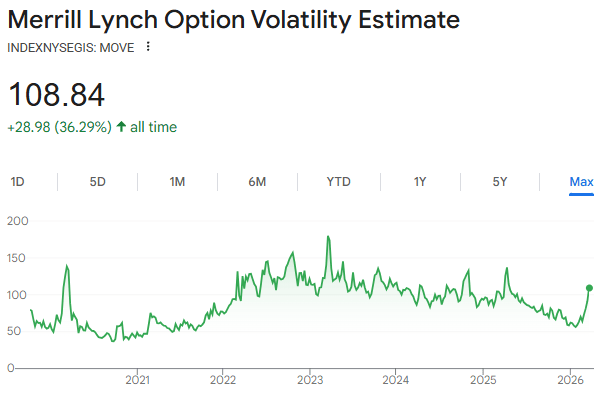
Volatility is exactly what the market dreads. As you can see from the graph below (down means higher rates), any sense of instability drives yields higher, resulting in higher mortgage rates.
ICE Home Price Index for September show home values remaining stable during the month. Year over Year, home prices nationwide are up 1.41%.
Demand Destruction: The Fed’s Favorite Party Trick
Let’s talk about “demand destruction”, which sounds like a Marvel villain’s origin story, but is actually just the Federal Reserve’s fancy way of saying “we’re going to make your life expensive enough that you stop buying stuff.”
That’s it. That’s the whole plan. No lasers, no secret lair, just interest rates, quietly turning your daily cup of coffee into a five-year financial decision.
Wait, What Even Is Demand Destruction?
In economist-speak: demand destruction happens when higher prices or higher borrowing costs cause people to buy less of something, which (in theory) cools off inflation.
On to other news…
Oil is down below $94 a barrel, Saudi Arabia may reopen their critical East to West pipeline.
There is increased economic pressure on Iran from the US, effectively shutting down their Airlines. The President is flying to NY to the US and we could have direct talks.
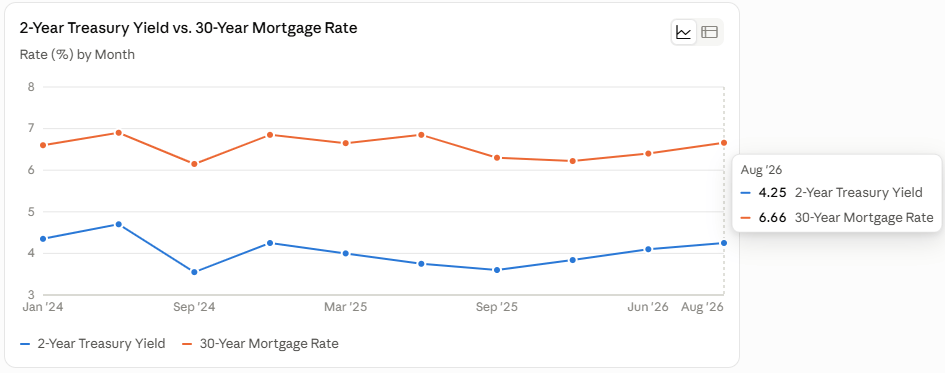
Graph below shows the relationship of the 2y bond to mortgage rates. Wonder what the rates are going to do? look at the 2y bond.
The Federal Reserve made a mistake, again. Raising rates in this environment doesn’t fight inflation. It fights the economy, while the actual source of inflation keeps burning in plain sight: oil.
This Isn’t Demand-Driven Inflation. It’s an Energy Shock.
Rate hikes are a blunt tool designed for one job: cooling off an overheating economy where too much money is chasing too few goods and services. That is not what’s happening right now.
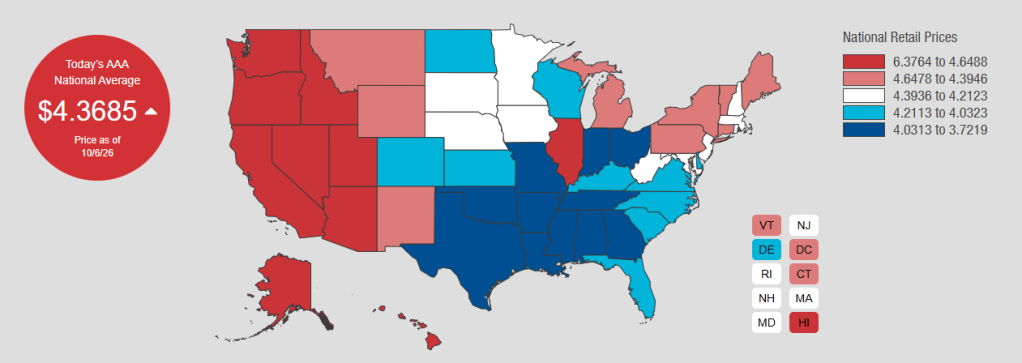
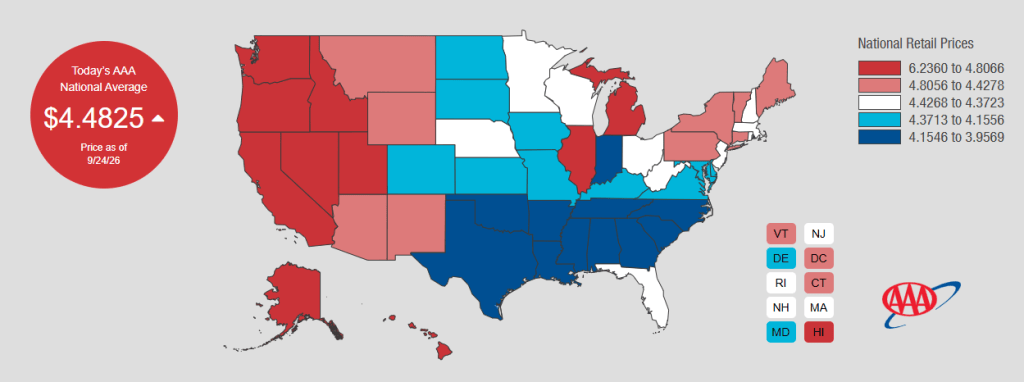
What’s happening right now is a supply shock. Oil is trading well above $90 a barrel, diesel has hit record highs, and the ripple effects are showing up everywhere, trucking costs, shipping costs, food costs, manufacturing costs. Diesel isn’t a niche input. It’s the fuel that moves nearly everything in the economy from a warehouse to a store shelf. When diesel spikes, the cost gets baked into the price of almost everything downstream, whether or not consumer demand has changed at all.
Raising interest rates does nothing to lower the price of oil. It doesn’t reopen a shipping lane, repair a damaged pipeline, or negotiate a ceasefire. What it does do is make it more expensive for businesses to borrow, expand, hire, and invest, piling a self-inflicted wound on top of an external one. The Fed is treating a supply-side energy problem with a demand-side hammer, and the only thing that gets nailed is the consumer and the labor market.
The Jobs Data the Fed Is Leaning On Is Softer Than It Looks
Here’s the part that should really give the Fed pause: the labor market data it’s using to justify staying hawkish is not as solid as it’s being treated.
The BLS jobs report is built on a survey, businesses filling out forms, self-reporting headcounts, with the data collected through phone, fax, and electronic questionnaires. It’s a well-constructed survey, but it’s still a survey, and it comes with real limitations: sampling error, non-response, and a track record of large revisions after the fact. We’ve watched this play out repeatedly, a headline number gets reported, markets and policymakers react to it, and months later it gets quietly revised by tens or even hundreds of thousands of jobs.
ADP’s employment report works differently. Rather than asking businesses to self-report on a form, it’s built from actual payroll processing data, real transactions covering tens of millions of workers who are actually being paid, in real time, through ADP’s systems. It’s not a business estimating its own headcount on a questionnaire; it’s the payroll data itself.
That distinction matters. A survey response and a processed paycheck are not the same category of evidence, and treating them as interchangeable, while giving the survey-based number outsized weight in a rate decision, is exactly the kind of thing that leads to policy mistakes getting locked in before the real picture becomes clear.
The Bottom Line
Inflation right now has an address, and it’s the pump, not the paycheck. Raising rates to fight oil-driven inflation doesn’t lower oil prices, it just slows down an economy that’s already showing cracks, using labor market data that deserves more skepticism than it’s getting. The Fed isn’t wrong to worry about inflation. It’s wrong about the cure.
SIDE NOTE: To be fair, there’s a case for the Fed’s approach too: even supply-driven inflation can become embedded if consumers and businesses start expecting higher prices to persist, and some economists argue that raising rates helps anchor those expectations regardless of the initial cause. There’s also a reasonable argument that the BLS survey, despite its revisions, still benefits from a larger and more consistently structured business sample than ADP’s payroll-based data, and that the two measures are best used together rather than one replacing the other. Reasonable people disagree on how much weight the Fed should put on an energy-driven inflation spike versus the risk of letting inflation expectations drift.
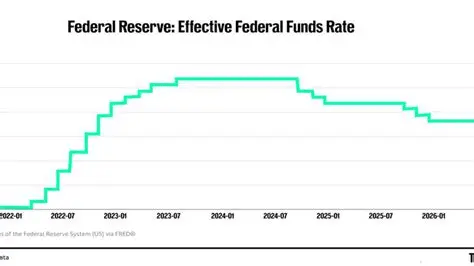
The Federal Reserve is expected to hike rates 25bp this Wednesday. The bond market has been on a tear, dragging mortgage rates along for the ride like an unwilling dance partner.
The 10-year Treasury yield is sitting at 4.99%, just a hair below the scary 5.00% mark. For context: back in late February, the 10-year was comfortably under 4.00%. That’s not just a 1-point difference in yield, it’s translated into more than a 1-point rise in actual mortgage rates.
Here’s the part nobody explains well: as rates climb, lenders get nervous about refinances, so any loan made now has a shorter expected life.
That uncertainty gets priced in as an extra spread on top of the Treasury yield, widening the gap between the 10-year and your actual mortgage rate.
In English: it’s not just what the 10-year is doing, it’s thegap between the 10-year and the mortgage rate that decides your payment, and right now, that gap isn’t doing anyone any favors.
Well, That Escalated Quickly
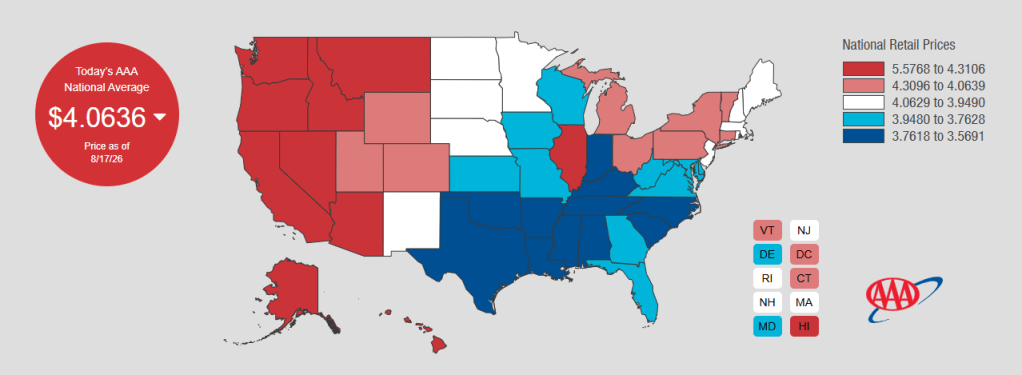
There’s a lot happening in the Middle East right now, and none of it is good news for your gas tank.
Saudi Arabia has shut down its East-West pipeline, the 7-million-barrel-a-day workaround built specifically to bypass the Strait of Hormuz, after a drone strike hit the line near Medina. So the backup plan for the backup plan just took itself offline. That’s not a great sign when you’re already down to Plan C.
The Houthis have seized Perim Island, a strategic chokepoint sitting right in the middle of the Bab el-Mandeb Strait, the “Gate of Tears” at the mouth of the Red Sea. Translation: they now have another lever to squeeze oil shipping, right as the Hormuz route was already struggling. The Red Sea and the Gulf are basically tag-teaming the global oil supply at this point.
My Take
The Fed is expected to raise rates because CPI inflation is running hot, but that inflation print is almost entirely a function of oil and diesel prices, with diesel now sitting at record highs. Diesel isn’t just a “gas at the pump” story either; it’s the backbone of trucking, shipping, farming, and manufacturing. When diesel spikes, everything that touches a truck gets more expensive.
Here’s the problem: raising rates doesn’t fix any of that. The economy is already slowing. This isn’t a “too much demand” inflation problem, it’s an oil supply problem, and the Fed doesn’t have a lever for pipelines getting droned or islands getting seized. Hiking rates into an oil-driven inflation spike is like turning up the AC because the house is on fire.
The bond market has a reason to be nervous today. The 60-day U.S.-Iran ceasefire framework has expired without a final agreement, and negotiations remain stalled. Both sides have accused the other of violating the agreement, while the biggest sticking point remains the Strait of Hormuz.
And this matters to mortgage rates.
The market had been hoping that a lasting agreement would remove some of the geopolitical and oil-price risk that has been pushing inflation expectations and long-term interest rates higher. A genuine de-escalation could take some pressure off bonds. In fact, analysts have noted that resolving the conflict could remove an energy-risk premium, although it wouldn’t automatically send mortgage rates lower.
But today, we’re back to the big question:
What’s next?
If negotiations restart and we see a credible agreement to reopen the Strait of Hormuz, we could see oil prices and inflation expectations move lower—and that could be very positive for bonds and mortgage rates.
If tensions escalate, however, the opposite could happen. Higher oil prices create renewed inflation concerns, and investors could demand higher yields to compensate for that risk. Shipping through Hormuz has already fallen dramatically from pre-war levels, keeping the market on edge.
The good news is that we also have some powerful economic forces working in the opposite direction: weak employment, softer CPI, weaker PPI and slowing consumer spending. Those are all arguments for lower rates.
So right now, we’re watching two competing stories:
📉 Economic data says rates should move lower. 📈 Geopolitical uncertainty says be careful.
That’s why the bond market is nervous.
The next major move in mortgage rates may come down to whether the Iran conflict moves toward resolution or escalation. For borrowers, this is another reminder that markets can change quickly.
The data is giving us reasons to be optimistic. Now we need the geopolitical picture to cooperate.