Mortgage bonds are holding the line at a key ceiling of 5.29%. For context, when mortgage rates averaged 5.99% last February, the 10-year was at 3.99%.
Yesterday’s Treasury auction was strong, a good sign that the peak may be in front of us.
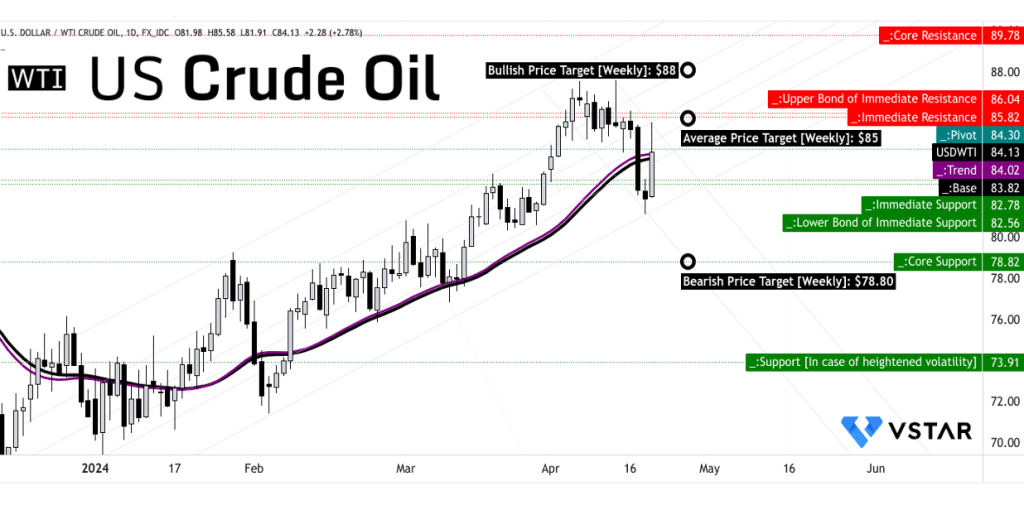
But oil is moving higher after reports that the President has asked the Pentagon for strike options on Iran ahead of the midterms. Markets don’t price in politics. They price in barrels.
The Fed says the current Fed Funds Rate is “not restrictive” or only “mildly restrictive.” Translation: they want to hike. I disagree, as I’ve said in many prior posts. The pain lands on the poor and middle class, not on the oil market.
You can’t raise rates to get out of the Iran conflict bag.
France has a debt-to-GDP ratio problem at roughly 120%, and the EU isn’t happy about it. The EU has a bond-buying tool for countries whose bonds are collapsing, but France isn’t covered.
Like an expectant father with sympathy pains, bond markets around the world are feeling it too, with yields rising in sympathy.
The Cotality Home Price Index showed home values remaining relatively stable in August.
A CNBC/SurveyMonkey survey shows 87% of renters want to buy a home, and the biggest hurdle is affordability. I can say that from experience with my own kids in their mid-20s: rent is half or more of what it would cost to buy an equivalent home.
With higher interest rates, purchase volume is down 15% year over year, and refinances are down 56%.
We can get through this. Just remember, if the home you want is coming down in price, that helps offset the payment and lessens the blow of the higher interest rate.
Softer economic data out of Europe is helping European 10-year yields move sharply lower, which in turn is helping global yields moderate.
France is talking Quantitative Easing (QE), or in real English, buying bonds. Not just a few billion here and there, but a systematic plan to buy tens of billions of bonds to help lower interest rates.
Reminder: Quantitative Tightening (QT) is what central banks have been doing for the last four years, reducing their bond holdings to shrink their balance sheets.
Quick reminder from yesterday’s post: To keep the same monthly payment you would have had when rates were 6.25%, today’s home price would need to be about 12% lower than it was last March.
Example: a $500K home last March would need to sell for about $440K today to keep the payment the same.
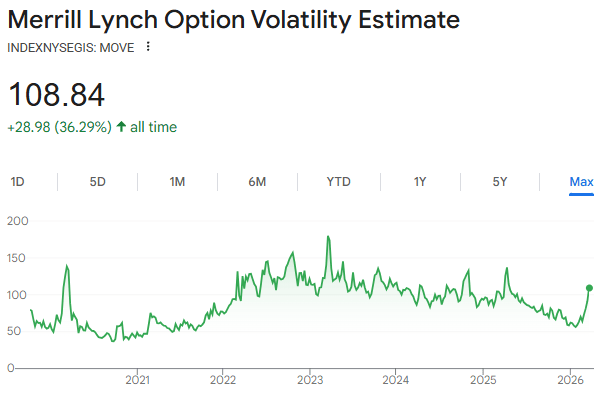
A big part of the bond market volatility, even with underlying weakness in the economic data: bonds initially rallied following the cooler PCE report and much weaker jobs report, but those gains have evaporated.
It’s unclear why, but one possibility is Japan. They are the largest foreign holder of our debt, and they’re dealing with a weakening currency. The weaker it gets, the more expensive imports become, and they import a lot.
The other challenge, which we saw a few years ago when rates touched 8%, is the mortgage spread: the difference between the 30-year fixed rate and the 10-year Treasury yield. The wider the spread, the more volatility and risk the market is pricing in.
Part of the reasoning is that borrowers with high rates will refinance as soon as they can. Investors holding those mortgage bonds get paid back early, losing the high interest they were counting on, so they demand a higher return up front to make up for it.
How to Tackle High Interest Rates
A $100K loan at 6.25% has a principal and interest payment of about $615. At 7.5%, that payment is $699.
The question: How much smaller does the loan need to be at 7.5% to keep the payment at $615? About $88K. That’s a $12K reduction per $100K borrowed.
Scale that up: the payment on a $500K loan at 6.25% is the same as on a $440K loan at 7.5%, a $60K difference. It’s very likely that the home you looked at last spring is $60K less today.
If you want to have your cake and eat it too, with a lower home price and lower rates, you might be waiting a long time. Shift your mindset just a bit: focus on the total payment, not just the rate.
Fed President John Williams: “There is no need for urgency, and the Fed has time to gather more information.”
Translation: A rate hike is unlikely.
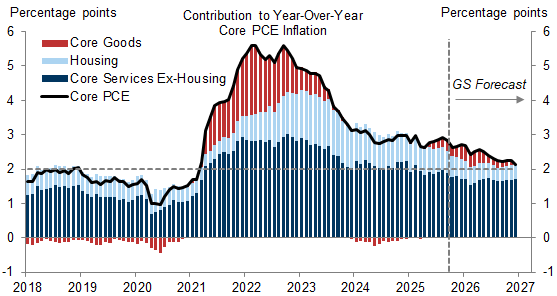
Personal Consumption Expenditures (PCE) came in at 0.3% last month, one-tenth lighter than expected. Year-over-year, it dropped from 3.7% to 3.4% headed in the right direction at this point.
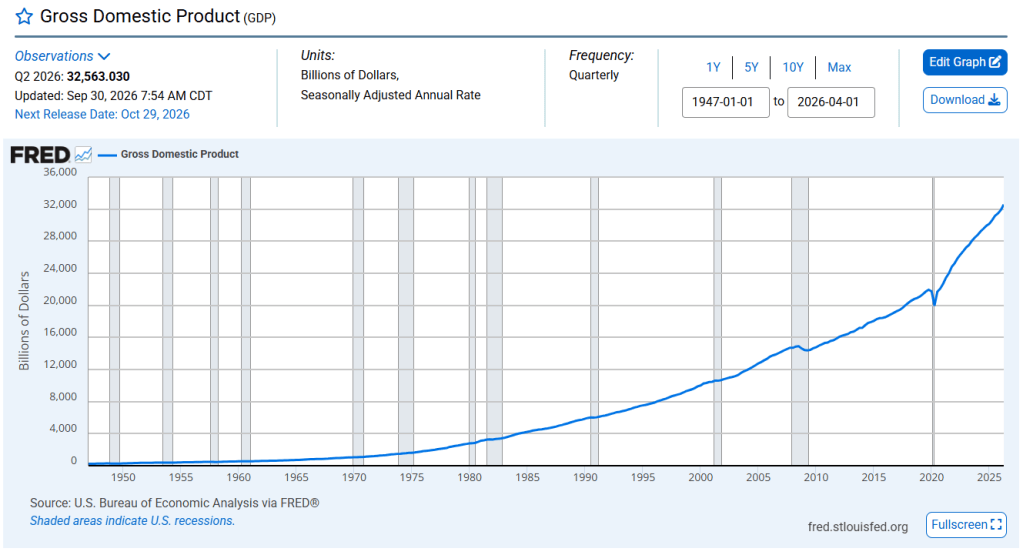
Q2 GDP came in at 2.2%, versus the 1.5% expected.
The ADP Employment Report showed 90,000 jobs created, versus 70,000 expected.
Mortgage applications were down, as expected, with rates still on the rise. Refinances made up 38% of transactions, with most being cash-out.
That’s a bit of a worrying sign. With rates as high as they are, and over one-third of applications being cash-out refinances, something is up. Time will tell.
Mortgage Bonds are continuing lower, with yields higher, meaning mortgage rates keep climbing.
The housing market is stable for now, the way a Jenga tower is stable right before someone pulls the wrong piece. Rising rates mean shrinking approval amounts, and that pressure has to land somewhere, namely home values, as buying power quietly evaporates.
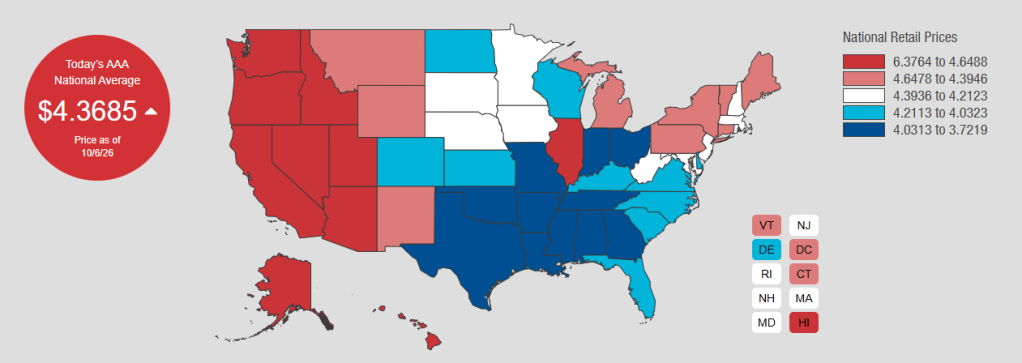
Until tariffs are removed, the Iran conflict ends, and fuel prices drop, we’re stuck standing on a chair missing a leg. Something has to give. Or everything does, all at once, which is the outcome nobody wants.
Job openings in August fell 256,000 to 7.08 million, missing estimates of 7.23 million. The labor market, politely declining to cooperate.
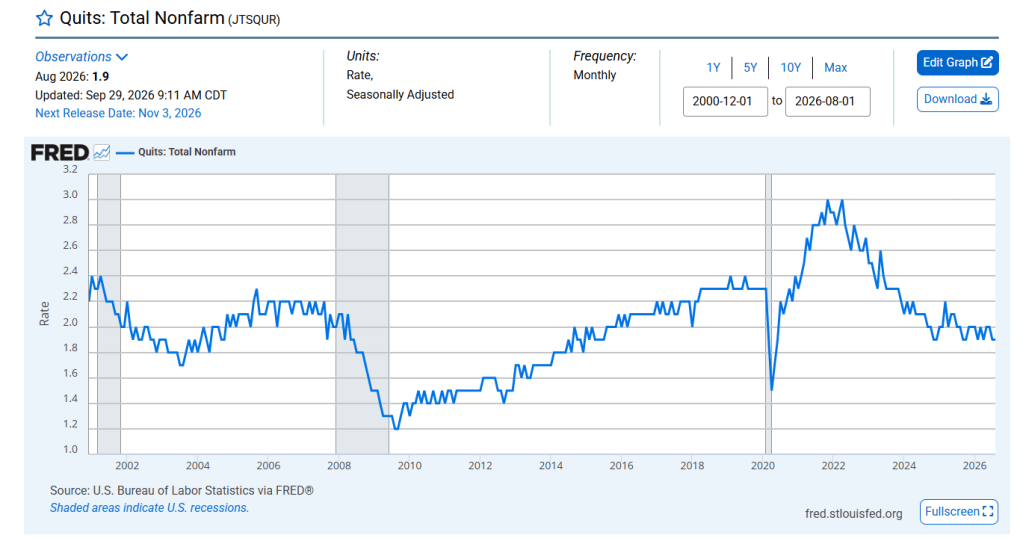
The telling number is the quits rate, still stuck at 1.9%, a measure of people confident enough to voluntarily change jobs. This low, it’s basically everyone deciding to sit very still, a strong signal of a weak job market.
The S&P Global Manufacturing report showed the economy running hotter than expected, triggering expectations for more policy tightening.
Comments on inflation regarding average input costs for goods and services, which surged higher (oil) hit their highest level since 2022.
Comments from Iran’s President at the UN, which were inflammatory.
Fed Governor Michael Barr also contributed to the bond selloff, stating that further rate hikes are likely to be needed.
Suffice to say, it was a bad day yesterday, and today is shaping up to be the same.
Some good news: New Home Sales, signed contracts on new homes rose 6.4% in August, with an annualized rate of 684,000, much stronger than the 620,000 estimate.
Part of this may be due to builders incentivizing buyers with massive rate buydowns and lower prices to move inventory.
If rates remain high, a lot of buyers will stay on the sidelines. Inventory is up, and most markets are softening, meaning there are opportunities to snag a great home at a fantastic price, which can help offset higher interest rates.
The Federal Reserve made a mistake, again. Raising rates in this environment doesn’t fight inflation. It fights the economy, while the actual source of inflation keeps burning in plain sight: oil.
This Isn’t Demand-Driven Inflation. It’s an Energy Shock.
Rate hikes are a blunt tool designed for one job: cooling off an overheating economy where too much money is chasing too few goods and services. That is not what’s happening right now.
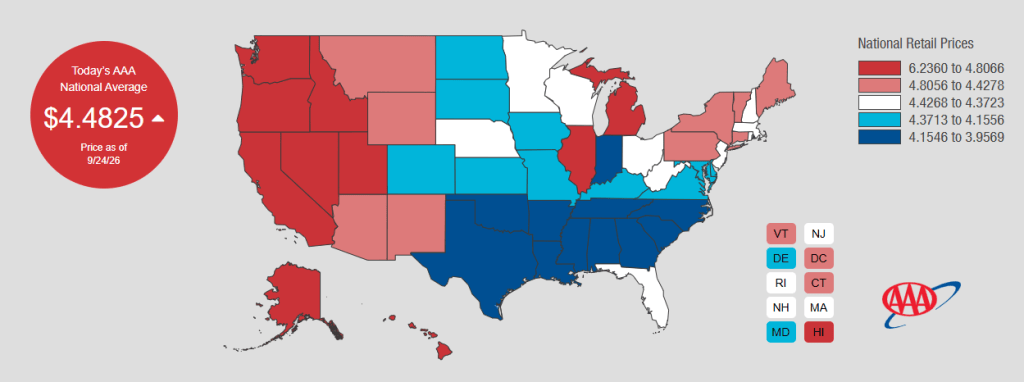
What’s happening right now is a supply shock. Oil is trading well above $90 a barrel, diesel has hit record highs, and the ripple effects are showing up everywhere, trucking costs, shipping costs, food costs, manufacturing costs. Diesel isn’t a niche input. It’s the fuel that moves nearly everything in the economy from a warehouse to a store shelf. When diesel spikes, the cost gets baked into the price of almost everything downstream, whether or not consumer demand has changed at all.
Raising interest rates does nothing to lower the price of oil. It doesn’t reopen a shipping lane, repair a damaged pipeline, or negotiate a ceasefire. What it does do is make it more expensive for businesses to borrow, expand, hire, and invest, piling a self-inflicted wound on top of an external one. The Fed is treating a supply-side energy problem with a demand-side hammer, and the only thing that gets nailed is the consumer and the labor market.
The Jobs Data the Fed Is Leaning On Is Softer Than It Looks
Here’s the part that should really give the Fed pause: the labor market data it’s using to justify staying hawkish is not as solid as it’s being treated.
The BLS jobs report is built on a survey, businesses filling out forms, self-reporting headcounts, with the data collected through phone, fax, and electronic questionnaires. It’s a well-constructed survey, but it’s still a survey, and it comes with real limitations: sampling error, non-response, and a track record of large revisions after the fact. We’ve watched this play out repeatedly, a headline number gets reported, markets and policymakers react to it, and months later it gets quietly revised by tens or even hundreds of thousands of jobs.
ADP’s employment report works differently. Rather than asking businesses to self-report on a form, it’s built from actual payroll processing data, real transactions covering tens of millions of workers who are actually being paid, in real time, through ADP’s systems. It’s not a business estimating its own headcount on a questionnaire; it’s the payroll data itself.
That distinction matters. A survey response and a processed paycheck are not the same category of evidence, and treating them as interchangeable, while giving the survey-based number outsized weight in a rate decision, is exactly the kind of thing that leads to policy mistakes getting locked in before the real picture becomes clear.
The Bottom Line
Inflation right now has an address, and it’s the pump, not the paycheck. Raising rates to fight oil-driven inflation doesn’t lower oil prices, it just slows down an economy that’s already showing cracks, using labor market data that deserves more skepticism than it’s getting. The Fed isn’t wrong to worry about inflation. It’s wrong about the cure.
SIDE NOTE: To be fair, there’s a case for the Fed’s approach too: even supply-driven inflation can become embedded if consumers and businesses start expecting higher prices to persist, and some economists argue that raising rates helps anchor those expectations regardless of the initial cause. There’s also a reasonable argument that the BLS survey, despite its revisions, still benefits from a larger and more consistently structured business sample than ADP’s payroll-based data, and that the two measures are best used together rather than one replacing the other. Reasonable people disagree on how much weight the Fed should put on an energy-driven inflation spike versus the risk of letting inflation expectations drift.
This is generally a good report for the Fed and potentially good news for mortgage rates, but there is an important wrinkle.
July retail sales fell 0.6%, versus expectations for a 0.1% gain. It was the first monthly decline in nine months. More importantly, the control group, which is used as an input into GDP calculations, fell 0.4%.
What does it mean?
1. The consumer is starting to slow down. Consumer spending has been one of the stronger parts of the economy. A significant miss like this suggests households may be becoming more cautious with their money.
2. This adds to the argument that the economy is cooling. Put this together with the weak July jobs report—23,000 jobs lost and the downward revisions to May and June, and we have several indicators pointing toward a softer economy.
3. That’s potentially good news for the Fed. The Fed has been concerned about inflation, but it also has a mandate to support employment. If inflation is coming down while employment and consumer spending are weakening, the argument for keeping rates elevated becomes less compelling.
4. And that’s where mortgage rates come in. The Fed doesn’t directly set mortgage rates, but expectations for future Fed policy influence Treasury yields and mortgage-backed securities. A cooling economy can ultimately create a more favorable environment for mortgage rates.
But here’s the catch…
The market didn’t simply look at the headline and say, “Great, rates are going down.” Some of the weakness was influenced by lower gasoline prices, the timing of Amazon Prime Day moving into June, and other temporary factors. Retail sales are also measured in dollar terms and aren’t adjusted for inflation.
So I would characterize today’s report as:
Weak consumer + weak jobs + cooling inflation = increasingly difficult argument for Fed rate hikes.
But it doesn’t guarantee lower mortgage rates immediately. The market still has to weigh inflation expectations, Treasury supply, geopolitical risk, and what the Fed believes the data means.
For your mortgage commentary, the clean takeaway is:
The Consumer Is Finally Showing Some Cracks. Retail sales were expected to rise 0.1%. Instead, they fell 0.6%. Combine that with weak employment numbers and cooling inflation, and the economy is sending the Fed a pretty clear message: the consumer is slowing down.
That’s exactly what we need to see if we’re looking for a path toward lower Fed rates and eventually, lower mortgage rates.
Have a fantastic weekend and always feel free to reach out to our team.
As I mentioned earlier this week, a few Federal Reserve members stated that the labor market remains robust and even voted in favor of raising the Fed funds rate. Looking at the recent data, I struggle to see the same level of strength.
Tomorrow’s Bureau of Labor Statistics (BLS) jobs report will be a key market-moving event and could play an important role in shaping the Fed’s thinking on whether to hike, hold, or eventually lower the Fed funds rate.
Recent employment data has pointed toward a labor market that is slowing rather than accelerating:
ADP reported only 44,000 jobs added in July.
Revelio Labs estimated approximately 79,000 new jobs, with 28,000 of those in healthcare, suggesting job growth may be concentrated in a limited number of sectors.
ZipRecruiter, one of the nation’s largest job platforms, noted in its recent earnings report that while the first quarter was relatively stable, hiring activity softened noticeably in the second quarter.
Interesting trends beneath the surface. Hiring rates and quit rates have fallen to levels not seen in many years. That aligns with what job platforms are reporting: fewer openings and a more cautious hiring environment.
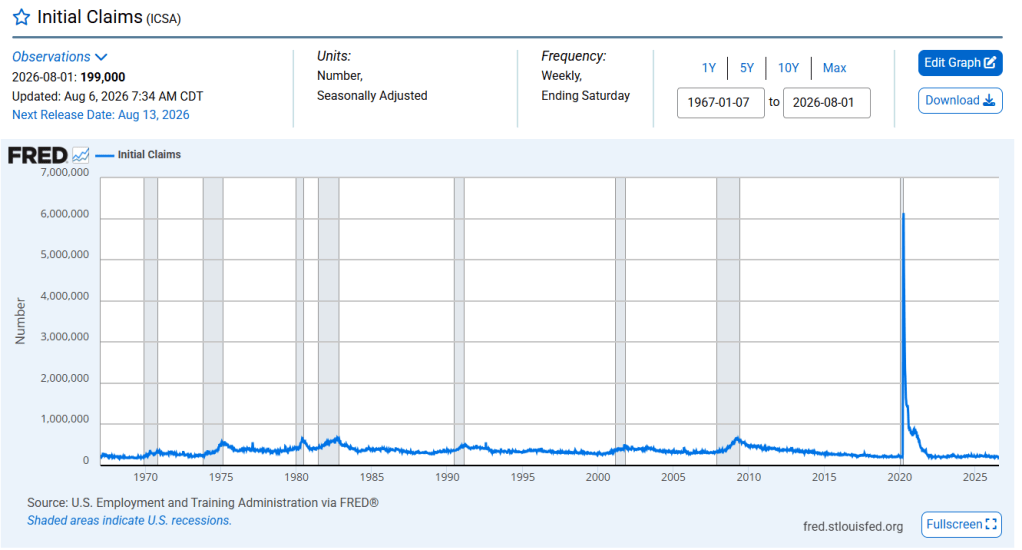
At first glance, lower jobless claims and fewer layoffs may suggest a healthy labor market, but it is important to dig deeper. Employers appear to be holding onto existing workers after years of labor shortages, resulting in fewer new job openings. At the same time, workers may be less willing to leave their current jobs because finding a new opportunity has become more difficult.
In other words, the labor market may not be strong…it may simply be frozen.
That is why tomorrow’s BLS report is so important. It will help answer a key question: Is the labor market truly resilient, or is it gradually losing momentum beneath the surface? The answer could have a significant impact on bond markets, mortgage rates, and the Federal Reserve’s next move.