-
The Feds Balance Sheet and what it means.
Last night I had a dream that I was a Teepee and a Wigwam, My doctor said I was too tense.
The Fed released their balance sheet figures showing it has risen by almost $400Billion in the last two weeks. This is the money banks are borrowing.
The banks are borrowing on their 2% bond collateral at 100% value but borrowing at about a 4 3/8% interest rate. Why would you do that?
Are the banks doing this for safety or do they really need it?
We continue to watch and see what happens next week. Have a great weekend and always reach out.
-
What goes up Must come down
The Federal Reserve said yesterday it would raise interest rates (fed rate not mortgage rate) by a quarter point to a range of 4.75-5.0%. We are still fighting inflation at over 6% every month since October 2021. The target is around 2%.
There is a strong indication that the Feds will pause as the availability of funds for banks to lend to businesses has tightened. This has the equivalent of a quarter point rise.
Think of it this way, if it’s harder for a business to borrow money to purchase new equipment to expand their business, they may not hire additional employees. This has a ripple effect in the broader economy.
It seems strange to slow down a robust economy with low unemployment and consumers continuing to spend but there is a larger reason. If inflation is not controlled, the money you have today will be worth far less in the future.
We continue to see rate improvement this week. call or email with any questions and have a great Thursday.
-
Don’t be Laggin out of fear
Lack of action is its own action. MBA released their Mortgage Application data for last week showing purchases rose 2% after rising 7% in the previous report. Plenty of buyers getting back into the market.
Today is the second day for the Fed meeting with a press conference at 2pm ET. Will the Feds hike, cut or pause. Most smart people in the room think hike .25% but we are looking for indications there will be a pause moving forward.
Disinflation as I had mentioned in earlier posts is real and coming.
Have a great rest of your week.
-
Is it safe to go back in the water?
Stock market is higher, Bond market a bit lower. The Feds Kick off their 2-day meeting with a statement and press conference at 2:00om ET.
Existing Home Sales, which is a measurement of existing homes sold were up almost 15% in February. This is much stronger than the estimated 5% gain. Sales were down 37% Y/Y in January but February is 22% Y/Y. We are making progress.
Inventory Inventory Inventory is very low at 980,000 but up 15% over last year. There is a 2.6 months’ Supply of homes currently. 4.6 months is considered normal. Active listings are only 578,000 or 1.5 months of inventory. It’s a very tight market.
First Time Home Buyers account for 27% of sales down from 31%. Cash buyers account for 28% of sales down from 29%. Investors made up 18% up from 16%. Investors are seeing the opportunity.
Check back in tomorrow to see what the Feds have to say.
Have a great rest of your week.
-
How can I miss you if you won’t go away?
What’s happening in the banking industry today is far different than 2008. The banks have taken duration risk meaning the assets in the long run are very strong.
Think back to 2008, the word I kept hearing was Derivatives.
Derivatives are financial contracts, set between two or more parties, that derive their value from an underlying asset, group of assets, or benchmark.
There were bad loans with lipstick, cobbled together with A paper loans wrapped in Adjustable Rate Mortgages. Nothing good was going to come of that.
What we have today is an artifact of eased regulations, Fed hikes and Executive greed. The foundation of the Banking system is strong.
Rates continue to improve, get out there and show them who’s Boss.
-
Nowhere to run to, Nowhere to hide….
One of the challenges for money managers is where to put their money. Do you buy stocks or flight to safety, securities. If both these markets are getting beat-up, what’s a money manager to do?
Diversification is key but if all your options have challenges you have to look elsewhere. I’m not sure what the answer is but historically real estate may be a valid option.
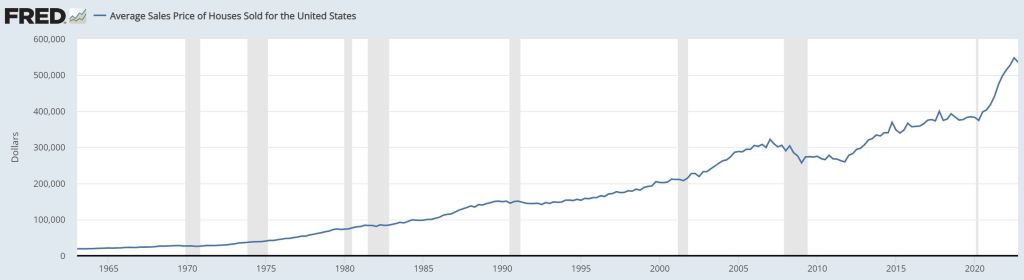
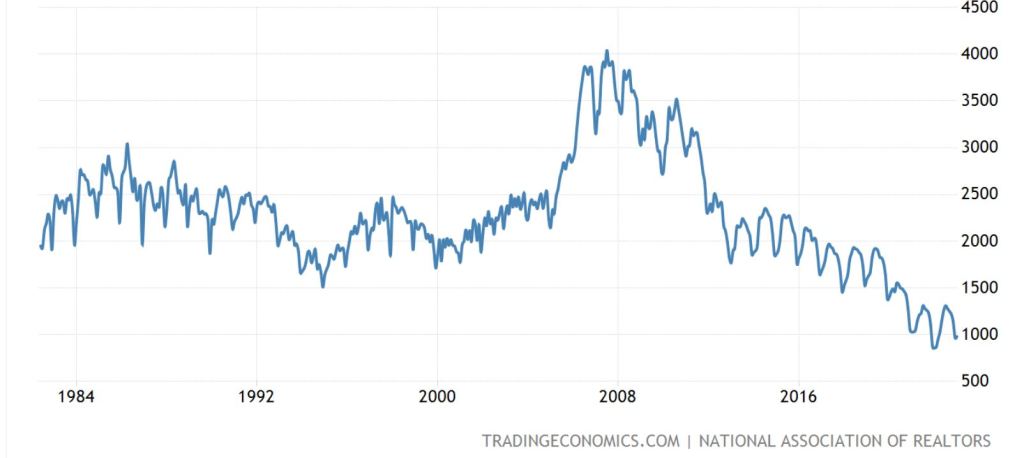
Inventory is low, very low. Demand is high and the rates continue to drop.
Have a fantastic weekend. I updated a few of my YouTube videos. Enjoy
-
What does Sanguine mean in regards to the Banking situation?
Definition, adjective – Optimistic or positive, especially in an apparently bad or difficult situation. “He is sanguine about prospects for the global economy”
European Central Bank (ECB) hiked rates 50bp this morning. Stocks dropped but have recovered for the most part. What will the Feds do March 22nd. Do nothing or explain the hike is the last for a long time.
Remember our inverted curve; the 2y bond has been outperforming the 10y. this is not normal. we are seeing a “de-inversion” on the horizon indicating a start to the recession.
This is very good news for rates. We have seen a demonstrable change in rates over the last week and expect that trend to continue.
It’s Thursday but sure feels like it’s been a month. Have a great rest of your week and always feel free to reach out.
-
We continue to see rate improvement
The dust is still settling in the banking industry and has caught a few European banks off guard. We are not quite out of the woods as a few more trees may fall.
Credit Suisse’s struggles looks to be unrelated to the regional U.S. banks, the combination could prompt a reexamination of the banking system.
We continue to see rate improvement this week and expect this to continue. Next week the Feds meet, we will see what happens then.
On a happy note, a Japanese company received a Guinness World Record when it harvested a giant radish that weighed in over 101 pounds.
Manda Fermentation Co., is a supplement and fertilizer company.
Have a great rest of your week and call or email anytime.
-
CPI Numbers as expected, Inflation easing if only just a bit.
The big news this morning is no news or at least the news we expected. The CPI (Consumer Price Index) came in as expected at 6%. Inflation still is stubbornly high but continues to go down. I personally prefer to see this in graph form below.

The Feds meet next week and are expected to raise rates 0.25% from the expected 0.50%.
We continue to watch the aftermath of Signature bank and Silicon Valley Bank. These are both unique situations though it has rattled the market and consumers.
Have a great rest of your week and yes its only Tuesday. Feels like Friday already.
-
This might be the straw
As we are now aware, we have had three regional bank failures and a lot of nervous deposit holders. Investors are reassured by regulatory actions to limit the fallout. Specifically, that SVB depositors will be protected.
We hope the FEDs will pause and see what they have done. Let’s hope they move less aggressively raising interest rates.
From a bond perspective, we are seeing one of the largest rate improvements I have seen in the last five years. As of last Thursday, we have seen a 159bp (basis point) drop-in rates. The national average rate went from 7.126% to 6.879%.
So, what happened to Silicon Valley Bank.
How did SVB get here: During the pandemic they had a huge influx of deposits. Some of those deposits they made loans, while other funds were deposited in Securities i.e., bonds. The underlying issue was the Fed raising rates. When the rates rose, those purchased bonds lowered in value. This is not a problem unless you need to sell early.
Deposits started to leave the bank faster than they anticipated which forced SVB to sell the bonds at a reduced price and took a loss. Last Wednesday they announced they needed to raise capital the next day, and that panicked the depositors. The stock sold off and in one day 42 billion dollars was withdrawn. SVB was forced to meet draw demands. They sold $21B and forced to take a $2B loss.
How Significant is the collapse: it matters because it could panic other parts of the banking system like Signature bank and First Republic, who announced they received funds from the Federal Reserve and JP Morgan.
What could happen next: The Key thing to watch is, are the investors and depositors reassured. Time will tell.
Call or email with any questions.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

