-
Don’t Pull the cord on the bus until you are ready to get off.
The Federal Reserve finds itself in a state of uncertainty, pondering whether to raise interest rates in the upcoming week or wait until the following month. The dilemma arises from the fact that while inflation is decreasing, the recent job numbers have surpassed expectations, as highlighted in a blog post published on Friday.
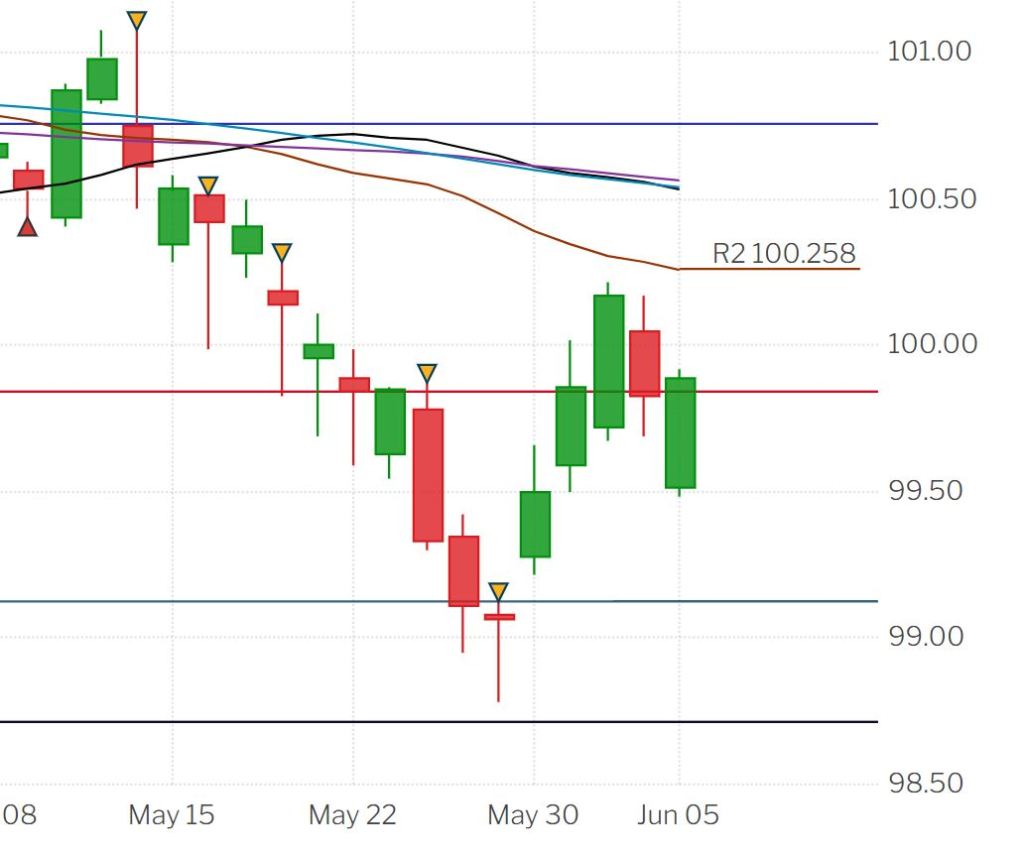
What are the current interest rates. It’s important to understand that this is a complex question influenced by numerous variables. Interest rates fluctuate daily, and the chart below provides a snapshot of the rates over the past month, with a downward trend indicating higher rates.
When you pose this question to your lender, their brief pause indicating how best to respond. This hesitation arises from the intricate nature of the question and the need to factor in various elements before providing an accurate answer.
Translation, it drives us crazy. but seriously there are so many different factors, its impossible to be accurate.
Have a fantastic Monday and the rest of the week is ahead of us.
-
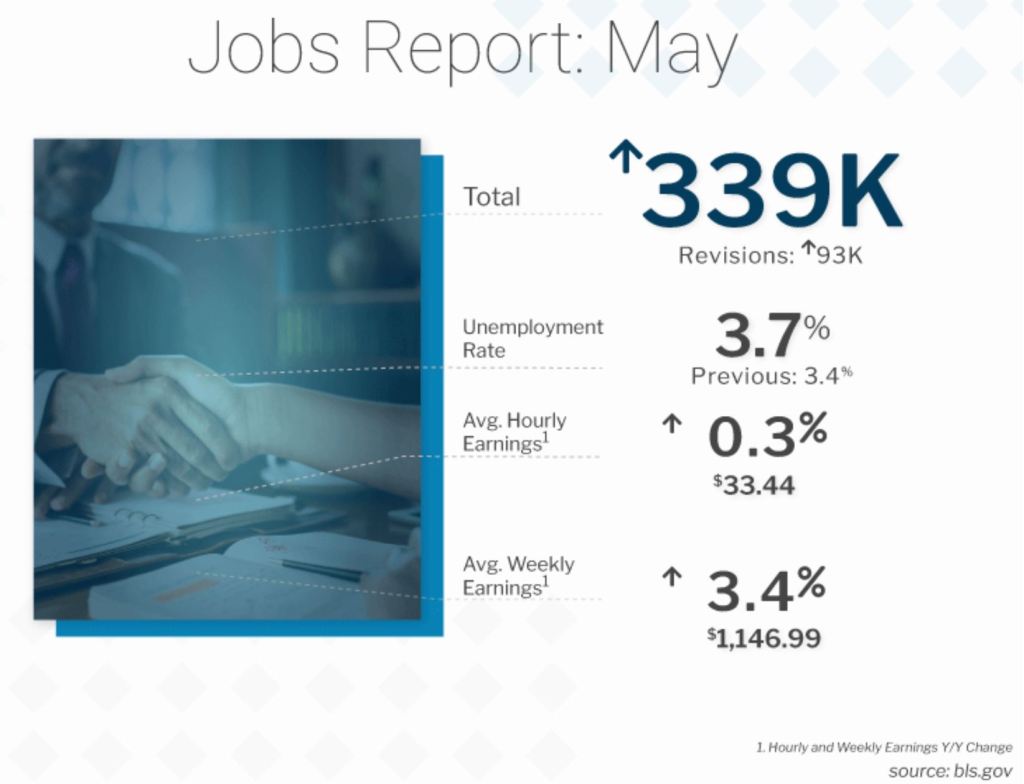
Wow, 339k new jobs, blows the estimate away.
The unemployment rate has inched up to 3.7%, but the number of new jobs has far surpassed expectations, slightly impacting the rates.
Although the Federal Reserve’s actions remain uncertain, knowledgeable individuals in the room are increasingly inclined towards a rate hike.
Notably, the Household Survey revealed a loss of 310,000 jobs, which accounts for the elevated unemployment rate.
Its Friday, already. Another weekend ahead of us. Enjoy and always feel free to reach out.
-
What’s in a Rate
We have witnessed significant improvements in mortgage rates as the resolution of the debt ceiling becomes inevitable. This development raises a question previously posed regarding the difference in house payments between a 3.5% 30-year mortgage and mortgages with rates of 6.5% and 5.0%.Comparatively, a 6.5% mortgage results in a 30% higher total payment, while surprisingly, a 5.0% mortgage leads to only a 15% increase. This difference is viewed as the tipping point for borrowers who are constrained by interest rates.
With these changes on the horizon, it is crucial to be prepared. We encourage you to reach out to us or your lender and get pre-approved. Obtain a fully underwritten file to address any minor issues that may arise.
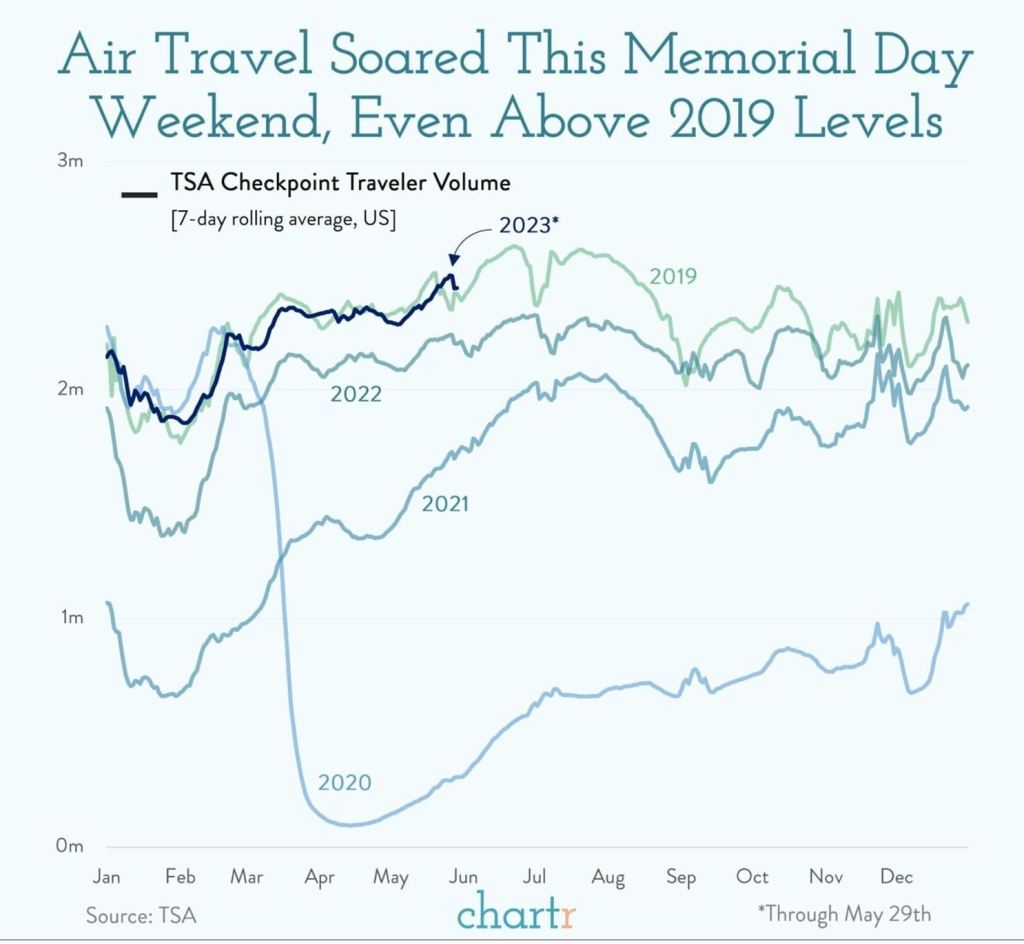
As I am currently traveling this week, I came across an intriguing graph that I wanted to share with you. It’s quite fascinating! Have a fantastic rest of the week.
-
Rate improvement
This will be a short post today. Headed on a plane to change the weather and a few meetings.
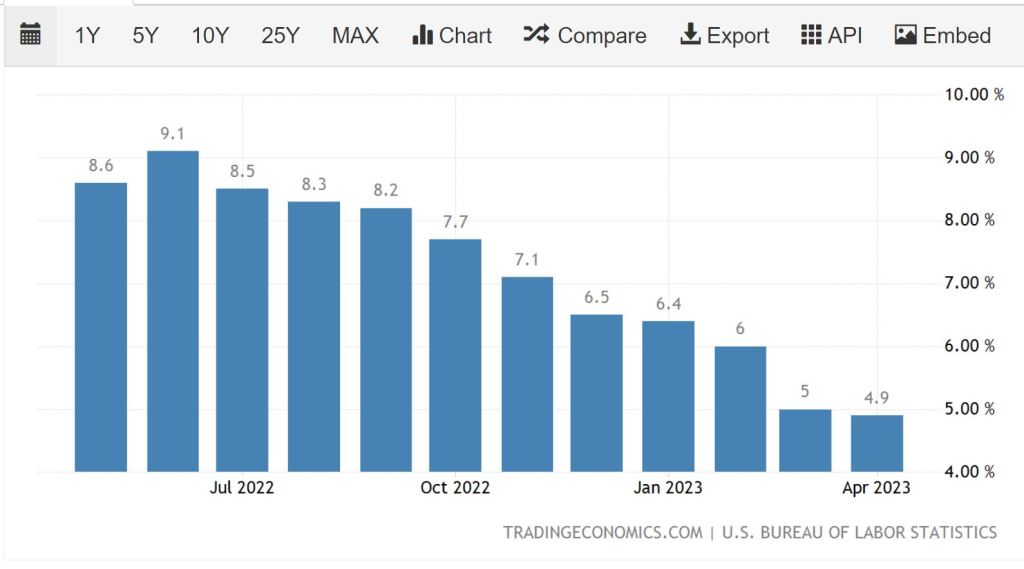
Rates have improved quite a bit the last few days with the debt ceiling deal almost behind us. Also the Inflation indicators are looking more and more favorable as we move into June.
Have a fantastic rest of your week.
-
Debt Ceiling, Stock Market and Rates.
Its appears we are out of the woods with regards to the debt ceiling but what does that mean for the Stock market and interest rates.
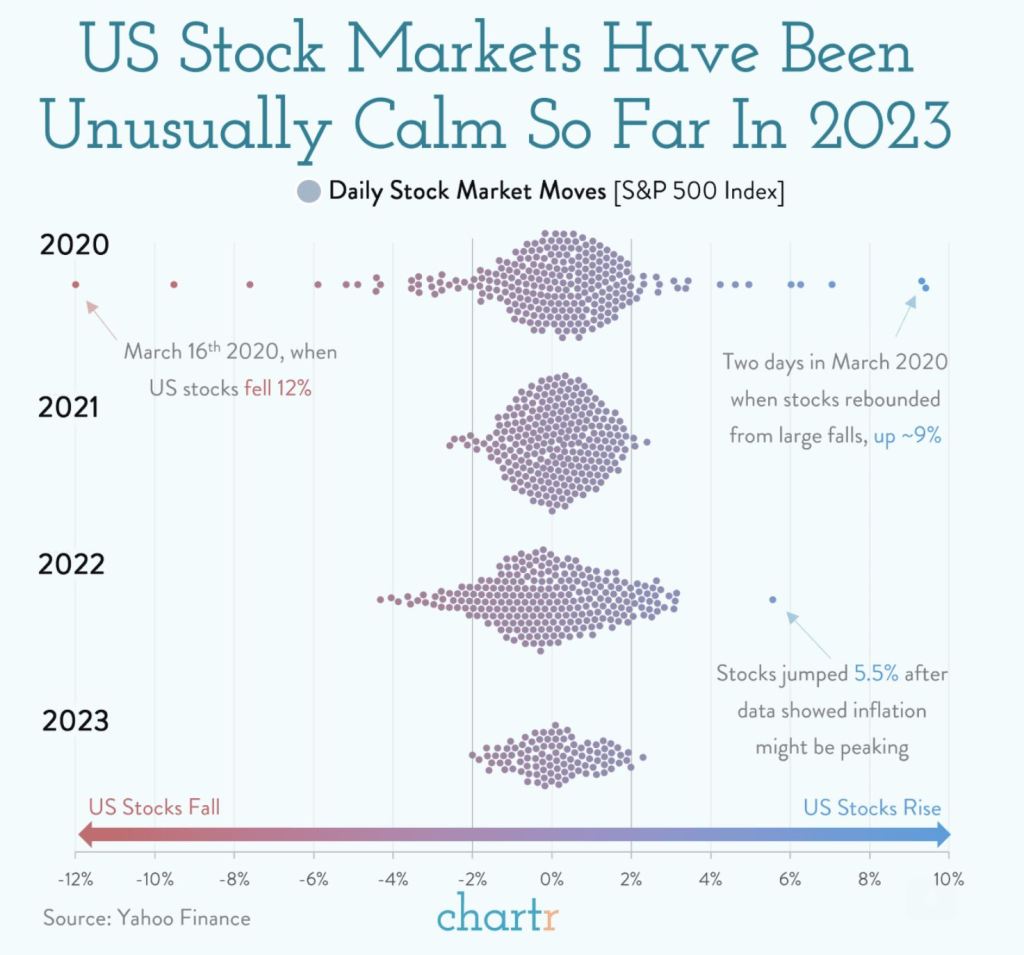
The first chart is the Stock Market activity last 3 years. 2023 so far is calm very calm. Operating in a narrow +-2% range.
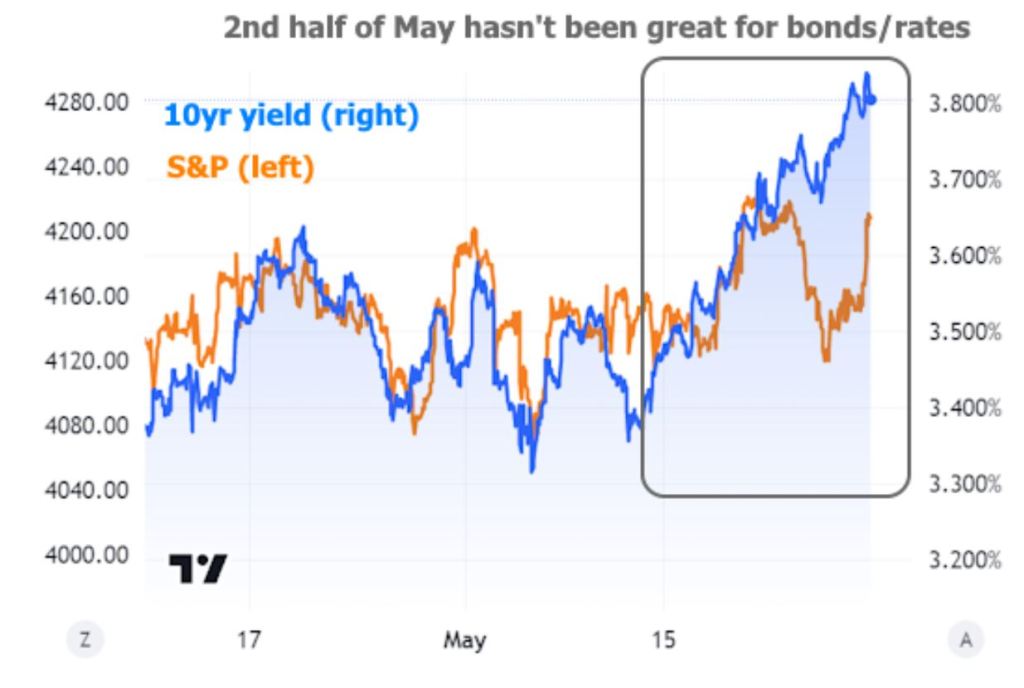
The Bond Market has been steadily rising this month, not helping interest rates.
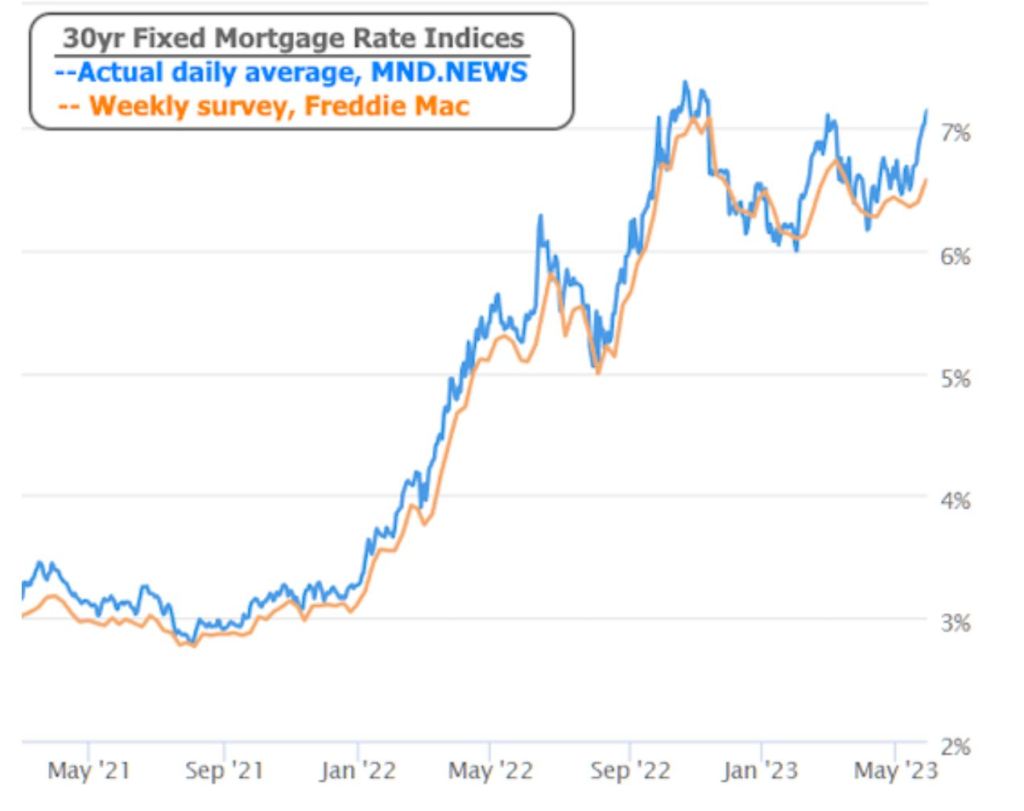
Interest rate peaked over 7% last week according to the daily Average.
Its a short week with ADP employment report and initial jobless claims.
Have a great week and always feel free to reach out with any questions.
-
PCE (Personal Consumption Expenditures) Inflation Report not cooperating (Silver Lining)
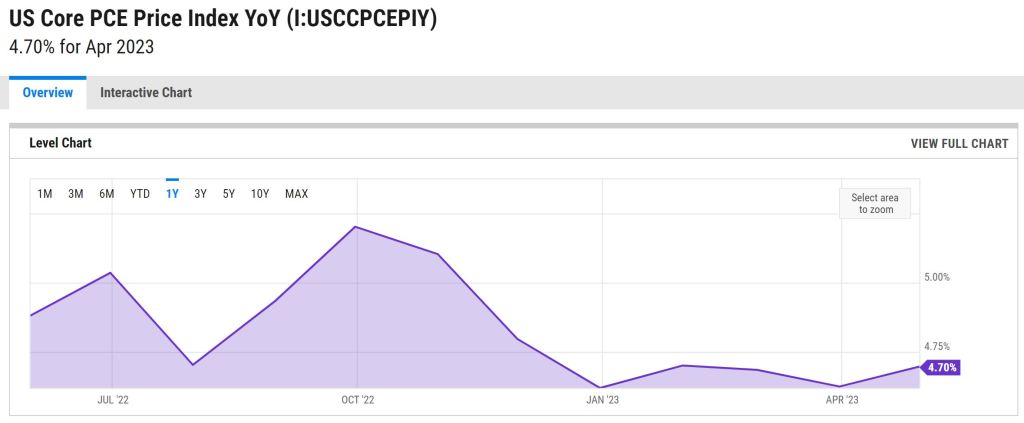
The past two weeks have been challenging for rates, as indicated by the latest data on Personal Consumption Expenditures (PCE). Inflation has increased by 0.4% in April, surpassing the estimated 0.3% rise.Energy rose 2.4% last month and Used Cars up 4.7%.
There is indeed a positive aspect to consider. We expect to observe progress in the coming two months due to higher comparisons with last year’s inflation rates. It’s important to note that we are focusing on year-over-year inflation comparisons.
Looking back at 2022, the inflation rates for May and June were 0.6% and 1.0%, respectively. If we continue to see readings around 0.4%, we can anticipate a decrease in year-over-year inflation from 4.4% to 3.6%. Furthermore, we project that inflation will decrease even further once the pressure from energy, used car prices, and shelter costs subsides.
Have a fantastic long weekend. Bond Market will be closing today at 2:00pm ET in observance of Memorial Day Holiday and the markets will be closed on Monday.
-
New Construction grabs 33% of the Home market Up from 10%.
According to the National Association of Home Builders, builders emphasize the scarcity of listings in the resale market, which grants them a significant advantage. Despite national average interest rates exceeding 7%, prospective buyers exhibit a strong preference for new homes.
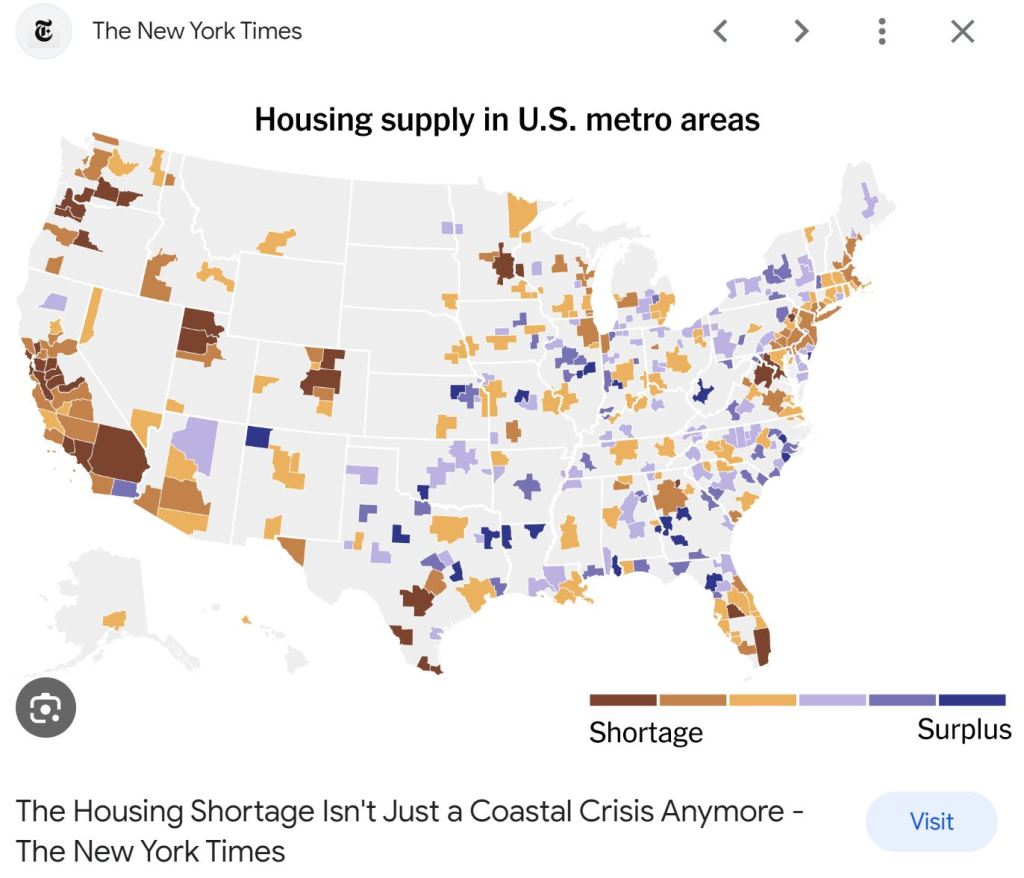
Just a friendly reminder, if your mortgage rate is 6.5%, your monthly payment will be 30% higher compared to the same mortgage at a rate of 3.5%. However, if the rate is 5.0%, your payment will only be 15% higher.
It’s Thursday, which means that tomorrow is Friday heading into the three day weekend.
-
Give a Mouse a Cookie and they will ask for Milk.
The Feds have put themselves in an untenable position. With a recession looming and inevitable, they are stuck. If they cut rates, it will help the banking sector, specifically the regional banks, making the recession less painful.
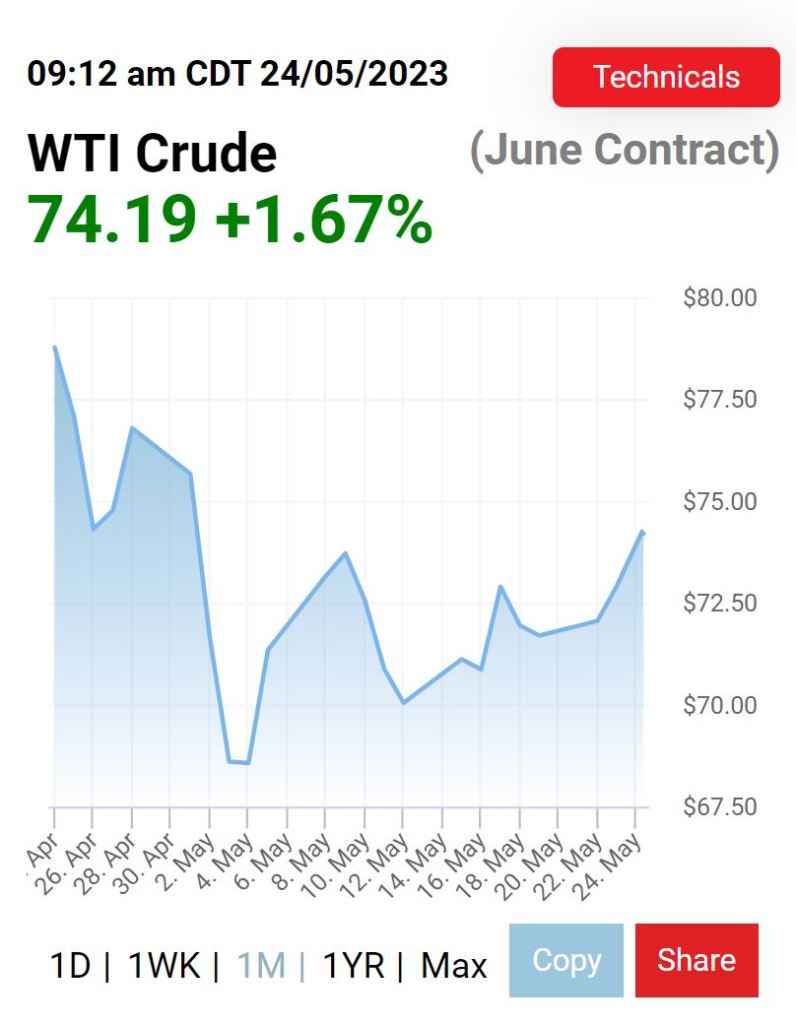
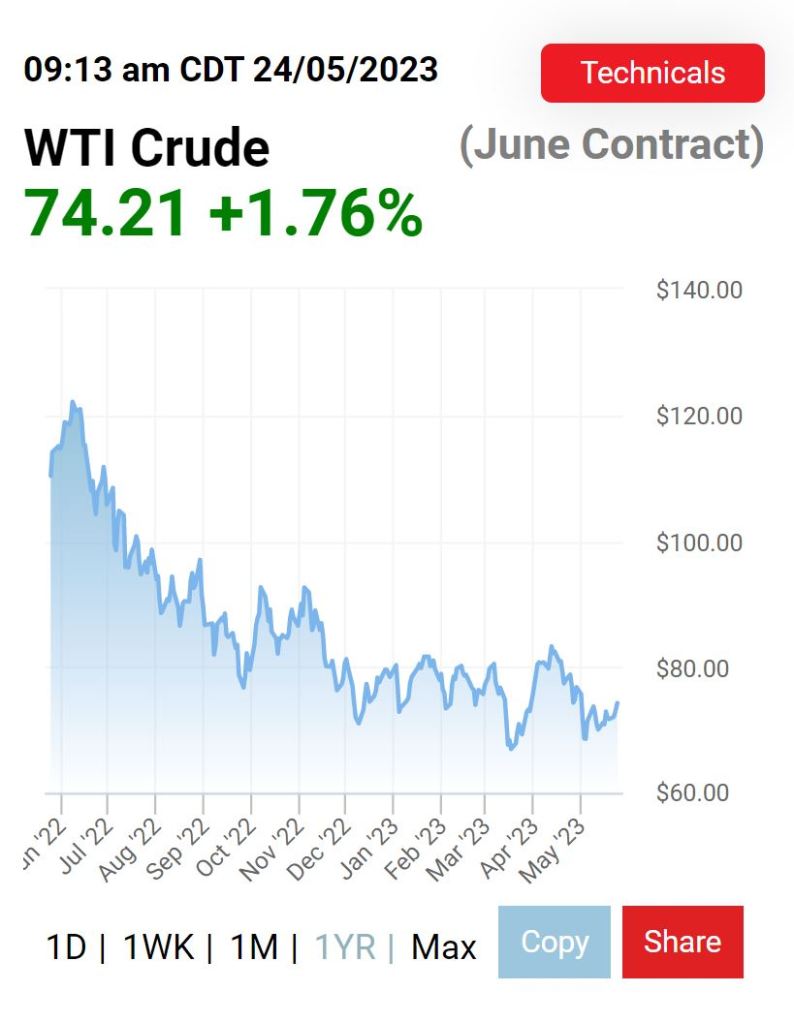
Oil prices are dollar dependent so if the Feds cut rates too much, oil prices move higher. Oil is holding around $73/barrel up just a bit after the Saudi Energy Minister comment to “watch out”.
This graph is the last month, but take a look at the second graph spanning the last 12 months.
-
The Bond Market has nothing to chew on.
We have entered a lull in the bond market ahead of Memorial Day weekend. No key reports or events except for the debt ceiling ordeal.
We are waiting for rate-friendly data as we are seeing the rates inch higher last week and into this week.
Have you ever wondered what all those numbers on Oil cans mean? Have no fear I am here to help.
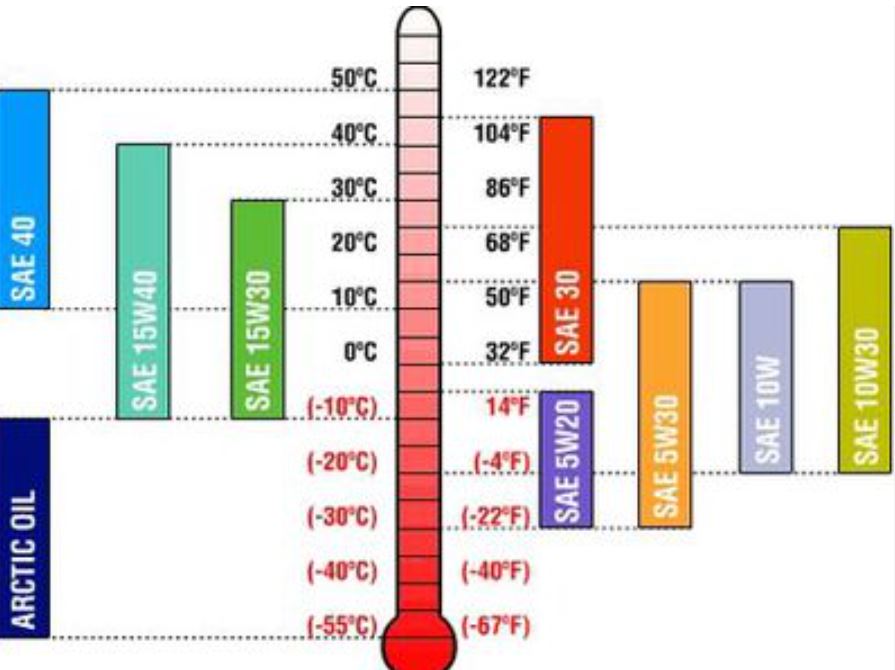
It’s Tuesday Morning, take on the day and I will see you tomorrow morning.
-
If Inflation is Down and Shelter Costs are Down, why are the rates not following?
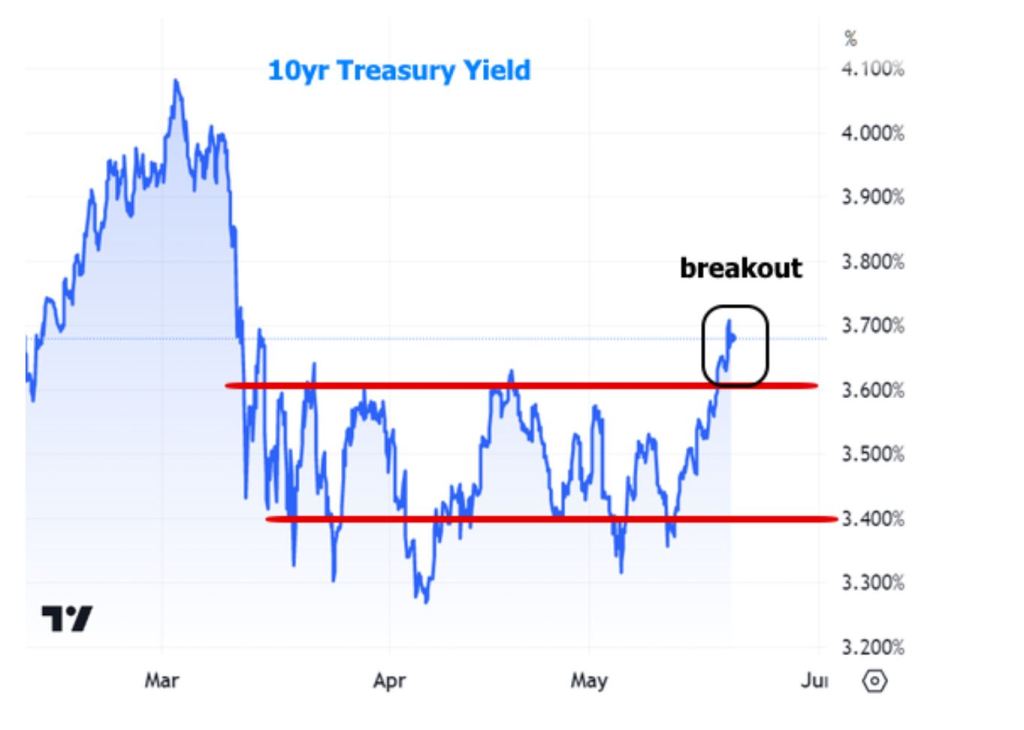
We are in a conundrum. Supply and Demand for Mortgage bonds are the issue. The FDIC who assumed $114B in Treasuries after SVB and Signature bank went under and Banks are selling their Bonds in an attempt to raise capital for depositors. Those depositors are taking their money and investing it in better options.
In 2021 the opposite happened. Inflation was moving higher causing rates to move higher, but rates did not. The reason was the FED was doing the lion share of buying of MBS – Mortgage Backed Securities and Treasuries.
We just need to weather the storm. It’s temporary and all this selling will be exhausted.
Monday morning, Make it a great week.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

