-
What’s an acronym between friends. GDP, GDI, CPI
GDP is the Gross Domestic Product and is used by economist to measure national economies by size.
GDI is the Gross Domestic Income and is a measure of a nation’s economic activity based on all the money earned.
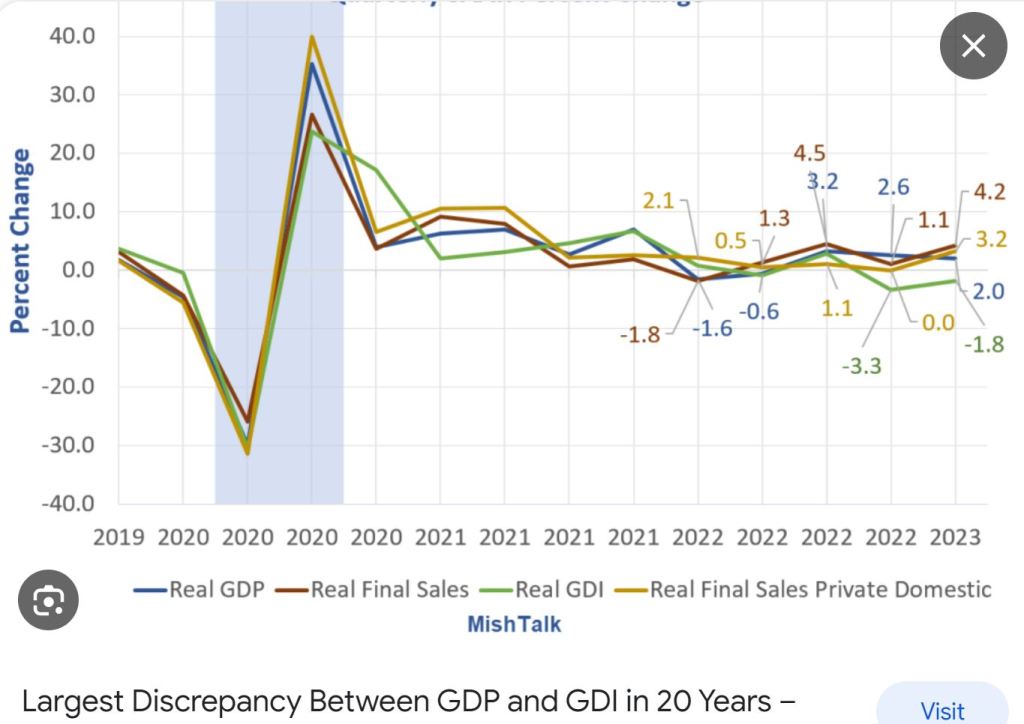
In theory, GDI should be identical to GDP which has been showing more strength than expected. GDI on the other hand has been negative for two consecutive quarters.
Think of it this way. GDP is the value of the goods, services and technology. GDI is what all participants in the economy make like wages, profits and taxes. Right now the trending data is telling us we are making more but getting paid less.
Look at the Blue GDP and Green GDI lines.
-
What are FED minutes and why its Important.
This afternoon, last week’s Fed minutes will be released. This is essentially a transcript of the Fed meeting and should give us a better glimpse into the thought process of the Fed. We expect the Fed may hint at a hike at the July 27th Meeting. This is expected to be challenging for the Bond market i.e. higher rates.
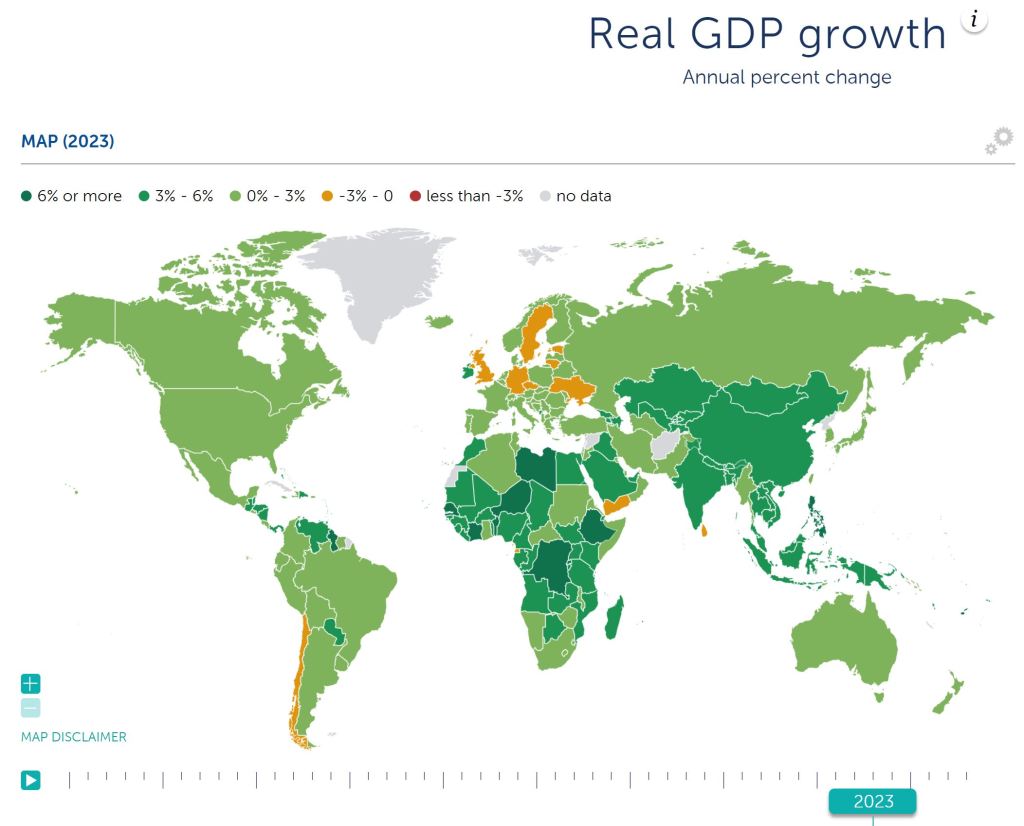
Regarding GDP Gross Domestic Product., the estimates for Q2 are 1.6% to 1.4% annualized growth. This is a slowdown in the economy and a heavy indicator of a pending recession if there are two consecutive quarters of negative GDP.
We expect and historically every time we enter into a recession, inflation and mortgage rates decline.
-
Analysts have a Tendency of falling in love with their Forecasts.
We keep hearing the sky is falling (recession) but the Can keeps getting kicked down the road.
Last week we had bullish updates on durable goods orders, business investment activity, new home sales, home prices, consumer confidence and initial jobless claims.
GDP Gross Domestic Product on Thursday grew in Q1 at a much faster pace than previously estimated.
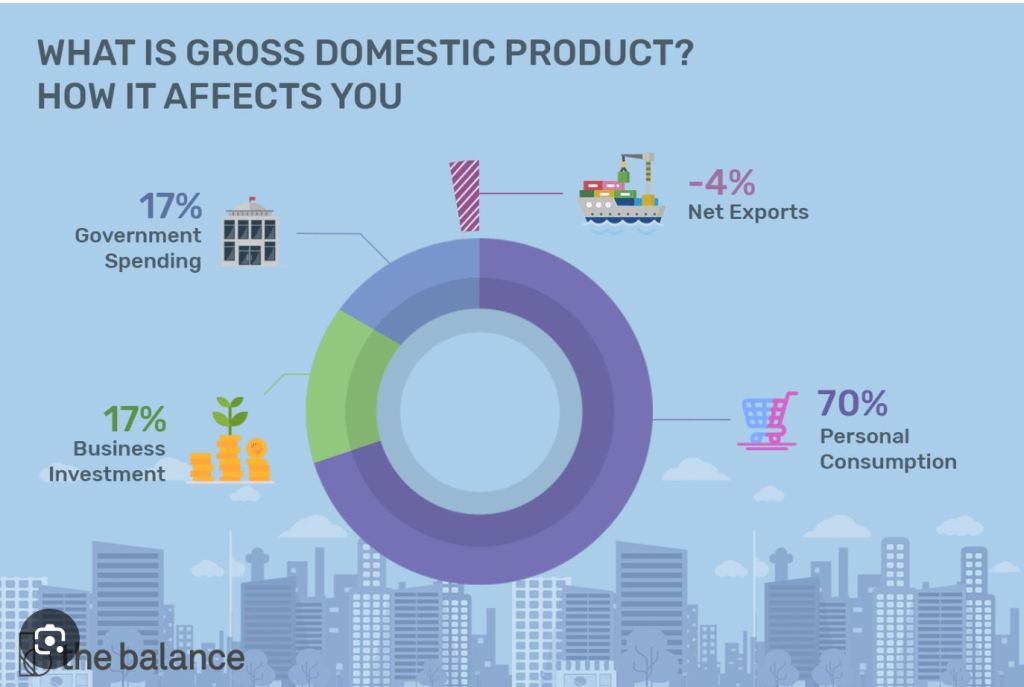
Many of the bearish economists are now dialing back their calls for a recession.
Here is an example of Bearish (negative) thinking:
Home prices: When they’re up, it’s bad because it means fewer people can afford to buy. When they’re down, it’s bad because existing home owners are seeing their net worth shrink and some could go underwater on their Mortgage.
Happy 4th of July and as always, available for any questions that might come up.
-
Jobless claims lower, Rates Higher, Feds watching!
Economically speaking a very strong positive report. The downside is the economy is cruising right along and not slowing down. This affects the bond market as the Feds are eyeing two additional rate hikes this year.
As I write this blog, I wondered who might not be on the internet. Well of course everyone is right??
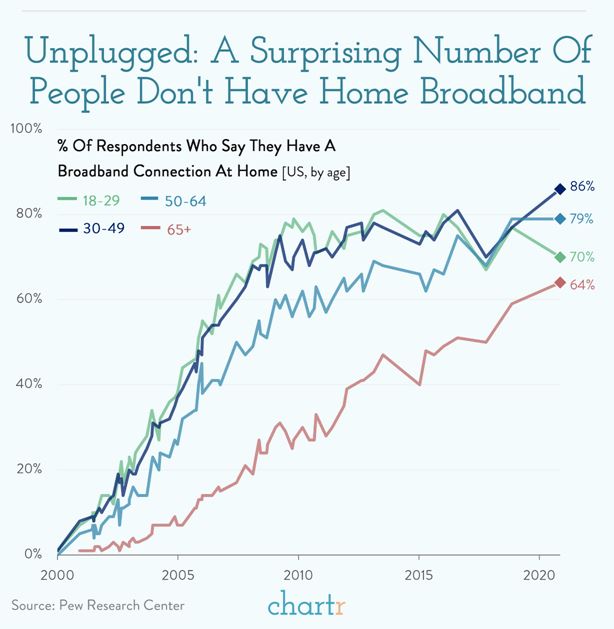
I am headed to Disneyland next two days, ahead of the long weekend and 4th of July. Always feel free to reach out anytime.
-
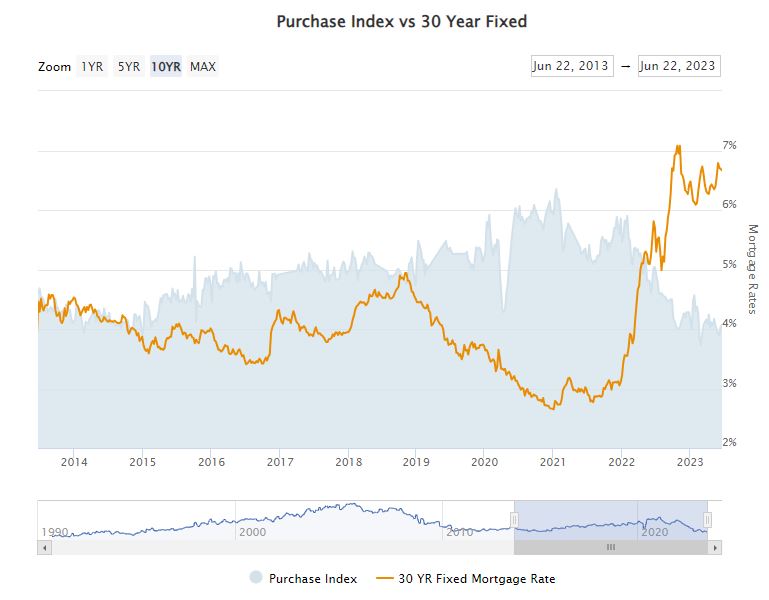
Mortgage Applications Rose, Third straight week.
Given yesterdays strong new home sales and earlier improvement for pre-owned homes, Mortgage application volume is up.
Tomorrow we have Pending Home Sales and Initial Jobless Claims, Friday Personal Consumption Expenditures. We anticipate continued rate improvement.
-
New Homes sales up 12.2% and how efficient are Electric cars
New home sales and completions are up 12.2%, which is great news but we have our familiar frenemy inventory. Low inventory means home values continue to go up, great for sellers but not so great for buyers.
Interest rates and inflation are just not budging. As a lender this is frustrating. We have a large swath of clients sitting on the sidelines either because of fatigue trying to buy or not willing to sell until the rates go down.
I don’t have a good answer for you except time heals all wounds.
Found this graph interesting. EV’s tailpipe emissions are zero but producing the raw electricity is carbon heavy.

Always feel free to reach out anytime.
-
63% of all Homeowners have Mortgages and gained $1 trillion in equity.
How can you harness that valuable resource of home equity without jeopardizing your low mortgage rate? The United States is currently experiencing a record level of home equity, surpassing $27.8 trillion.
Traditionally, accessing your home equity while maintaining a low mortgage rate would involve providing comprehensive documentation, such as paycheck stubs, W2 forms, or tax returns. However, there are alternative options available that leverage the equity in your property. These are referred to as low doc or no doc loans, also known as SIVA (Stated Income Verified Assets) loans.
With low doc or no doc loans, the emphasis is less on extensive documentation and more on the value of your property’s equity. These loans enable borrowers to state their income without extensive verification, while the focus shifts towards verifying the assets they possess.
By opting for a low doc or no doc loan, you can tap into your home equity effectively, allowing you to access the funds you need without disturbing your low mortgage rate. These loans provide flexibility and convenience for borrowers who may have unconventional income documentation or prefer a streamlined application process.
It’s important to carefully consider your financial situation and consult with a qualified mortgage professional to determine the best approach for leveraging your home equity while safeguarding your low mortgage rate.

Have a great rest of your week.
-
Contractionary Territory
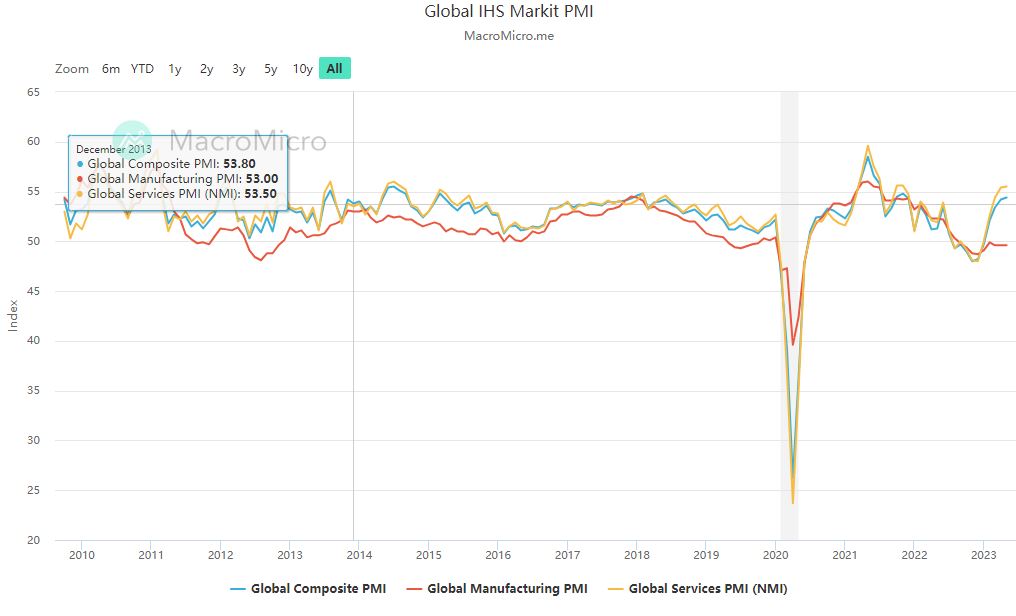
The Global PMI (Purchasing Managers Index) report came out this morning showing evidence of a global slowdown.
Below we are specifically looking at the orange line showing14 months of contraction. We are also seeing a slowdown in the US, as evidenced by the Leading Economic Indicators repot
Rates are still stubborn as always as we look towards July and August for relief. Have a great weekend.
-
Inventory is Up and Homes are selling.
Existing Home Sales showed sales rose 0.2% in may at a 4.3M unit annualized pace. This is stronger than the estimated 1.0% decline.
Inventory levels increased slightly to 1.08M but are still very low. There is a 3 Months’ supply of homes. to put this into perspective, 4.6 months is considered normal.
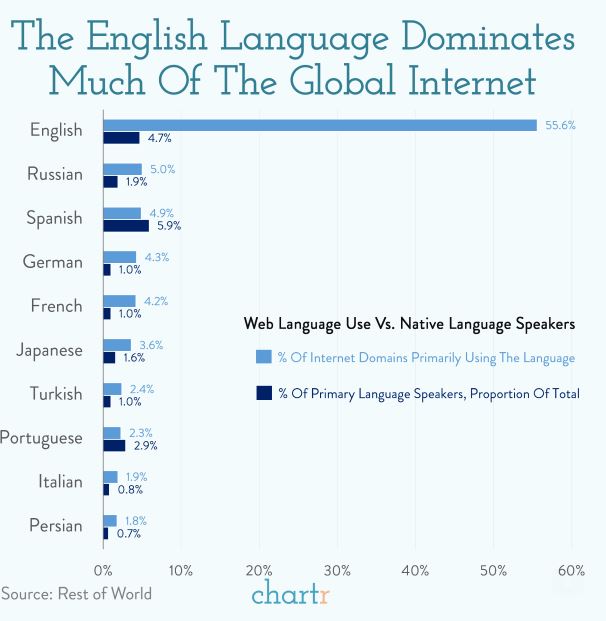
I thought this was interesting given I am currently on the internet and never actually thought about the dominance of the English language.
Have a great rest of your week.
-
If the Shoe don’t fit, it just ain’t your Shoe.
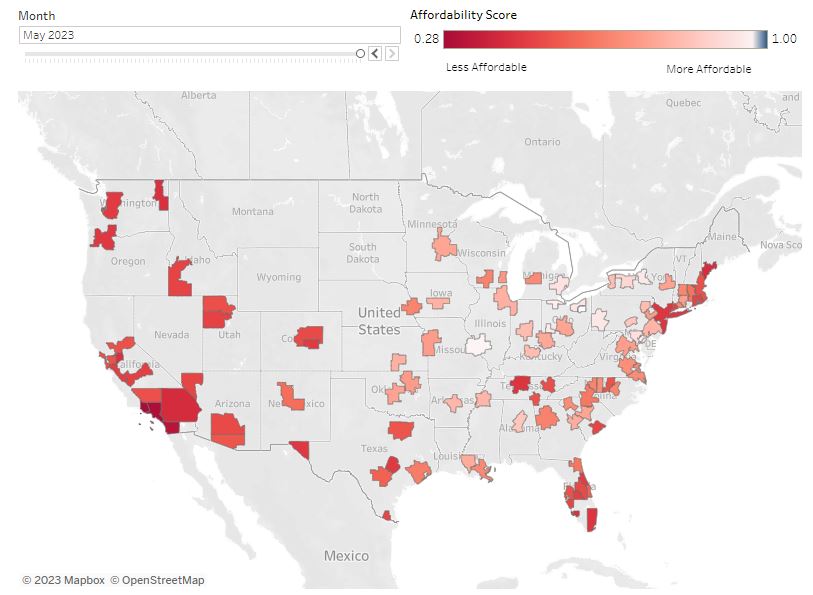
It’s possible that you find yourself living in a home that simply doesn’t suit you anymore, either because you have outgrown it or were compelled to purchase it within the past two years.
While it’s true that the interest rates have increased significantly compared to two years ago, it’s worth noting that once the rates reach the 5% range, the monthly payment only rises by approximately 20% compared to the existing total payment.
Have a great rest of your week.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

