-
Consumer cash buffer dwindling
There is an interesting correlation between inflation and Savings. Inflation generally is more demand than product. Demand requires ability and that ability is cash.
The dwindling cash reserves puts pressure on corporations to compete with fewer buyers causing the prices to drop.
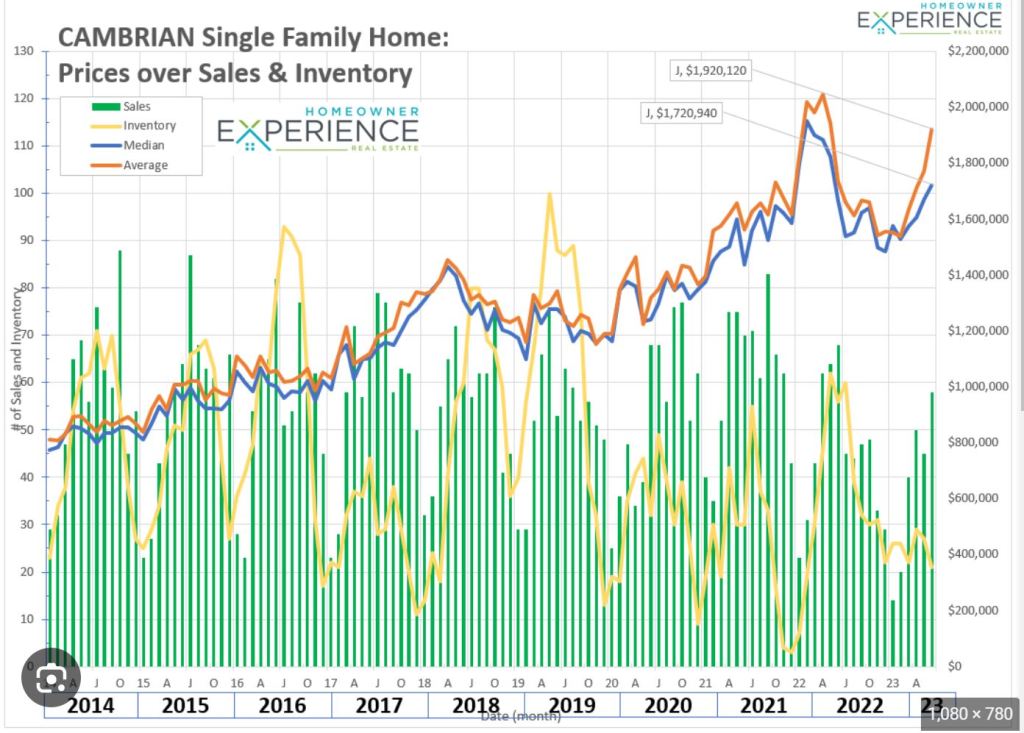
The housing market on the other had has low inventory and high prices.

Existing home sales fell 3.3% in June. Y/Y down 18.9%. Inventory is half the levels we saw in 2019, a year that was already tight. Homeowners with low interest rates or own their home outright are the artifact of this low inventory.
-
Time to get off the porch and go find a Home.
Getting pre-approved for a mortgage is more important now than I have ever seen. Low inventory demands a clean and attractive offer. To that end, a full underwritten approval is not only necessary but required by more and more sellers.
If this is your first time buying or you are a pro, dust off the W2s and get you qualified.
Below video steps through the process.
Always feel free to call or email.
-
“You want a statement made by someone other than a nut, but, by making such a statement, that person becomes a nut”
Yesterday when I was surfing the financial channels I heard a voice that said “We do not expect a Recession, soft landing or otherwise”.
Get ready, Fun facts below – source Primerica Q2 survey Middle-Income:
- 76% cutting back on non-essential purchases
- 36% using their credit card more often
- 71% say income falls short of cost of living
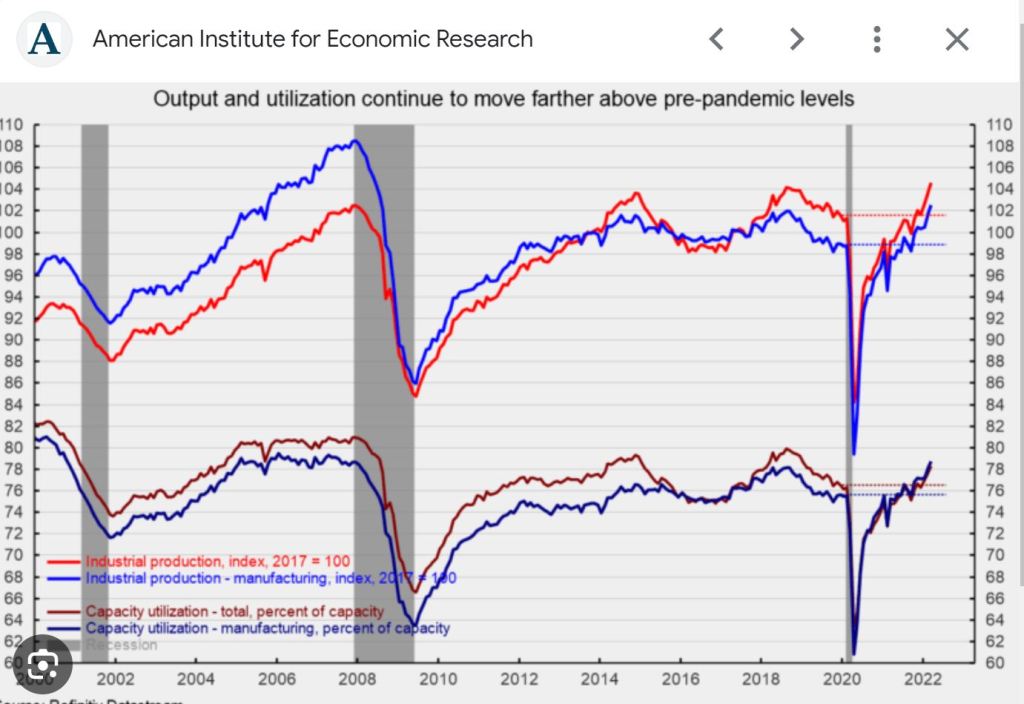
Industrial Production and Capacity Utilization
Think 100% is a factory working 24 hours a day. Currently we are at 78.9% slight drop from last month. This decline directly correlates with the buying activity of consumers.
Below you can see the 2008 Global financial crises and the 2020 pandemic affect on capacity usage.
Happy Tuesday, and always feel free to reach out.
-
If You’re constantly living in the future- you’re not enjoying the present.
The Powerball jackpot is over $900M and yes I bought a ticket this morning. But it begs the question; Dreams are fun but reality is real.
I have met and talked to many buyers and sellers who voice the same sentiment. “We are just waiting for the rates to go down” and “I heard home prices might drop next year”.
Redfin released their housing report for June, showing what we already know, housing supply remains very tight. Active listings are down 15% Y/Y and equally as important New listings are down 31%.
More inventory is not coming online and this is keeping home values up.
-
Inflation dropping from 9.1% to 3.0% in 12 months. But…..
The Feds, specifically Chris Waller, a voting member, wants to hike two more times this year.
I get it and understand the logic, the challenge is how is it going to affect the rest of us. A sprinter is told to Run Through the Tape. The question is are we past the tape or just have it in our sights.
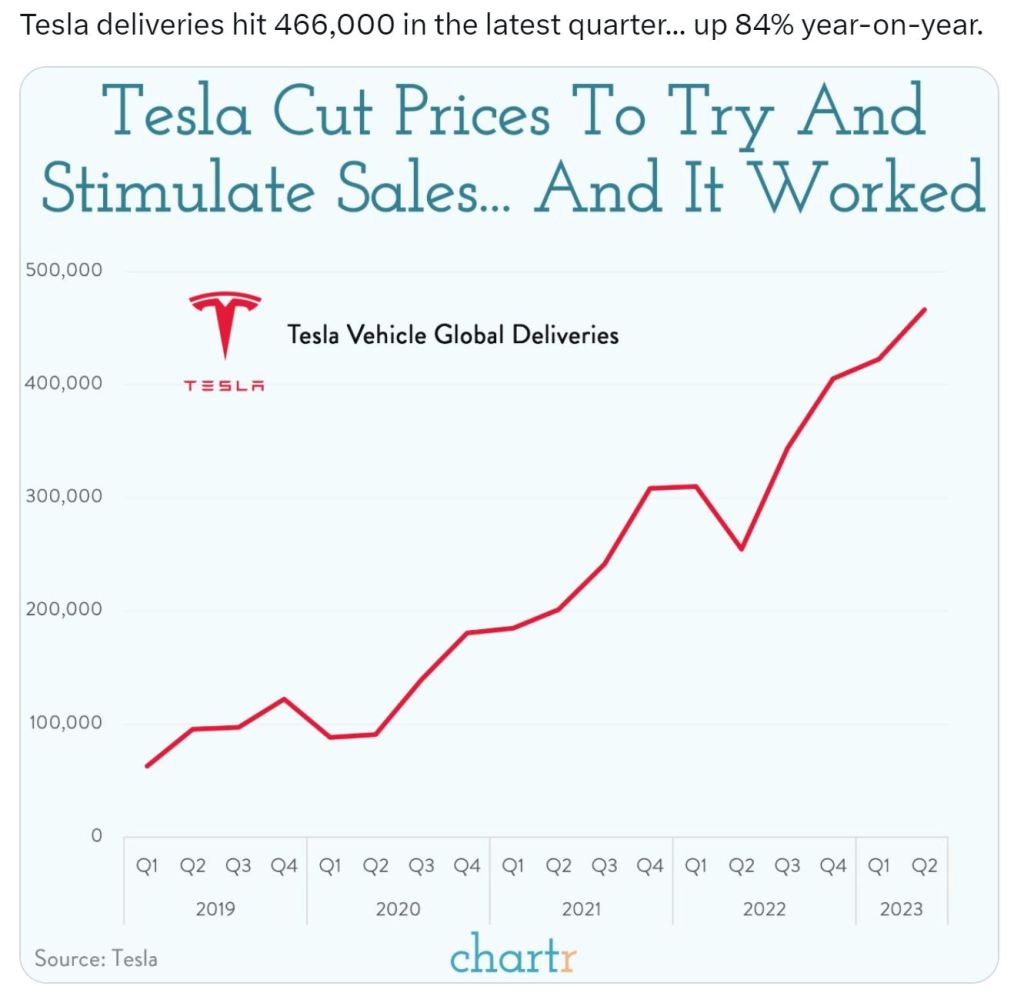
Tesla has been in the news lately due to used car prices dropping. Part of the reason is below. If you can buy a new Tesla for the same price as a used one, why buy a used Tesla.
-
Its getting Cold outside and its July…
Stocks and Mortgage Bonds are both in rally mode after a COOLER than expected PPI report.
The May Producer Price Index (PPI) report showed that overall producer inflation increased by 0.1% in June, which was even lower than the 0.2% expected drop.
There is an 80% chance after the July expected .25 hike the FEDs will not hike again for the rest of the year.
This is very good news for rates as we are starting to see the early June and mid May rates on a national average coming back into the 6’s comfortably.
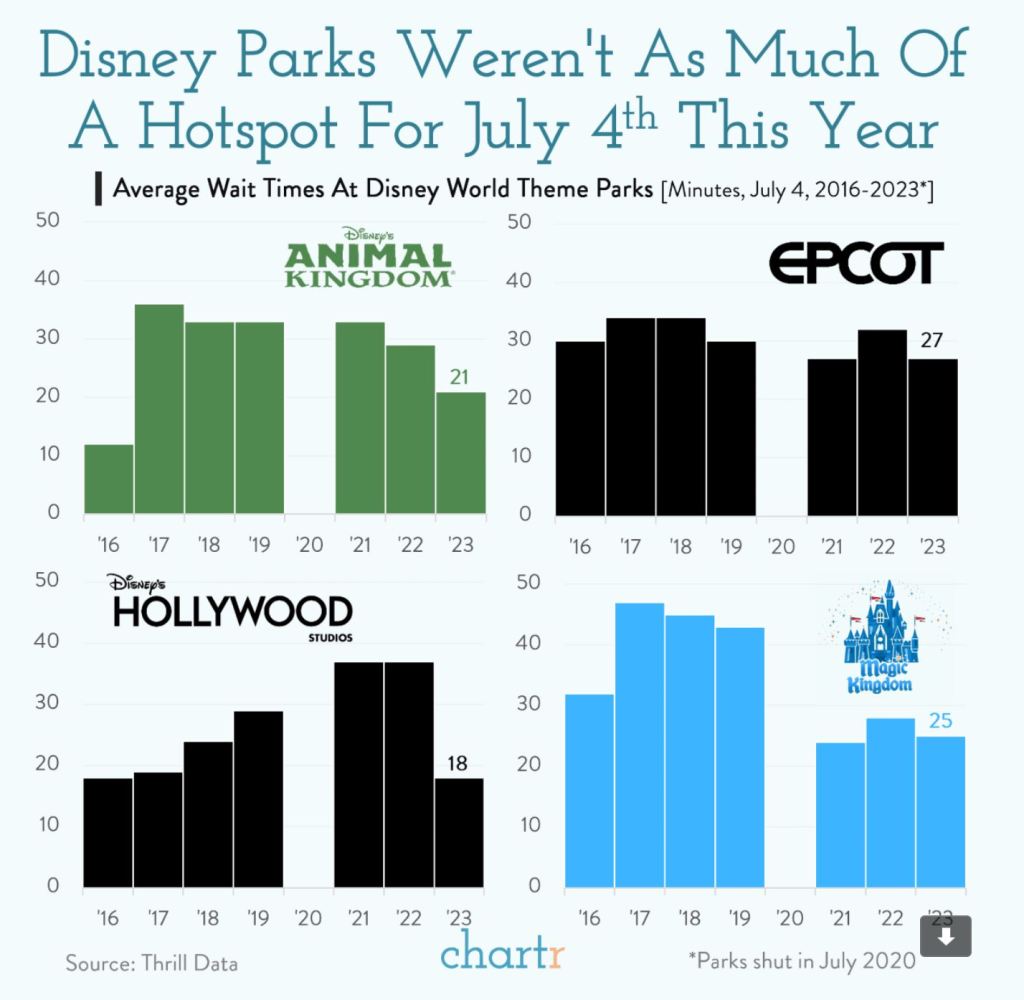
A fun look at Parks and attendance.
-
What goes Up has come down for the past 12 months
June CPI Consumer Price Index has dropped for the past 12 months.
Inflation increased by 0.2% lower than the estimate of 0.3%. Y/Y inflation declined from 4% to 3%. the expected drop was 3.1%. All aspects of the Core inflation, Shelter, and Used Cars also dropped below expectations.
What this means for us is lower rates. Mortgage Bonds have responded in a rate favorable direction.
I couldn’t find a good graph of the Bond Yield movement so opted for this one.
Enjoy the rest of your week.
-
Home Prices Continue to rise. Office Space and allot of it.
CoreLogic Reported home prices rose 0.9% in May and 1.2% in April. Home values are now up 1.4% Y/Y.
CoreLogic expects a 1% gain in June with a 4.5% gain over the next 12 months. We may be on a 10% appreciation pace.
With used vehicle price index showing used car prices falling 4.2% in June and over 10.3% Y/Y, the expectation is a Consumer Price Index (CPI) from 4% to 3.0%.
Crossing our fingers as this could be a positive reaction in the Bond market.
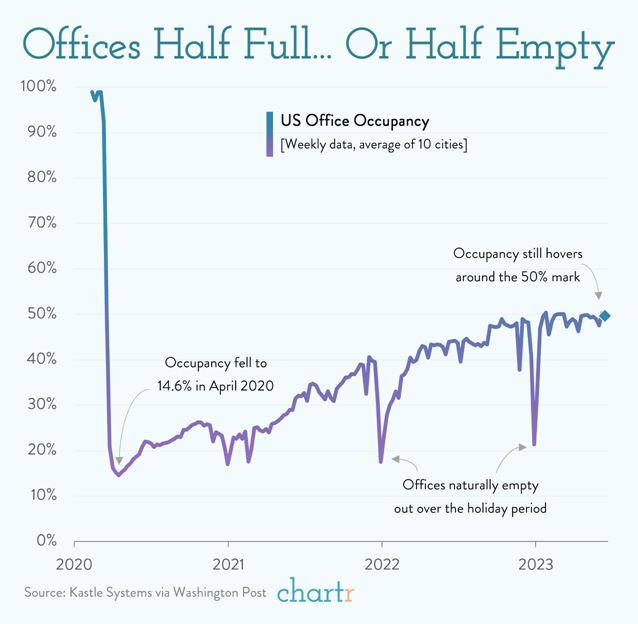
Office Space. This graph says a 1,000 words and will leave you with that.
-
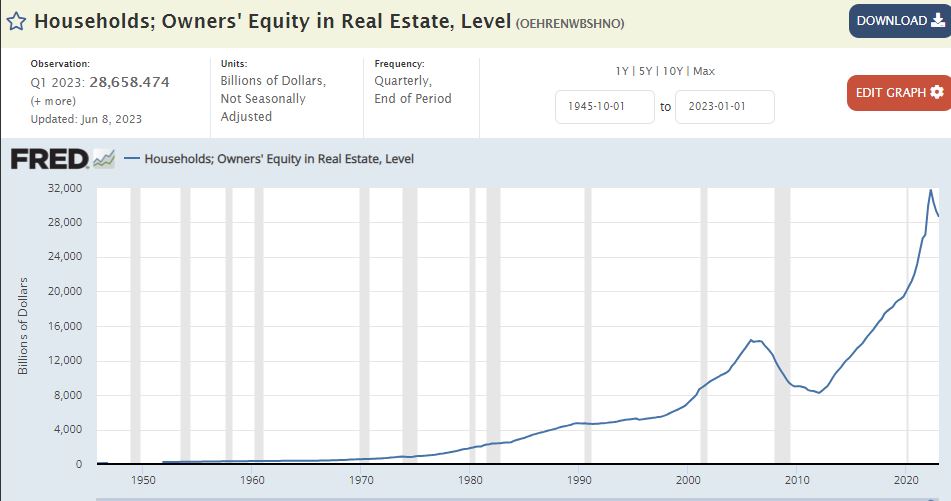
Home Equity Q1 Report showed home equity dropped 0.7%. What’s going on?
I have seen in the media this morning stating home equity has dropped with the assumption that home values have also dropped. This is not the case.
What is actually going on is a large amount of people are doing cash out refinances or Home Equity Lines of Credit.
We are looking for Wednesdays report on inflation Wednesday. But will it be enough for the FEDs from hiking another 25bp on July 26th.
Rates have been hit hard the last two weeks. On Monday, July 10, 2023, the current average interest rate for a 30-year fixed mortgage is 7.38%, up 23 basis points from a week ago.
We are still projecting lower rates this summer but its been a stubborn ride this year.
-
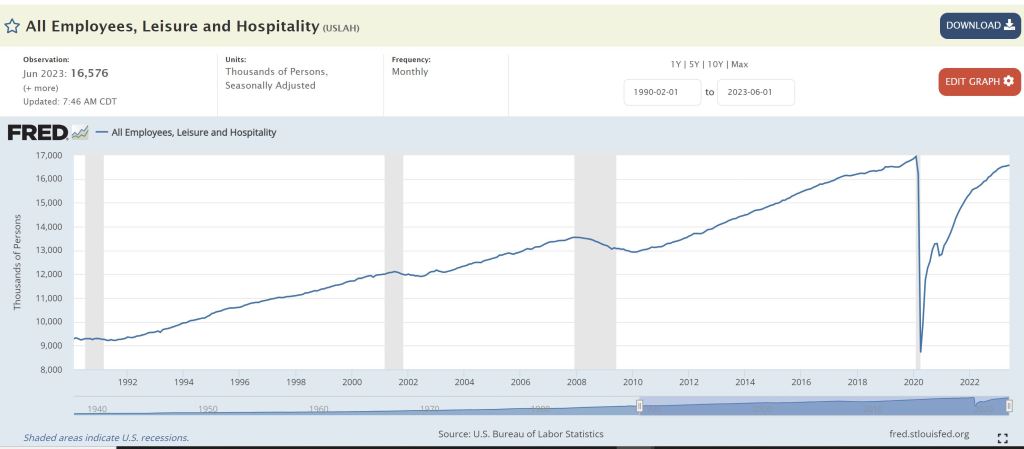
Leisure and Hospitality is the Canary in the coalmine
The Bureau of Labor and Statistics (BLS) reported there were 209,000 jobs created in June which was weaker than the expectations of 340,000.
But… Leisure and Hospitality only added 21,000 jobs. If we look back to my previous posts it’s helps clarify why this is an important trend. Think back last year when this sector was adding jobs let and right and not slowing down after the pandemic layoffs. We are now seeing a dramatic slowdown.
Have a great weekend and always here to help.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

