-
“The economy is weaker than it appears.” – Kaplan, former Dallas Fed Pres.
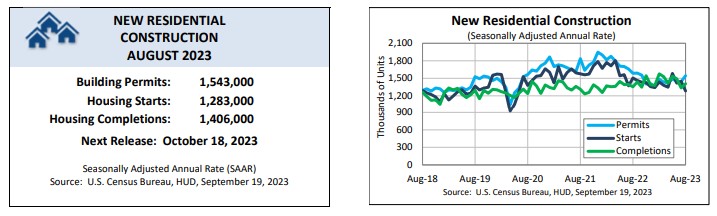
Supply is not keeping up with demand. Housing Starts fell by 11% in August. This means we are 15% down from last year. The decline was mainly in Multi-Family homes.
Single family starts fell 4% last month but up 2% Year over Year. Housing permits, which foreshadow the future supply, were up 7%, but down 3% from last year.
To put this into context. The Demand for new construction housing is 2M+ units. Actual production is 1.4M units. This is one of the reasons housing prices continue to rise.
Not to be too depressing but here are a bit more data points.
Current Sales fell 6%, Future Expectations fell 6 points and below 50%. Buyer Traffic fell 5 points.
Rising mortgage rates, lack of workers and buildable lots, and ongoing shortages of distribution transformers that connect the home to the grid.
To defend the Builders, they are the ones taking the risk. Spend all that money on land, materials and labor in hopes that one year or two years later you made the right decision with no control over inflation or interest rates.
I promise I will be happier tomorrow.
-
Fed Speak, You tell me.
Here are a few quotes from different Fed Presidents across the Country.
“Acknowledged shelter lags and said inflation would be at 2.5% today.”
“Said Fed policy is appropriately restrictive”
“Can be patient and hold rates steady, let actions taken do their work”
“Not how high to take the Fed Fund Rate, but how long”
“If tighter financial conditions are a headwind to the economy, the path of Fed Funds Rate may be lower.”
I will predict today that the Feds will not raise the Fund Rate 25bp. Some top economists disagree but let’s see. Feds meet later this week.
-
Signs signs everywhere a sign. – 5 Man Electric band
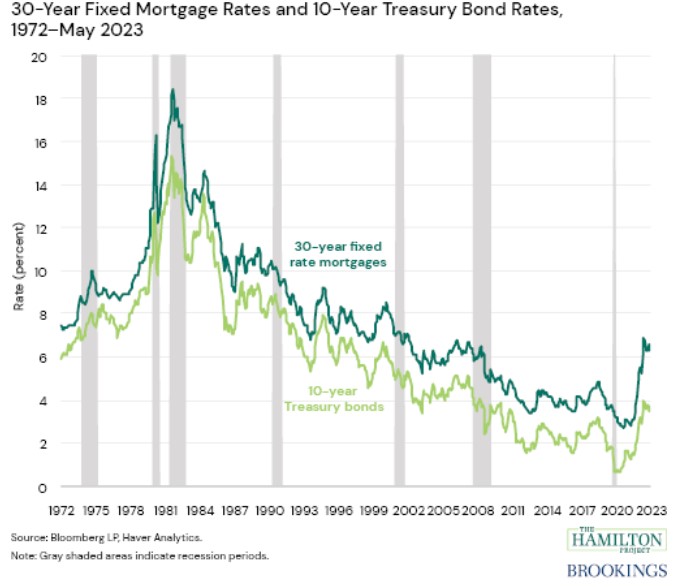
Did you know that the Fed Funds rate at 5.5% is above the 10-year Treasury yield.
Here’s what is interesting. It’s only happened 4 times in history, including right now. Though they don’t follow each other it does show once the Feds start lowering the Fed rate, the Mortgage rates will follow.
Zillow Home Price Index
Home Values rose 0.2% now 4.5% since the beginning of the year. Looking at a 7% full year appreciation.
Have a great weekend and enjoy the song.

-
Only the Past can’t be Changed
NY Fed President John Williams commented on inflation and the real estimates of inflation being closer to 2.5%.
This is the first sign that the Feds are not looking back but forward and projecting the data correctly in our opinion.
An example is retail sales. It rose 0.6% in August, hotter than the 0.2% expected. But when you strip out gasoline, sales only rose by 0.2%.
The idea is to look closely at the numbers and not have a knee jerk reaction.
There are 17% more homes on the market compared to January. This is good news.

-
It’s baked in. Let’s crunch the numbers on Inflation.
There is a feeding frenzy in the news. Inflation is up, oil prices keep climbing….The world is ending… Let’s break down the numbers and take a deep breath.
Yes the CPI August Consumer Price Index which measures overall inflation increased 0.6%, and was in line with expectations. The Core CPI decreased from 4.7% to 4.3% again as expected.
Energy prices rose by 7.3% Y/Y, and was down from 7.7%.
Rents rose 0.5% last month and up 7.8% Y/Y but down from 8%.
Lodging away from home also fell 3%.
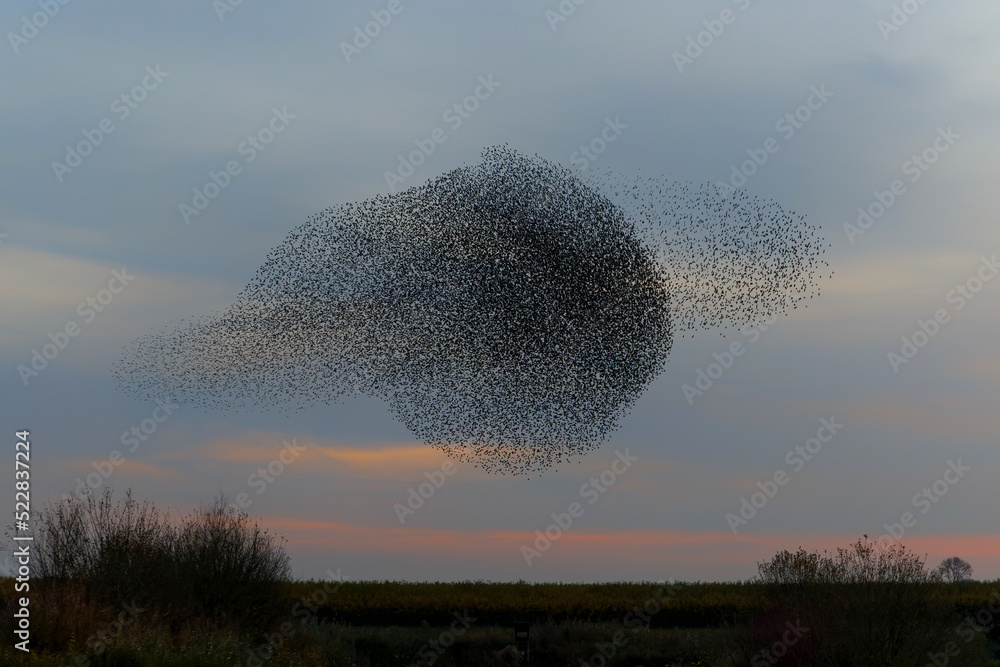
A wealth of data flows in, yet many news outlets seem reluctant to delve deeper into the true essence and beauty of the data. It’s akin to observing a single bird soaring through the sky, swiftly changing course from left to right. Only when you step back and broaden your perspective do you witness the mesmerizing spectacle of a flock of birds engaged in a graceful ballet.
We are headed in the right direction. The FEDs will most likely pause on the rate hikes in September given the true long term data that has been coming in this year.
-
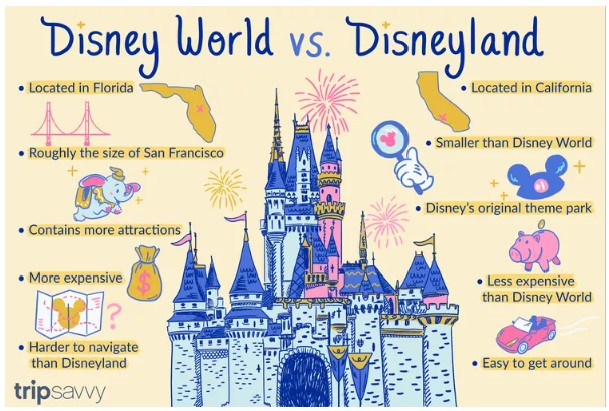
Disneyland Opened its gates 68 years ago.
I’m just trying to find my happy place.
Wednesday the CPI Consumer Price Index and Thursday the PPI Producer Price Index for Retail Sales comes out. These are two important gauges of inflation for the FEDs.
Remember the FEDs are data driven.
Definition of CPI: It is the Measure of the overall change in consumer prices based on a representative Basket of goods and services over time.
Forecast for tomorrows CPI is 3.6% from 3.3% but the Core CPI estimate is 4.3%. But it’s down 0.2% for July from 0.6%.
Definition of Core CPI: Is the change in prices of goods and services, except for those from the food and energy sectors.
In a nutshell, Inflation is not going away. The FEDs may say, one more rate hike then we are done.
-
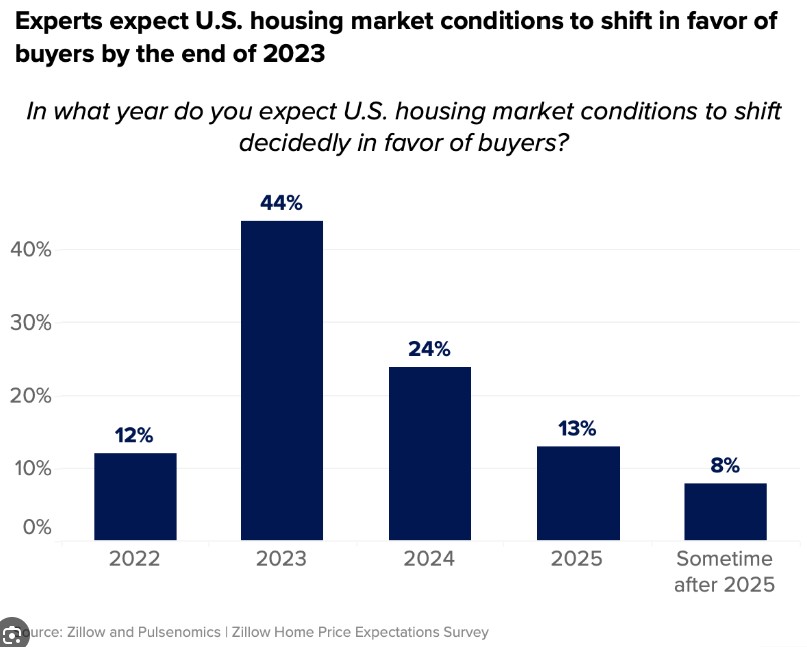
Price Cut concerns, are home values going down?
I was at the grocery store yesterday and I noticed quite a number of sale prices on items I actually wanted and needed. I have enough laundry detergent to last two lifetimes…
This struck me as a consumer for the first time in two years that prices are dropping for actual items we want and need. It’s anecdotal but sure seemed real to me.
In the housing market we are seeing price reductions rising year over year. But here’s the rub.
2018/2019: Home values up even with price reductions climbing.
2020: Home prices rose, reductions still strong.
2021: Home prices up 19% and price reductions rose sharply.
2022: Home prices skyrocketed as did price reductions.
Today: Home values are still rising as are price reductions.
Having been in the industry for over 19 years, the glaring omission in the data is inventory and greed. High demand, low inventory. Low inventory sellers get greedy and overprice their homes.
-
Feds Thinking Hold, Recession? What Recession.
NY Fed Pres John Williams said monetary policy is in a good place. He also said recession talks have now vanished.
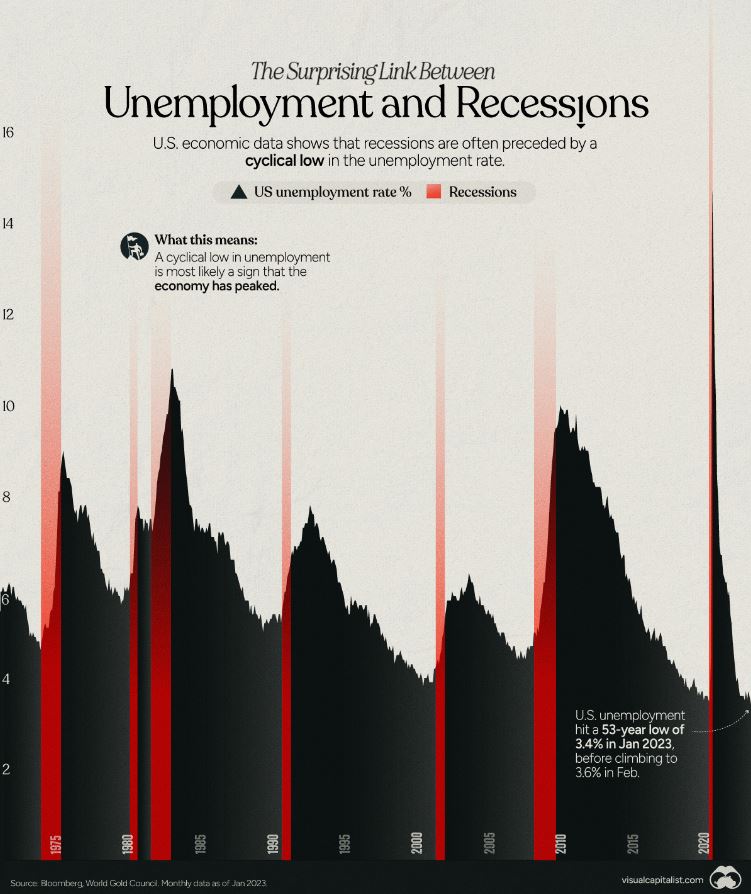
Here is the interesting part; how can there be a recession if the unemployment rate is so low. and we never get recessions when the unemployment rate is higher.
It’s about the differential. When the unemployment bottoms and then moves higher, that is when we see a recession with 100% accuracy. Unemployment then moves higher during the recession. The April unemployment rate was 3.4% now it’s 3.8%.
Consider what we are up against this fall. Higher spending on credit cards. Those cards have higher rates, the delinquencies are higher, student loan payments are coming, savings rates are declining, and almost all of the excess from the stimulus is spent out of the system.
The silver lining is if we were to see a recession, inflation and mortgage rates would decline as they always do.
-
Rates
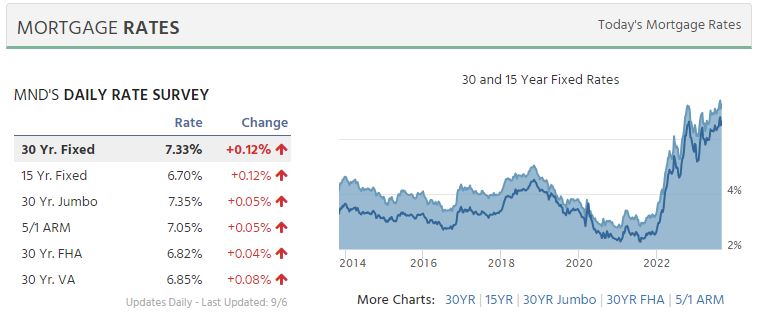
It’s the question that comes up daily. When are the rates going to drop? Should I buy now while the home values are going up or just wait for the rates to drop.
At this point it’s a crystal ball. We just don’t know. Technically we see the indicators but it’s just not happening yet.
The Feds are Data Dependent. If they see less growth and inflation, the Fed will set a more friendly policy stance and rates will move lower.
Remember what the Feds are doing; they are making it less attractive to borrow money to expand businesses and do other purchases that stimulate the already hot economy.
-
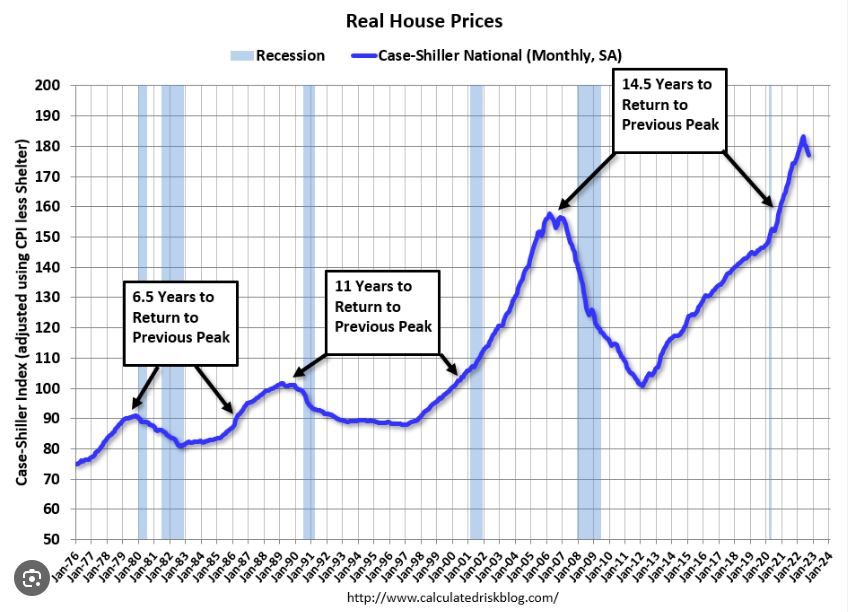
Home Prices rose 1.5% in July, 4.4% this year.
I am now speaking to all that are waiting for the rates to drop. Stop waiting to purchase. Home values continue to rise and offset any gains by waiting for the rates to drop.
When rates drop your competition will be drastically higher as more buyers get into the market.
Feds are talking and I see the doves in the air. Let’s look for a pause in rate hikes this month.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

