-
When you pray for rain you got to deal with the mud.
The economic data is messy and counterintuitive. Q3 GDP shows US the grew at a 4.9% pace up from estimates of 4.3%. More inventory available, more consumer and government spending. Q4 projections show things slowing and even a negative number.
The Bank of Canada left rates unchanged, citing the global economy slowing. The European Central Bank also paused after ten straight hikes. They said they would use their emergency bond buying powers if bond yields go unruly.
Feds meet next week and we expect a pause.
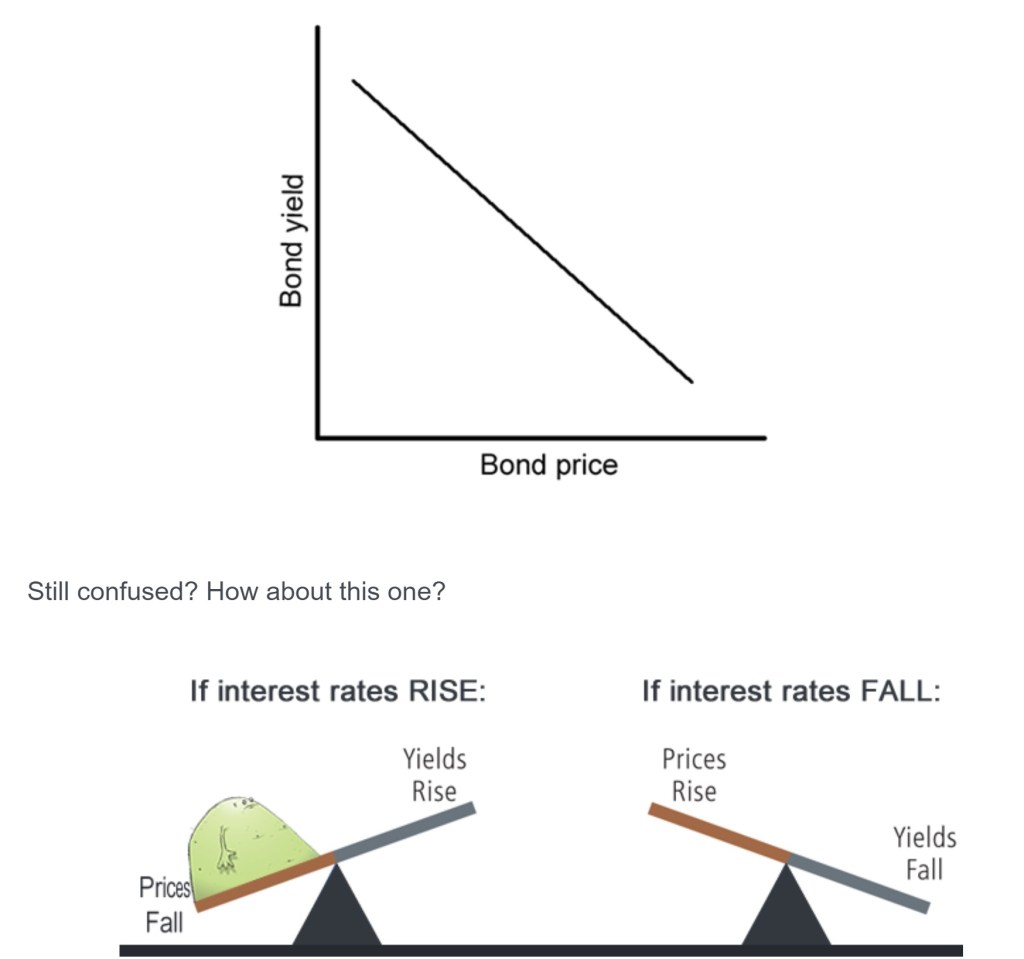
The appetite for Bonds is perplexing. It’s the flight to safety/security. But that is not happening. the Bond Yields continue to go up, Bond rates continue to drop. Remember the correlation between Bond Yields and Interest rates. With the lack of Bond purchasing, the mortgage rates keep going up as do the Yields.
Initial jobless claims rose 10,000 to 210,000. Continuing claims also rose 63,000 to 1.79M.
Pending Home Sales rose 1.1% projection was a 2% fall. Sales are down 11% Year/Year. And at the heels of yesterday’s blog, showing New Home Sales rose 12%.
Delinquencies are down to their lowest levels in almost 25 years. Foreclosures are almost at their lowest mark in 25 years at 0.3%.
-
New Home sales up 12.3% last month up 34% Y/Y.
60% of new homes sold were either not started or under construction. The builders are selling air.
Anecdotally I have spoken to many Title company officers and they are stating the same thing. If home prices are that high and the builder can incentivize the buyer with rate buydowns and upgrades, why wouldn’t you buy a brand new home.
I have done a few presentations this week and one analogy kept hitting me. We in our industry including Agents, home buyers and sellers, have been treading water for the last two years just to stay afloat. What we miss when we are so focused on breathing is we forget to straighten our legs to see if there is sand under our feet.
I feel sand and I want you to straighten your legs, you might be surprised.
-
The Feds have won the battle of the American Consumer – B of A CEO Brian Moynihan
Its not just Brian stating the obvious but other well respected players suggesting the economy is slowing faster than the data suggests.
Not to bring up the pandemic, but… I remember telling my wife that some day and sooner than later we will wake up one morning and this will all be behind us. Our intense focus sometimes blinds us to the broader picture.
In retrospect, my future self might view this moment as the turning point when society collectively decided “enough is enough.”
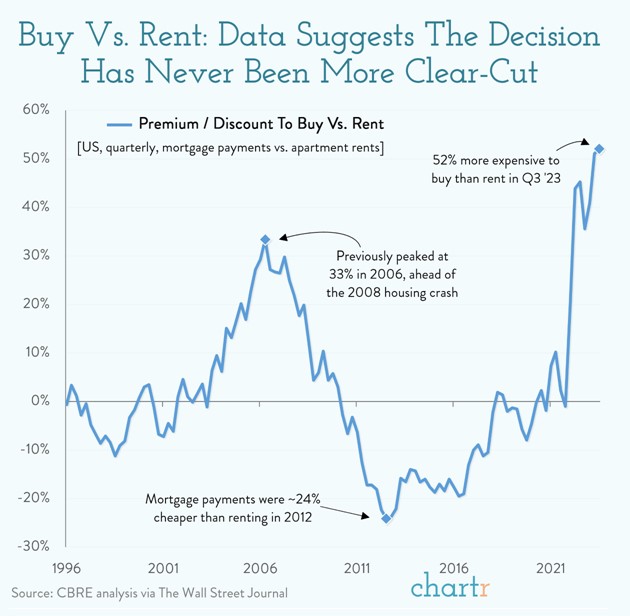
The dilemma of buying versus renting hits close to home for me, especially with my two daughters who have recently graduated from college. They wonder aloud, “When will we ever be able to afford a home?”
To the Real Estate Agents out there, this is a good time for your sellers to start thinking 2/1 buydown. Lets get borrowers in reasonable rates for what we anticipate will be lower rates in the next two years.
-
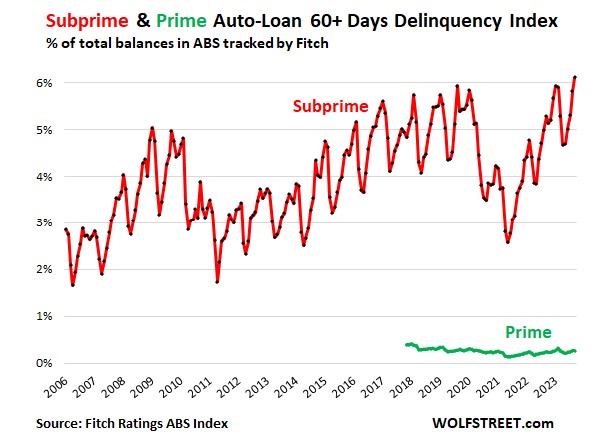
Delinquencies on Subprime Auto loan Borrowers rose to 6.11%, highest on record.
This is the Canary in the coal mine as the economy starts to slow. I saw this coming years ago and was a bit surprised it took this long. When you can get an auto loan with no proof of income, the lesson has just not been learned.
Housing inventory up 1.4% per Redfin report. Great news but seasonally expected. 40% of homes went under contract in September. Inventory is still at historic lows.
10-year yield touched 5% briefly this morning. The one good news is it becomes more attractive to Bond investors. This will inevitably lower yields and rates.
-
“Are we there yet? I feel like I’ve aged a hundred years in this car, and I haven’t even grown a single gray hair!”
Fed Chair Jerome Powell gave us some clues as to what the Feds are thinking. A bit of a hawkish tone. He is flexing his muscles but maybe just for show.
Other Fed Presidents are more optimistic of a rate pause and cut mid to end of 2024.
Zillow has adjusted their home price appreciation forecasts down from 4.3% to 3.3% for 2023. Over the next 12 months the revision has been adjusted down from 4.9% to 2.1%.
At this point home values are hitting rates square in the face. The appetite for an 8% mortgage is too much to bear.
-
The First Time Since…….
The 30-year fixed mortgage rate just hit 8%, the highest Since 2000.
Highest bond Yields Since 2006.
Mortgage Applications Plummet to lows not seen Since 1996.
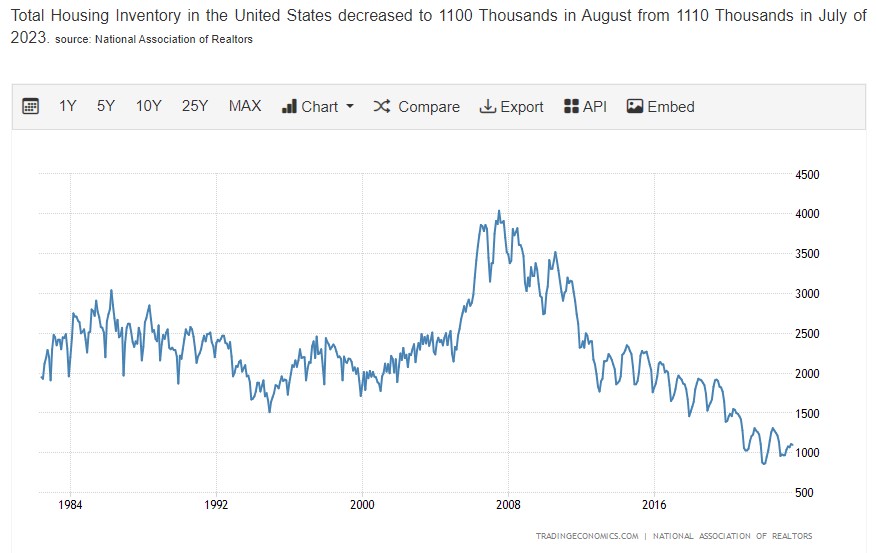
Housing inventory 2023 lowest level Since before 1984.
Unemployment rate in 2023 lower than its been Since 1969.
So what do I think? I don’t. I had to stop thinking, my head hurts too much.

-
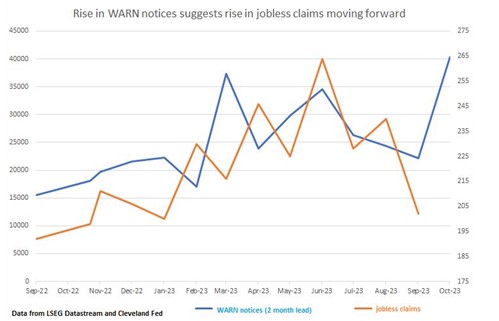
What is a WARN Notification? Let me tell you why it’s important.
There is a plethora of data to sift through to help focus the lens on the future. I feel like calling my psychic advisor but before I do that, let’s take a look at what a WARN notification is and the graph below.
WARN stands for Worker Adjustment and Retaining Notification Act. This Act protects workers, families and communities’ by requiring companies with over 100 employees to provide at least 60 days notice of a plant closing or mass layoff affecting 50 or more employees.
It’s a kind of 60 day time machine.
Housing Starts and Permits
Supply is not not keeping up with demand even if supply has increased. Single -Family Permits rose 2% and up 12% year over year. But Housing starts are down 7%.
It sounds like I’m talking from both sides of my mouth. You have housing starts rising, Building permits (future supply) falling 4%. Single family and multi family projects and the permitting process standing at a 3-year low.
It’s all over the place. If you want good news you’ll find it. If you are doom and gloom, you will find that data as well. Take a deep breath we will all get though this.
-
Why this Housing Cycle is Nothing like 2008.
In the news and always on social media is the drumbeat of the highly anticipated housing crash. This is False and the numbers bear it out.
Unemployment rate at historic lows, no Subprime loans, low inventory, Mortgage delinquencies and minimal homes in Foreclosure.
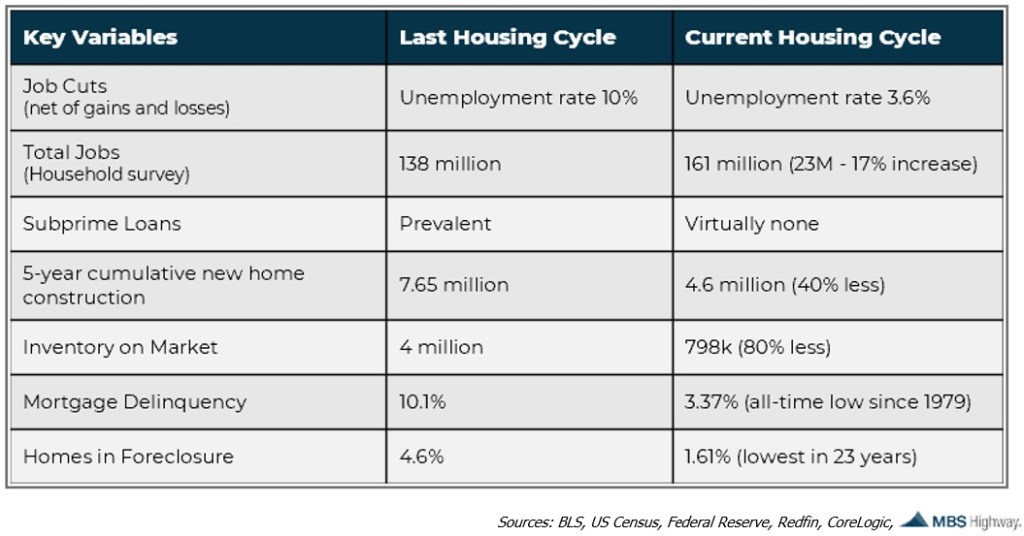
Remember in 2008 when the housing market crashed, the borrowers still hanging on to their homes were looking at an Adjustable Rate Mortgage ready to mature.
The second wave of foreclosures were just around the corner.
Today we have none of that. Home Owners are highly motivated to keep their homes to preserve the low fixed rate mortgage. Home Values keep going up along with the interest rates.
There is a diminishing likelihood of a recession as the indicators are begrudgingly eking out data telling us so. The problem is its taking far longer than anyone expected.
Have a great rest of your week.
-
Financial Flight to Safety – understanding the Bond Market
Mortgage rates are driven by the Mortgage Backed Securities i.e. Bonds. Uncertainty in many forms causes a flight to financial safety.
The bond market is confusing especially when you hear bond yield and bond price used interchangeably.
During the financial crisis in 2008, the US Government was purchasing bonds at a breakneck pace. This caused the bond prices to go up and the interest rates to drop.
When the Federal Reserve buys bonds, bond prices go up, which in turn reduces interest rates. Open market purchases increase the money supply, which makes money less valuable and reduces the interest rate in the money market.
We have seen some rate improvement this morning as expected.
-
Ok Now What……
BLS the Bureau of Labor and Statistics reported 336,000 jobs created in September. This was far higher than the estimated 170,000.
The bond market reacted exactly as expected. Higher Yields, higher interest rates this morning.
There are two Surveys within the jobs report.
Business Survey – is where the headline job creation numbers come from and includes a lot of modeling and estimations.
Housing Survey is where the unemployment rate comes from and is derived from calling households to see if they are employed. This has its own job creation component, and tells a completely different story, only showing 89,000 job creations.
This is why the unemployment rate stayed at 3.8% from the expected 3.7%.
Trying to understand all of this is an apt comparison attempting to grasp a handful of Jell-O, which incessantly shifts and eludes your grip with the slightest movement.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

