-
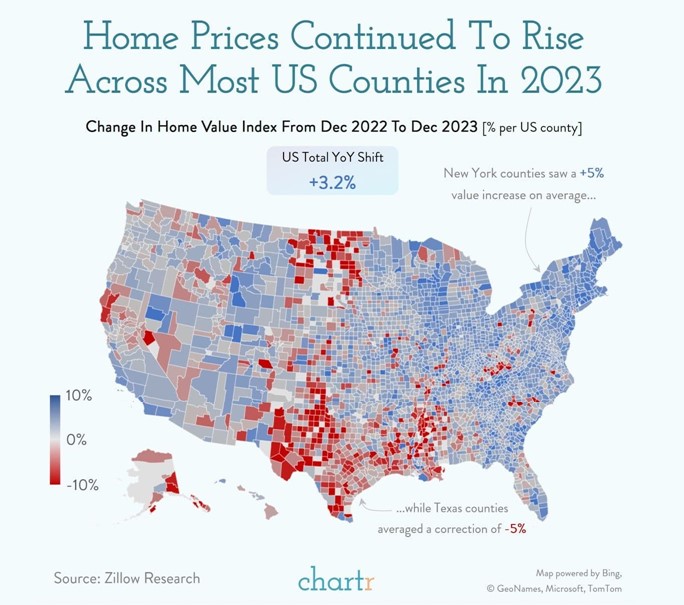
Cost of Waiting. Home Values up 5.5% Y/Y
Home values continue their climb, up 5.5% year over year. Black Knight reported the average homeowner has over $300k in equity. Most mortgage holders loan to value is under 46%.
The equity position of home owners is incredibly strong. Refinances, especially debt consolidation are on the rise. 1.7M people could benefit because they purchased it last fall at higher rates. When rates drop to 6% there will be over 3.8M who would benefit from refinancing.
The forecast for home appreciation is 2.8% per CoreLogic and Black Knight Appreciation Reports.
I have a YouTube Video explaining the Cost of Waiting to purchase a home. Enjoy and have a great rest of your week.
-
Thank you Powell, NOT. Debbie Downer just walked into the room.
Fed Chair Jerome Powell spoke on 60 minutes Sunday and basically took the air out of the room. There is a phrase in the industry called Analysis Paralysis.
The Feds are so afraid to make a decision, they end up deciding by not deciding.
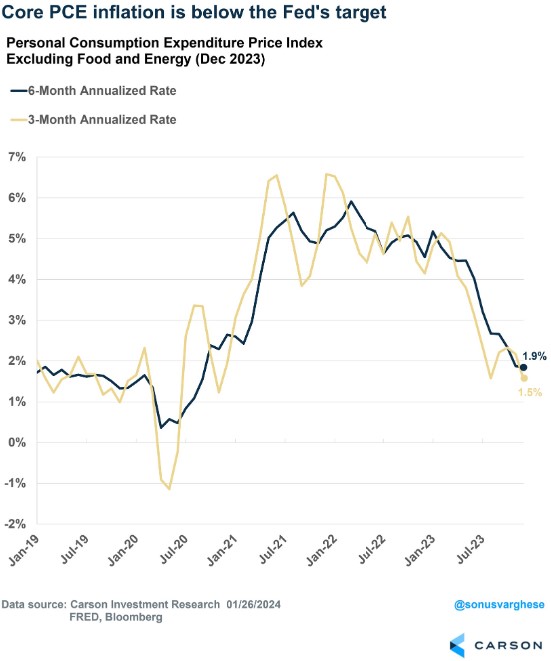
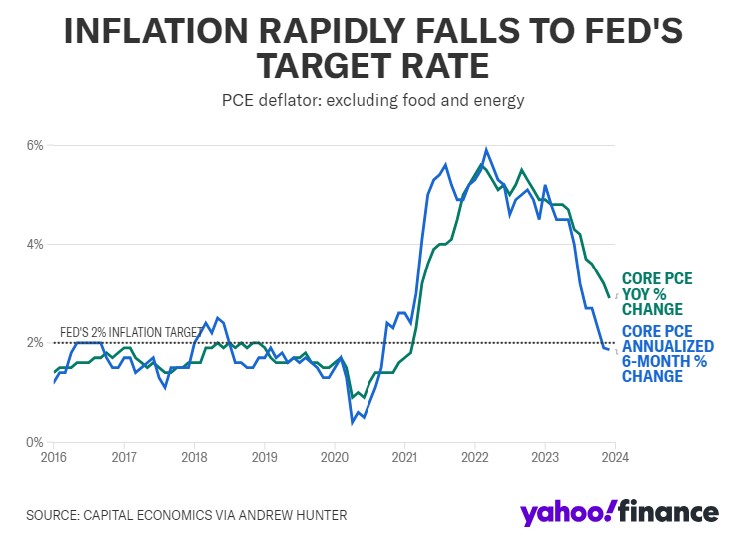
Let’s put this into context. The 6-month annualized rate of core PCE inflation is at 1.85% and the 8-month annualized rate is at 2.08%. Remember the target is 2.00% annual inflation.
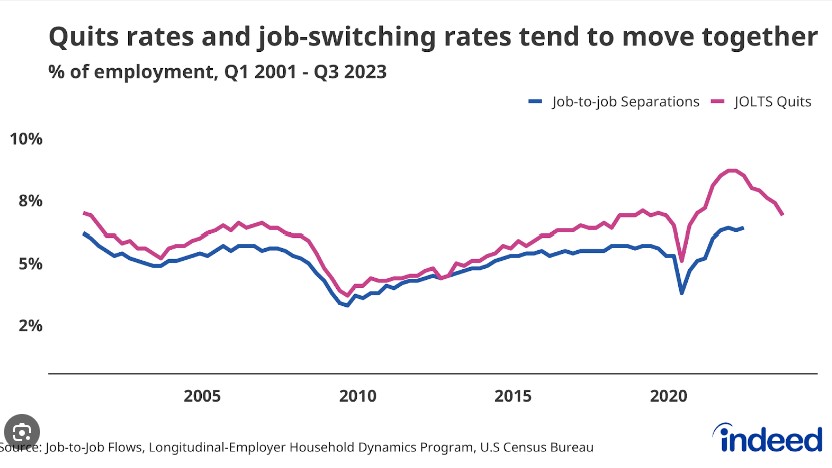
Oil prices, rents-shelter costs and other components of the PCE report continue to drop. The Jobs market is also not quite what it seems. Employees are staying put as it’s harder to find a job once they quit.
-
Double the pleasure or Double the Trouble?
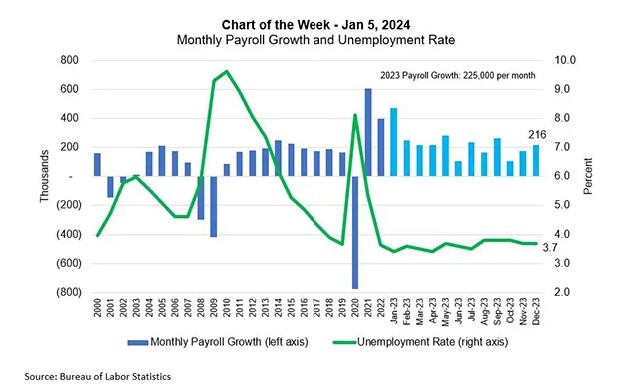
The Bureau of Labor and Statistics (BLS) reported 353,000 Jobs created in January, which is double the expectation.
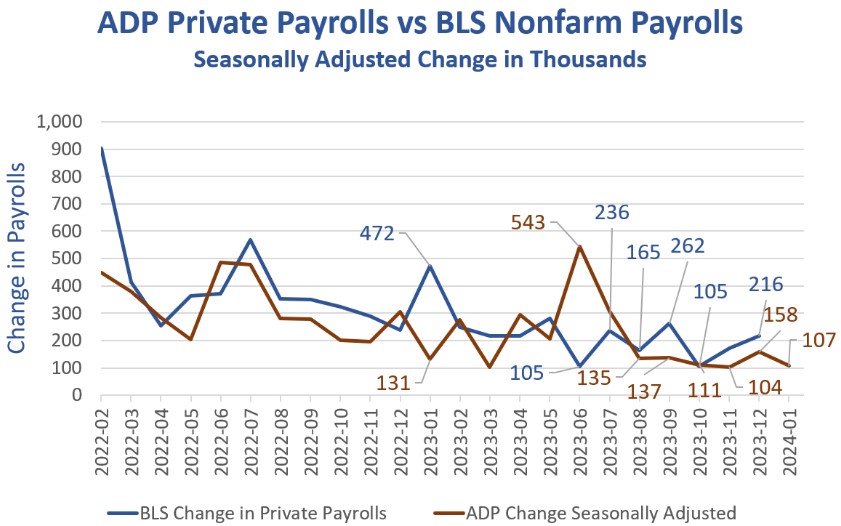
What is really odd is the contract to the ADP report that only showed 107,000 jobs created.
Here is another contrast between the two reports. Average hourly earnings, which measures wage pressure on inflation, rose 0.6%. This is double the expectation. ADP showed significant declines. ADP samples 10M actual employees.
Average weekly hours worked declined from 34.3 to 34.1. The lowest level since 2010 (minus the pandemic). This is why hourly earnings rose. Working less hours but producing the same result. This translates to 30 minute less per week compared to January 2023. This is a way for businesses to cut costs.
However, amidst these contrasting data points, a challenge persists with the potential manipulation or omission of crucial data elements.. The BLS report has two components, the Business Survey and the Household Survey. The Business Survey is the headline report. The Household Survey is where the unemployment rate comes from.
The Household Survey was much much weaker than the headline 353,000 jobs created.
I’m rambling here but bear with me. All this data, regardless of how it’s presented, paints the picture the Feds want. Weaker economy and inflation. This translates to the Feds lowering their rate sooner than later and the Mortgage rates will follow.
-
All Eyes and Ears on Powell. Whatcha gonna do???
Jerome Powell Chair of the Federal Reserve is EF Hutton (dating myself on that reference). When Powell speaks everyone listens.
Acknowledge GDP better than expected.
Growth has slowed from Q3.
Better balance of employment and inflation goals
Less likely Confidence by March 20th to cut rates.
Mum on the balance sheet ie buying Securities/bonds and stop selling them.
Unemployment rate 4.2%, benefits for the first time rose 9,000 to 224,000. This is Holiday adjusted. Continuing Claims rose 70,000 to 1.898M. A big rise and a sign that once you are laid off, its harder to find another job.
I don’t see exactly what the Feds are waiting for. We see what is happening with Rents dropping, the Used car industry on the ropes, Layoffs and more. My suggestion is for Powell to quit looking through the rear view mirror and drive the car.
-
Jobs Report Weaker, Bonds improve, rates keep dropping.
ADP Employment report showed 107,000 jobs created in January, but was weaker than the 150,000 expected.
Here is the breakdown
Goods-Services Added 30,000
Manufacturing Added 2,000
Construction Added 77,000 *155,000 last month
Hospitality Added 28,000
Annual Pay for Job Stayers increased 5.2% down from 5.4%. Job Changers increased 7.2% down from 8.0%. Still strong but moving down.
Going back 19 months, Stayers saw a 16.4% increase in pay, while job Changers was 7.8%. What the Math tells us is the difference between last year and this year’s stayers/changers is only 2%. It was over 7%. Employers are holding onto their employees and employees are more reluctant to change.
The Fed concludes their 2-day meeting today with a Press Conference at 2:00pm ET.
Rates continue to improve as we expect the Feds to pause on rate hikes as we look towards March for a possible rate cut.
-
Headlines say Layoffs but JOLTS report says otherwise. Home Values UP.
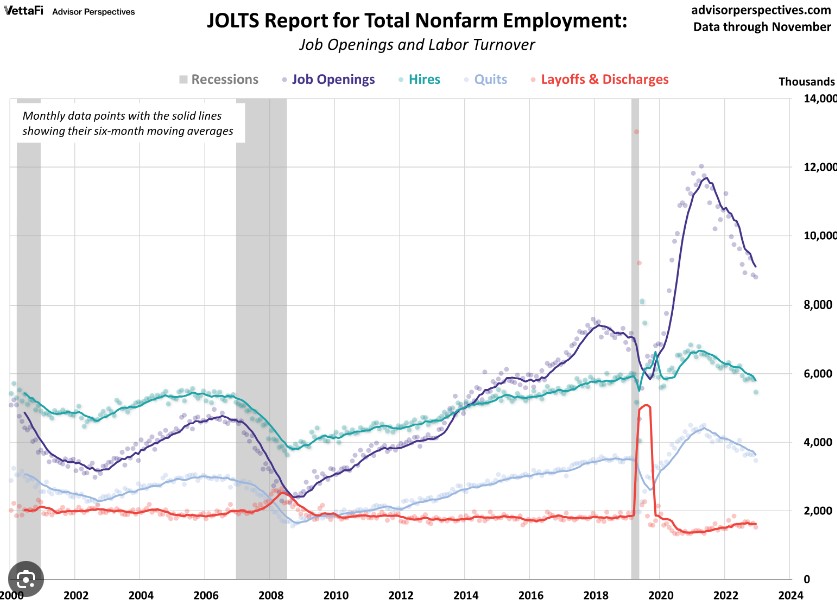
With high-profile companies like UPS announcing layoffs, it’s easy to feel like the sky is falling. However, the JOLTS report, which measures Job Openings and Labor Turnover, showed a rise in December from 8.925 million to 9.026 million.
Despite this, the number of quits remained at 2.2%, suggesting a decrease in hiring and less poaching of employees from competitors.
On another front, the Case Shiller Home Price Index saw a 0.2% increase in November, marking a 5.2% rise from the previous year.
In contrast, the Apartment List Rental Report experienced a 0.3% decline, down 1% year-over-year. This marks the sixth consecutive monthly drop and is significant as shelter costs are a key component of inflation.
The Bond Market reacted predictably, experiencing a slight hit to rates.
Tomorrow, the Bond Market will respond to the ADP Employment Report and the Federal Reserve’s statement at 2 pm EST.
-
Hindsight is 20/20 but you could have just kicked a field goal to tie the game.
Hindsight Bias is the illusion of predictability. We understand the world looking backwards but life moves forward.
The Fed will begin their 2-day meeting tomorrow. We will hear from Powell at 2:00pm ET on Wednesday.
The Feds will leave the Fed Funds Rate where it is but Powell has a tightrope to walk.
Core PCE is at 2.9% Y/Y, 6 month view 1.85% and an 8 month view is at just 2.08%. Remember the goal was 2% Inflation Y/Y.
We are seeing rents drop, the used car market shaking up and gas prices going down.
The BLS Jobs Report comes out this week as well as the ADP report. We are anticipating 135k to 170k new jobs created. Unemployment report due Friday and expectations are a rise from 3.7% to 3.8%.
Rates are holding steady but we have an important week ahead.
-
Inflation below 3% for the first time since March 2021
The Fed prefers the Personal Consumption Expenditures (PCE) as a gauge of inflation. The PCE index grew 2.6% year-over-year in December as expected.
The Core PCE, which excludes food and energy, grew 2.9% down from 3.2%.
During the December Fed press conference, Powell told Yahoo Finance’s Jennifer Schonberger that the Fed would want to be “reducing restriction on the economy” well before inflation hits 2%.
The Bond Market is holding tight and hanging onto the rate improvements so far this year.
-
Perfection of Imperfection – Wabi-sabi
The gap between good and perfect is immeasurable. In my interactions with numerous clients, agents, and trades, the recurring topic revolves around the anticipation of when mortgage rates and housing prices will decrease.It seems like we’re all yearning for a utopian world where gas prices are low, inflation is in check, unemployment is minimal, and so on. Surprisingly, we’re currently experiencing many of these favorable conditions.
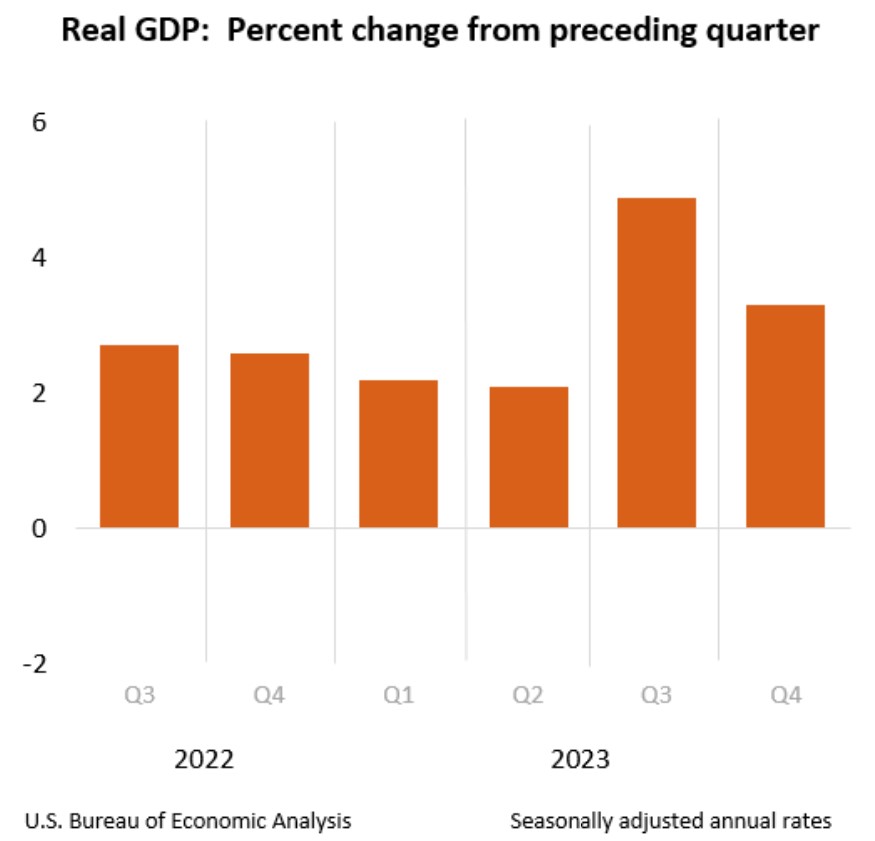
This morning’s revelation of a 3.3% rise in Q4 GDP, surpassing the estimated 2.0%, follows Q3’s impressive 4.9% growth. The economy appears remarkably robust, with Consumer Sentiment surpassing the 78% mark.
The challenge lies in being too fixated on perfection, potentially causing us to overlook the opportunities presented by the imperfect.
Get out there and start looking for a home, or list your home. Take advantage of the day/week/month/year.
-
CPI is 3.4%, PCE is 2.6% and Truflation is at 1.87% inflation.
Attempting to count a room full of cats or a pond teeming with fish is futile.Similarly, the Federal Reserve employs various indices, including the Consumer Price Index (CPI), Personal Expenditures (PCE), and Truflation. While CPI and PCE analyze around 80,000 data points, Truflation delves into a staggering 10 million data points.
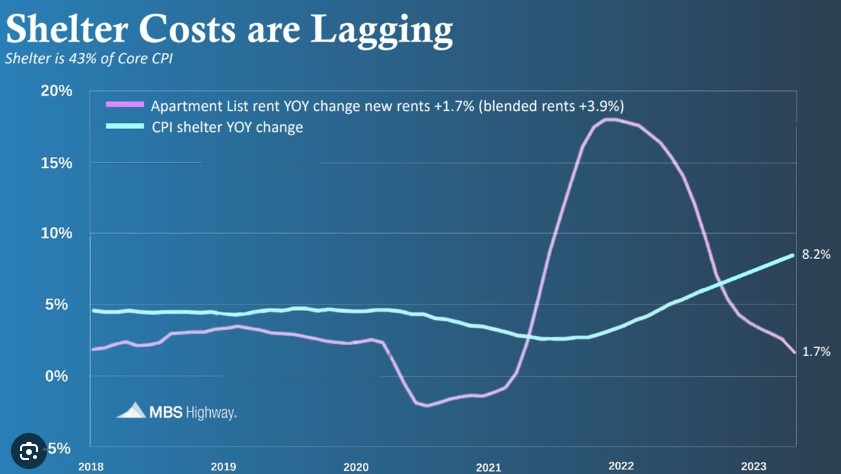
Within CPI and PCE, Shelter or Rents constitute the largest component. The disparity between CPI at 3.4% and PCE at 2.6% arises from CPI assigning twice the weight to Shelter costs compared to PCE.
Shelter costs are akin to looking through a rearview mirror, lagging in reporting their true numbers or decline. Anticipations suggest more accurate shelter data reporting by March/April.
Obtaining an accurate glimpse of the true costs of products and services proves nearly impossible. Keep an eye out for Personal Consumption Expenditures (PCE) numbers releasing on Friday, as we anticipate a positive impact on the Bond market and rates.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

