-
Goolsbee to the Rescue and the ADP Jobs report helps rates
There are cracks in the armor and the ADP Employment Report showed 150,000 jobs created last month, slightly weaker than estimates. This was true for May as well.
4th of July is tomorrow but remember the ADP report when the BLS Jobs Report comes out Friday.
The reason is BLS uses birth/death model for small businesses typically comes in hotter than the ADP report showing the only 5,000 of the 150,000 new jobs were for companies with 50 or fewer employees.
Jobless claims rose 4,000 to 238,000. These are the highest numbers since last year.
The Feds are starting to think rate cut as the data keeps streaming in. Dust off your W2s and paystubs and lets get you pre-qualified (soft credit pull).
Have a fantastic 4th of July.
-
What goes up, Must come down, unless you’re a Flat Earther.
But seriously, Gross Domestic Product – GDP estimates are released by the Atlanta Fed weekly. They just revised their Q2 estimate from 3% to 1.7%. May not seem that much, but its the equivalent $400 Billion adjustment down.
More signs of a slowing economy, with a lean towards rate cuts.
Job Openings and Labor Turnover Survey – JOLTS as I mentioned yesterday came in as expected at 8.1M. this is the lowest level of job openings since February 2021.
Home Values are still on the rise but holding steady at 4.9% increase year over year.

-
Short week but important
Quick update, Beth Hammack is replacing Loretta Mester as the new Cleveland Fed President and a voting member.
Why is this important you may ask? Its because she has real world experience at Goldman Sachs and managing director. The Fed needs this.
The JOLTS – Job Openings and Labor Turnover is coming out tomorrow. The numbers are expected to stay relatively stable. To note, Feb 2021 the number of openings was over 12M, Last report was 8M, tomorrows expected at 7.9M.
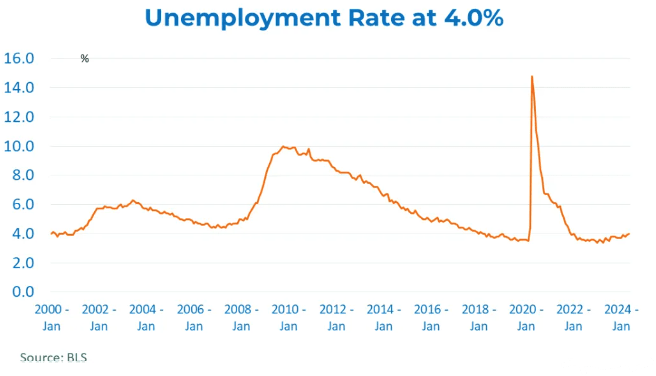
Wednesday ADP Employment report and Initial Jobless Claims will be released. Unemployment rate expected to stay at 4%.
Friday the BLS jobs report will be released.
-
Bostic, Daly, Goolsbee and Cook all aiming for Rate Cuts
Fed members are starting to join the ranks of rate cutters than rate holders.
Atlanta Fed President, Raphael Bostic spoke this morning and seems to be in favor of a cut sooner than later. He specifically called out the slower economic conditions and labor market.
Pending Home Sales fell 2.1% in May. We expected a gain of 1%. This is a clear response to higher rates.
Apartment List National Rent Report rose in June but still down 0.7% year over year.
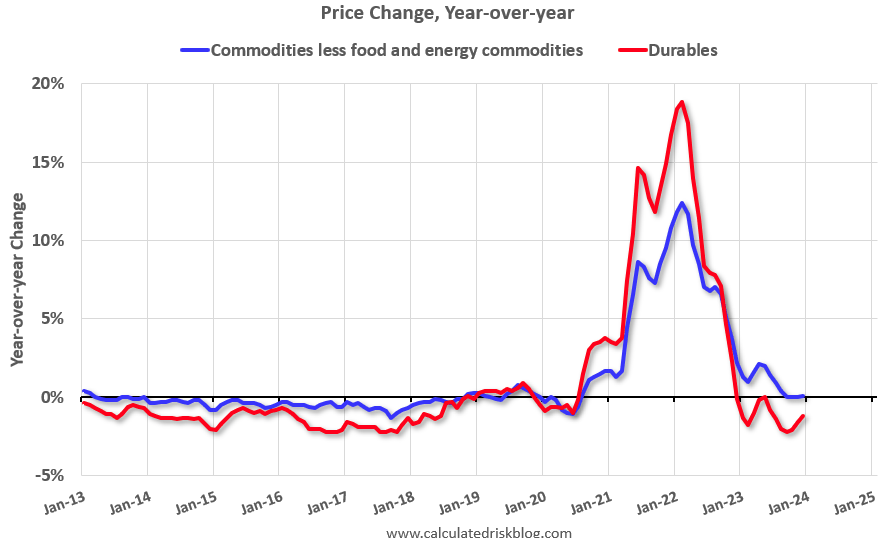
Durable Goods Orders rose in May, but Core Durable Goods fell 0.6%. Far softer than the expected 0.1%.
From my perspective, the Data is coming in strong in favor of rate cuts.
-
The FEDs are having a tough time agreeing to disagree agreeably
Bowman and Daly hold wildly opposing views on what to do with the Fed rate. Mary Daly isn’t solely focused on inflation but also on the rising unemployment rate. On the other hand, Bowman is against cutting rates this year and is so data-driven that she is actually discussing raising the Fed rate.
Let’s examine the impact high Fed rates have had on our economy. The objective was to slow down a hot market/economy to curb inflation, which sounds great and is historically accurate—except when the Fed rate remains high for an extended period.
Over time, higher costs for producers contribute to inflation. What costs me more will end up costing you more.
Home Prices hit all time high.
Case Shiller Home Price Index is the gold standard for appreciation. Prices rose 0.3% in April and up 6.3% year over year.
FHFA Housing Price Index which does not include Jumbo loans reported a 0.2% rise and a 6.3% year over year increase.
-
Restrictive nature of the FEDs is shifting quickly. Doves are flying
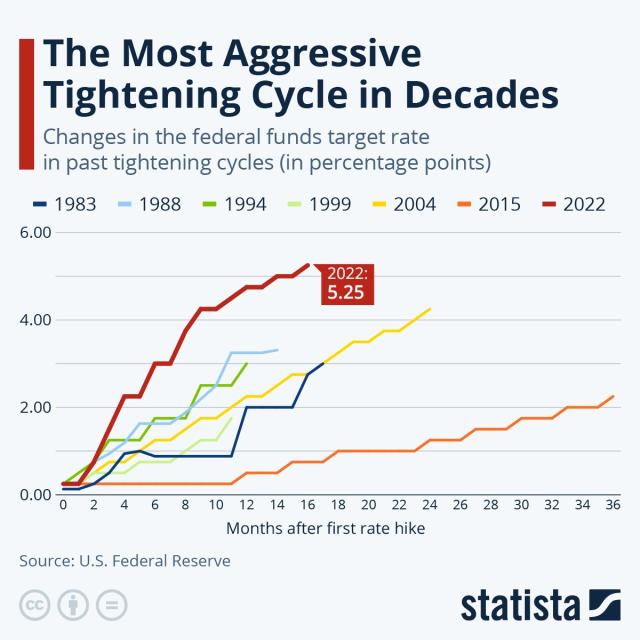
Goolsbee, Chicago Fed President said the Fed is at a historic level of restrictiveness. In English that means he is talking rate cuts sooner than later.
The jobs report is a big tell as the rising unemployment claims and higher consumer delinquencies are strong indicators of a slowing economy.
Friday, the Personal Consumption Expenditures (PCE) will give us an important look at inflation specifically the Core rate.
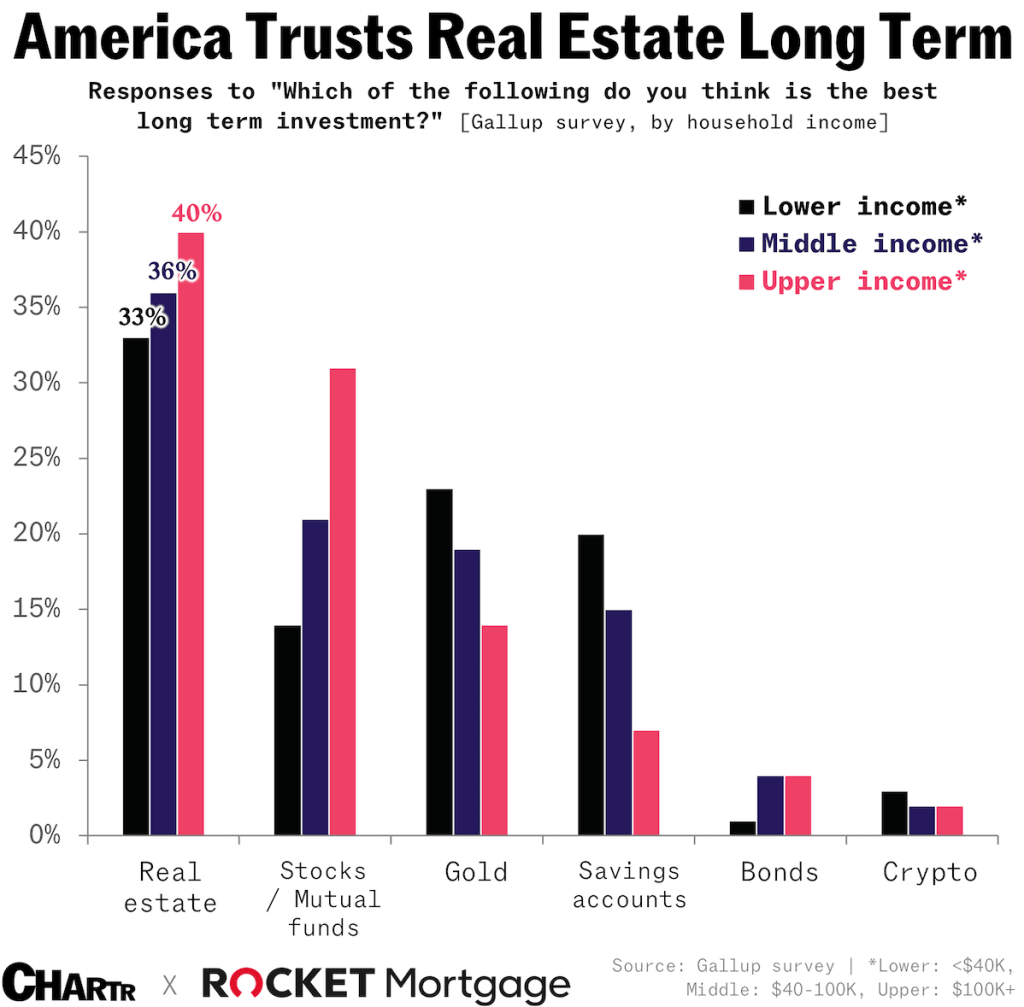
Real Estate is still the most trusted long term investment.
-
Retail Sales, a perspective on the numbers
Retail sales year to date are only up 0.3%. Consumer spending is slowing.
Consumer behavior has become more evident, with many opting for cheaper alternatives, like substituting steak with chicken.
To put this in perspective, the first five months of 2019 saw a 4% increase, while last year recorded a 2.7% rise.
In May, retail sales edged up by 0.1%, below the 0.2% estimate. Last month’s figure was revised down from -0.3% to -0.5%. Core retail sales, which contribute to GDP, increased by 0.4% but fell short of the 0.5% estimate.
For us, this means more data for the Fed to consider potentially earlier and more frequent rate cuts this year.
The job market shows significant revisions:
- October: revised from 165,000 to -9,000
- November: revised from 182,000 to 8,333
- December: revised from 290,000 to 116,333
The truth eventually surfaces.
Despite weaker retail sales, industrial production in May rose by 0.9%, surpassing the 0.3% estimate. This tempered the bond market’s reaction to the retail sales report.
There was some rate improvement, but not as much as anticipated.
-
Fed Speak, PPI and Jobs. Lets do the numbers.
Powell spoke yesterday and admitted that the Fed’s policy is currently restrictive. It’s like saying, “I know I’m being tough right now, but I’ll ease up later.”
Unemployment rate ticked up, Quite rate is lower, which means less job movers and the ones that have a job as staying put. Wage increases slower as well.
The Fed’s Summary of Economic Projections (SEP) indicates that members are considering one or two rate cuts this year. They are extremely data-driven in their decisions. While the economy remains strong, there is growing unease among the public.
The Producer Price Index (PPI) report fell 0.2%, lower than the 0.1% rise. PPI measures wholesale or producer inflation.
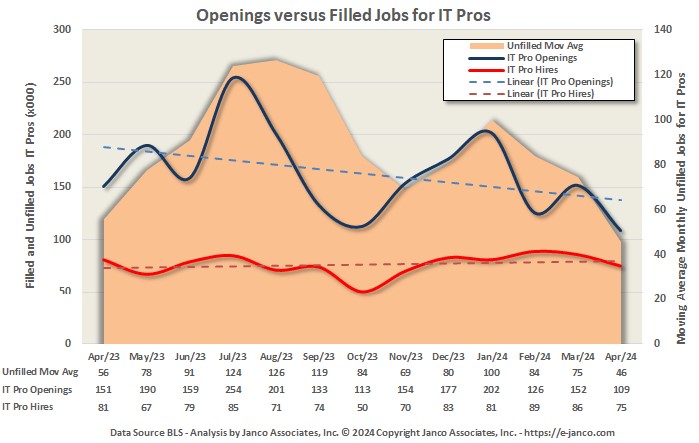
Initial jobless claims up for the first time in 10 months. The job market is tightening up.
The result of all this is lower interest rates. Lets see if the trend can continue through the summer.
-
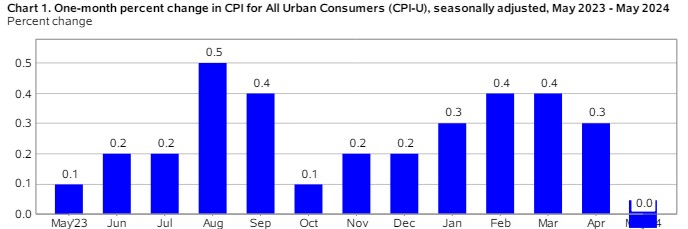
Zero, صفر, 零, nula, nul, μηδέν, शून्य, 零, cero – Inflation
May Consumer Price Index (CPI) reported zero inflation for the month. The estimate was 0.1%. This is significant and a powerful indicator for the Feds to start lowering their rate.
Looking at the Year over Year, almost all the inflation that was present was from Shelter and Motor Vehicle insurance.
Everything else only rose 0.21% from last year. Let that sink in. Shelter cost make up 45% of the core index.
Today the feds will be meeting to talk about rate future rate cuts. We do not expect any cuts this month or summer.
Rates have rebounded nicely this morning.
-
Why the Huge Jobs Report number? It’s wrong by the way.
The unexpectedly high job gains reported by the Bureau of Labor Statistics (BLS) in May can be attributed significantly to the Birth/Death model adjustments. This model plays a crucial role in estimating employment changes that arise from the natural churn of businesses starting up and shutting down. Here’s a detailed breakdown of the situation:
Birth/Death Model Overview
The Birth/Death model is designed to account for the dynamic nature of the business landscape. It estimates the number of jobs created by new businesses (births) and the number of jobs lost due to business closures (deaths). This model is particularly important because real-time data on new businesses and closures is not immediately available, and these factors significantly impact overall employment figures.
Impact on May’s Job Report
In May, the BLS reported a total of 272,000 jobs created, which significantly surpassed the estimated 185,000 jobs. Out of these 272,000 jobs, a substantial portion—231,000 jobs—were attributed to the Birth/Death model adjustments. This suggests that the majority of the reported job gains were derived from the model’s estimates rather than direct data from business surveys.
Why the Huge Job Gains?
- Economic Recovery and Expansion: The economy might be experiencing a phase of robust recovery or expansion, leading to the creation of numerous new businesses. As these businesses start operations, they contribute to job creation, which the Birth/Death model captures.
- Data Estimation Methods: The Birth/Death model relies on historical data and statistical techniques to make its estimates. If there are significant deviations from past trends or unexpected economic developments, the model’s estimates might be larger than anticipated.
- Seasonal Adjustments: The model incorporates seasonal adjustments to account for regular fluctuations in business activity. These adjustments can sometimes lead to higher estimates during certain times of the year.
The Dilemma
The challenge with relying heavily on the Birth/Death model is that it is an estimation tool. While it helps provide a more complete picture of employment changes, there is inherent uncertainty because it is based on statistical projections rather than direct measurements. This can lead to discrepancies and debates over the accuracy of the reported figures.
- Reliability Concerns: Critics argue that the model might overestimate job gains if it does not accurately reflect the current economic conditions or if there is an unexpected downturn in business activity.
- Adjustment Lag: The model’s estimates are based on past data, which means there can be a lag in reflecting real-time economic changes. Rapid economic shifts, such as those seen during economic recoveries or recessions, can make the model’s projections less reliable.
Conclusion
The significant job gains reported in May are largely driven by the Birth/Death model’s estimates of new business activity. While this model is essential for capturing the dynamic nature of the labor market, its reliance on historical data and statistical methods introduces a level of uncertainty. Therefore, while the reported figures suggest strong job growth, they should be interpreted with caution, understanding the underlying estimation processes and potential limitations of the Birth/Death model.
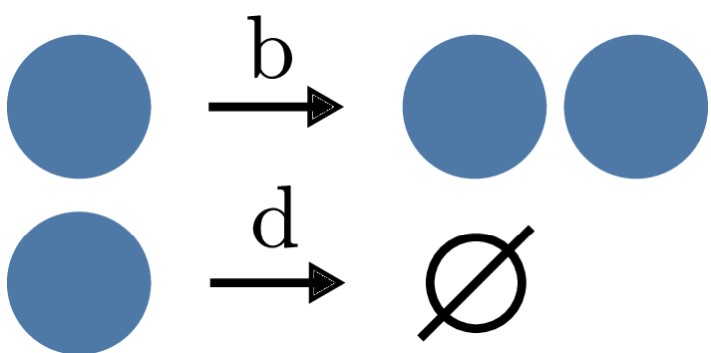
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

