-
More Oil, More Home Sales and More buyers hitting the streets.
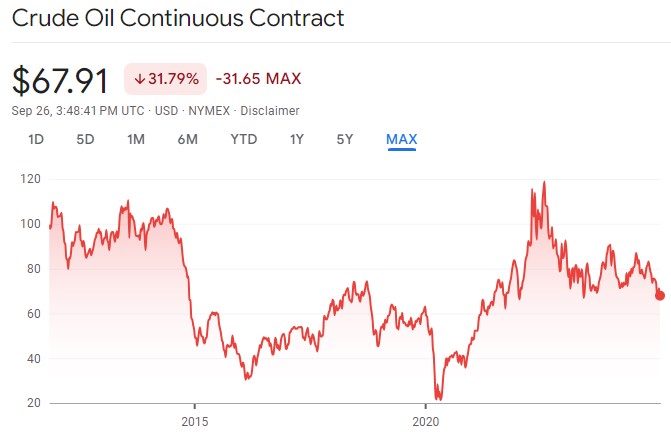
One of the larger components of the Personal Consumption Expenditures (CPE) is Shelter and Energy. Saudi Arabia who is the world’s largest oil exporter will be increasing Production by the end of the year. Right now oil is running just under $68 per barrel. They abandoned their $100 target.
As oil prices go down so does inflation. When inflation drops so does the Feds proclivity to drop their rates, as their rates drop….
Pending homes sales rose 0.6% in August stronger than expected.
Initial Jobless Claims fell for the first time in awhile 4,000 to 218,000.
Q2 GDP shows the US economy grew 3%, stronger than expected.
All in all generally good news but a mixed bag. We have seen a pull back with the bond market that has not helped rates this week..
Lets see what tomorrow brings when the PCE Inflation numbers hit.
-
Not Surprising, Refinance applications are up 175% Year over Year.
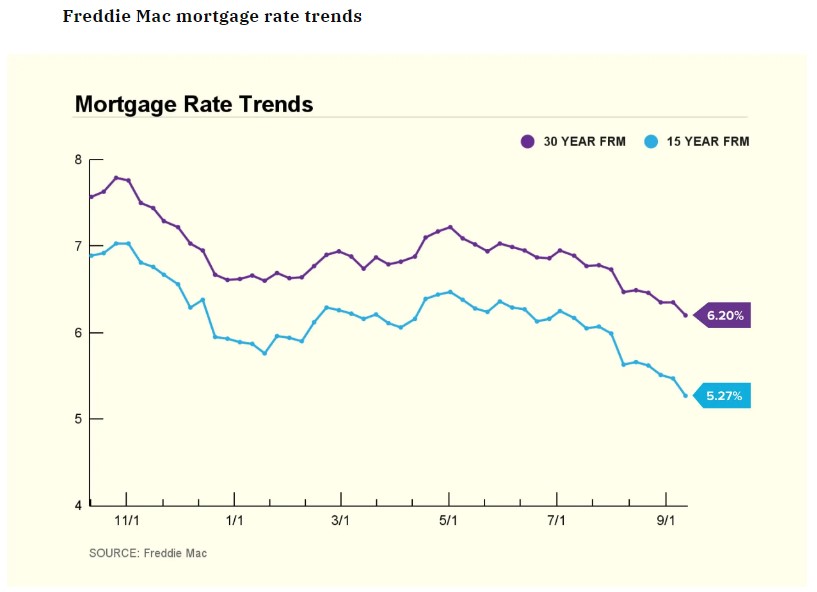
According to the Mortgage Bankers Association (MBA), interest rates are now 1.25% lower than this time last year, dropping from 6.15% to 6.13%.
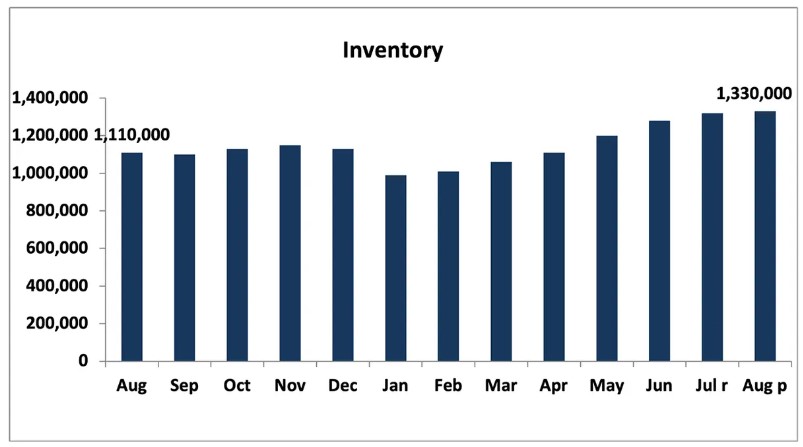
While new home sales fell 4.7%, they still surpassed estimates of 700,000, though only 105,000 homes were completed. What’s more interesting is the pace of sales compared to the number of available or completed homes.
Last month, 716,000 contracts were signed, equating to 7.8 months of inventory, but only 1.7 months of that inventory represents completed homes.
Despite these dynamics, housing demand remains strong, especially as interest rates continue to decline.
-
Who’s the Cheese wrapped around that dog pill?
Bonds are sensitive to global events, and a major one occurred today. The People’s Republic of China announced several stimulus measures to boost their economy.
Key actions include cutting the average interest rate on existing mortgages by 0.5%, lowering minimum down payment requirements, and other steps to release a significant amount of funds.
While this may seem positive on the surface, it raises global inflation concerns and China’s stability. More global funds drives demand, limits supply and increases prices.
When I’m asked how far and when I expect rates to drop, the answer is more complex than it initially appears. The Bond Market around the world moved lower in price. Translation slight rate improvement.
Case Shiller Home Price Index rose 0.2% in July with Home prices up 5% year over year.
-
Fed Gov Waller “Inflation on lower Path than we Expected…”
I never thought I’d hear these words. Here’s the exact quote:
“Inflation is on a lower path than we were potentially expecting. I think inflation is on the right path, as log as we don’t let it get too low”.
Even Fed Pres Minneapolis Neel Kashkari said even after the 50bp cut the Fed is still restrictive. He wants another 50bp by end of the year.
What’s coming up this week.
- Tuesday – Cash Shiller Home Price and FHFA house Index
- Wednesday – Mortgage Applications and New Home Sales
- Thursday – GDP, Initial Jobs Claims
- Friday – Personal Consumption Expenditures – PCE.
PCE is the big news of the week. If expectations come in at 0.1% in August that will put inflation at 2.3% down from 2.5%.
In my view, interest rates are falling. How much they’ll drop remains uncertain, but we’re finally seeing some light at the end of the tunnel. For years, low inventory has been a challenge, with homeowners locked into 3% rates and buyers either unable to afford homes or waiting for rates to decrease.
If you’re a homeowner looking to move, now’s the time to tune up your finances and get pre-approved—just in case you find your new dream home. For home buyers, inventory is up 22% from last year, and more homes are hitting the market, with more expected in the future.
-
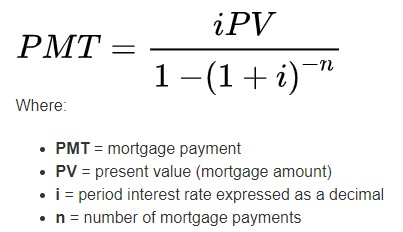
A Surprisingly Simple formula to calculate house payment in your head.
Here’s an example: if you have a $500,000 loan at a 6% interest rate, with typical property taxes and homeowner insurance, your total monthly payment would be around $3,210. That breaks down to $642 per $100,000 borrowed.
To simplify further, you can estimate that every $100,000 borrowed will cost you about $700 per month, which gives you a slight cushion to overestimate the final payment.
If you live in a State or County with lower property taxes, you might be closer to $625 per $100,000 borrowed. In higher-tax states like New Jersey or Texas, the figure could be closer to $700 per $100,000 borrowed.
It’s an easy way to get a rough idea of your total monthly house payment.
“I found a beautiful home, Sales price is $700k and I want to put $100k down. $600k loan is 6x$700 or $4,200 a month total house payment.“
Here is the actual Math if you want to pull out your calculator or just use my simple trick.
-
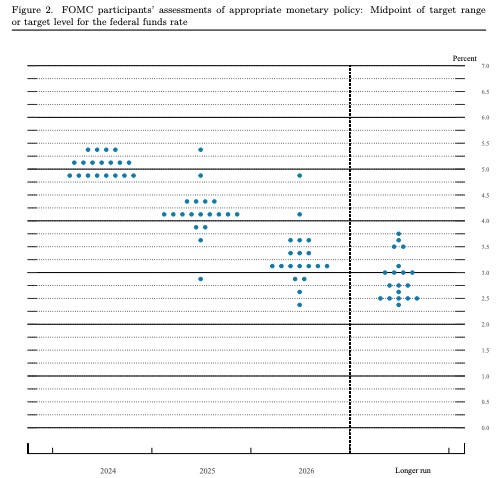
Fed Dot Plot Gives us Insight- It’s more exciting that it looks…
The dot plot below represents each Fed official’s projections for future Federal Reserve interest rates.
This plot is updated every three months, with the next update in December.
Now that we’ve covered that, let’s dive into how this affects you. Credit card and auto loan rates will gradually decrease, and HELOCs or home equity loans tied to these rates will start to decline as well.
What about mortgage rates? While the correlation between the Fed rate and mortgage rates isn’t exact, they generally move in the same direction. So, as the Fed rate drops, mortgage rates are likely to follow.
Mortgage Interest Rates are dropping and will continue into 2025.
-
Rate Cut Cycle Begins: A New Era, Whether 25 or 50 Basis Points.
The greatest challenge arises when the remedy becomes worse than the problem. Prolonged restrictive Fed rate policies lead to higher costs for everyone, ultimately prolonging inflation.
The industry is pricing in a 63% likelihood of the Fed cutting rates by 50 basis points, as reflected in the recent decline in rates over the past two weeks.
Anecdotally, feedback from the real estate community suggests that clients are waiting for a Fed rate cut, regardless of its actual impact on mortgage rates. It’s the perception of rates dropping that is motivating those on the fence to take action.
At 2pm PST the Federal Reserve will release a statement on the rate cut and a summary of economic projections.
Reach out to our team to navigate your refinance/purchase. www.YourApplicationOnline.com
-
The Battle of the Indicators. Who will win, no one knows? William Dudley knows…
William Dudley is a former NY Fed President and is calling for a 50bp Cut in the Fed Rate tomorrow.
The Federal Reserve focuses primarily on two key factors: inflation and the overall economy. Inflation, heavily influenced by shelter costs and auto insurance, can sometimes paint a misleading picture of the true inflation landscape.
The job market continues to show signs of weakening, with the unemployment rate increasing by 0.8% so far this year.
Dudley highlighted that 92% of the 4 million jobs created were part-time or self-employed positions, yet they are still counted as full-time jobs. This skews the data, masking the decline in job quality.
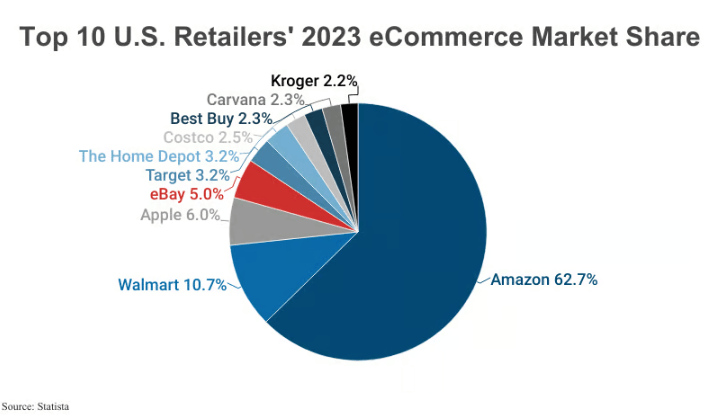
What to know the Power of Amazon? Last months retail sales rose 0.1% primarily due to Prime Day from Amazon. $14.2 Billion in sales on one day.
Rates continue to improve as we hold our collective breath for tomorrows Fed Announcement. I have my money on a 50bp drop then another 25×2 by the end of the year.
-
It’s tough to make Decisions especially about the Future. – Yogi Berra
What will the Federal Reserve do Wednesday. We have some insight.
Former Fed Vice Chair Donald Kohn: “We are at a point where you might say, I could go either way – 25 or 50. but I think the risk management has shifted to the labor market and favors doing 50”.
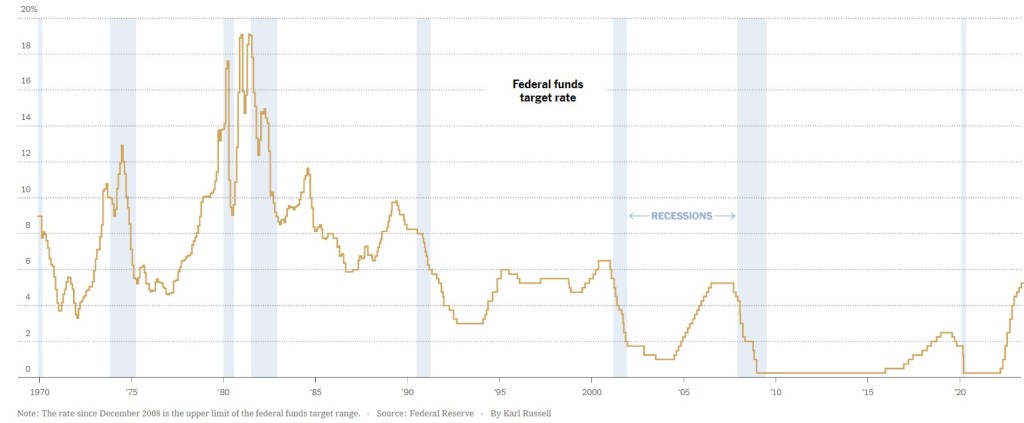
When we look back, we can see that once rate cuts start, they tend to proceed rapidly.
Later today we will hear from Former Fed Vice Chair, Lael Brainard, now the Director of National Economic Council.
Her prepared remarks were released and highlights that “we have reached a milestone in the fight against inflation”.
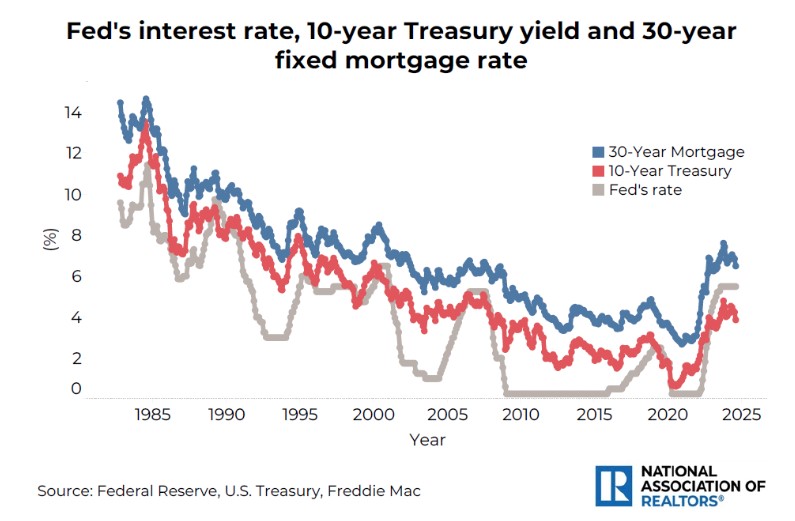
How will this affect the mortgage rates? a picture is worth a thousand words. Mortgage rates have historically followed the Fed Rate.
Feel free to forward, copy and reach out anytime. www.YourApplicationOnline.com
-
To Be or Not to Be.
What will the Federal Reserve actually do on the 18th? The market is expecting, and has priced in, a 0.25% rate cut. Personally, I believe the cut should be more aggressive—at least 0.50%.
The Fed has effectively shifted the goalposts regarding the timing and size of future cuts. The current unemployment rate is 4.2%, slightly down from 4.3% last month.
Interestingly, 16 out of 19 Fed members predicted unemployment wouldn’t exceed 4.1% this year—yet here we are.
The market is anticipating a 1% rate cut this year and an additional 1.25% next year. Let’s hope the Fed moves forward and breaks free from their analysis paralysis.
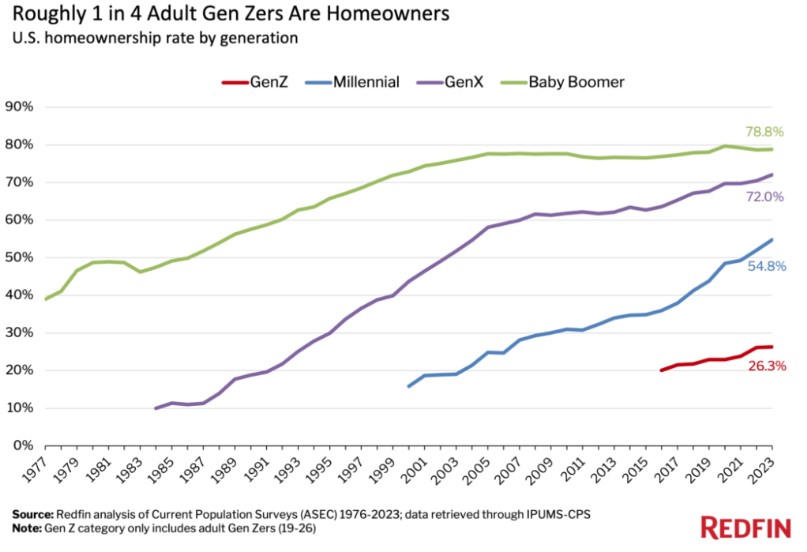
Let’s take a look at the housing market through the lens of different generations.
At age 30, the homeownership rate was 48% for Boomers, 42% for Gen X, and 33% for Millennials. People are waiting longer to get married, have kids, and buy homes. However, by age 40, those rates rise significantly, and Millennials begin to catch up with Gen X and Boomers in homeownership.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

