-
Jobs report remains strong
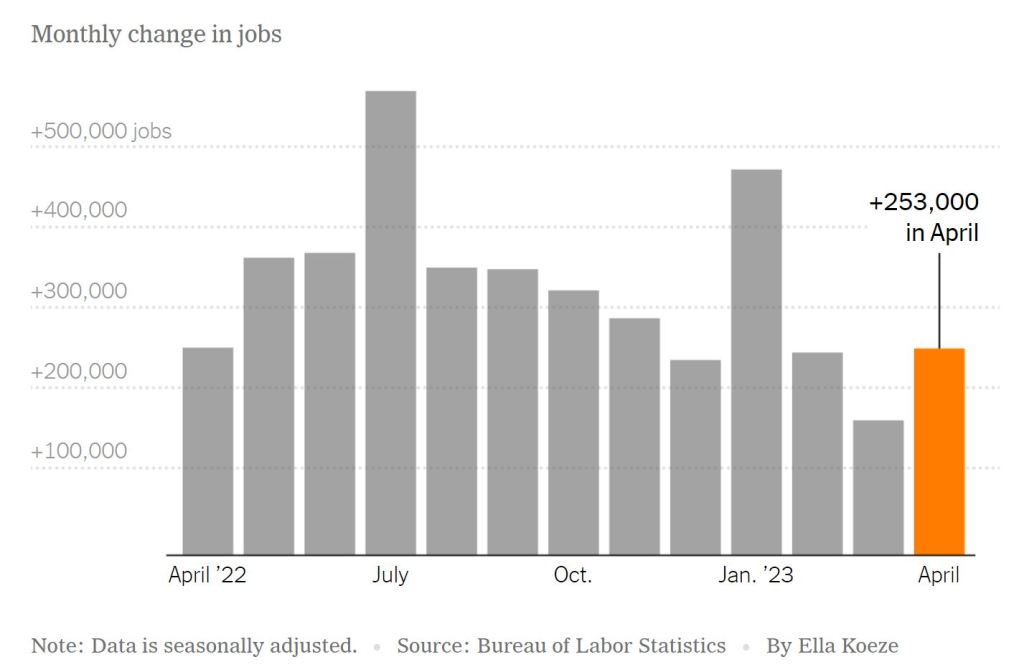
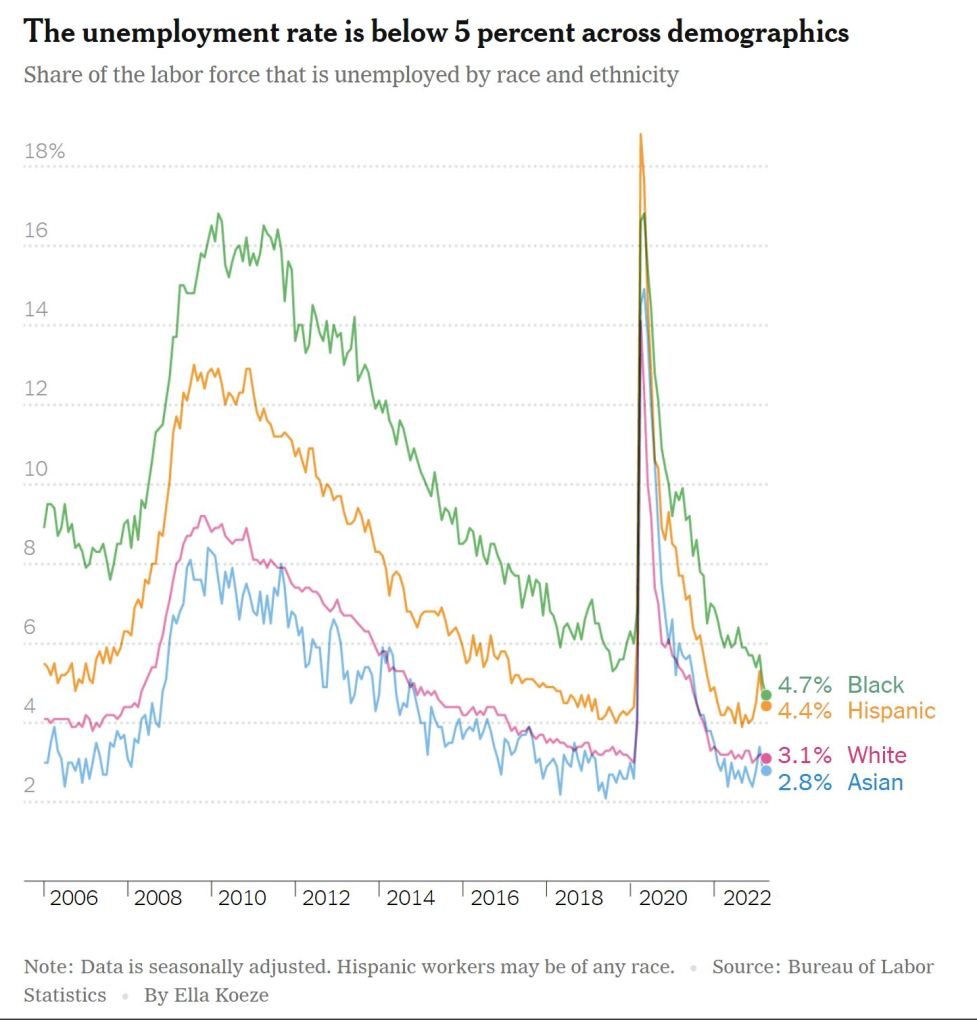
More Jobs were added in April than in previous months despite the Federal Reserve’s efforts. Unemployment rate drops to 3.4%
Another data point for the unemployment rate.
The economy is stubborn, this is a good thing, but the Feds are not happy this morning…..
-
Fed Rate and Mortgage Rate aren’t Married to each other, they are not even dating….
I love graphs, they tell you so much with so few words. But first lets quickly understand the difference between the Fed Funds rate and the Mortgage Rate.
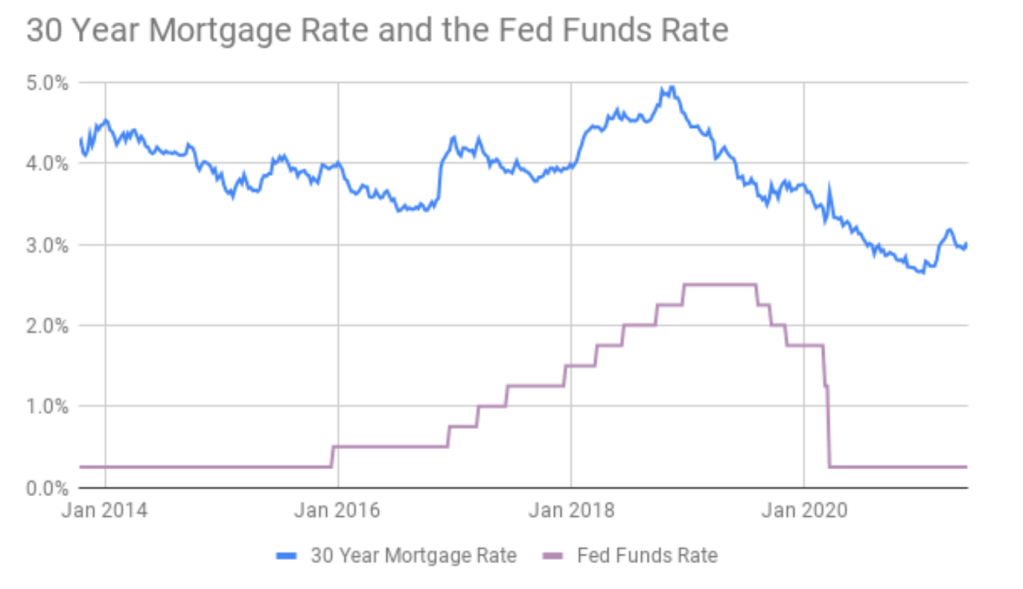
Fed Funds Rate is the rate banks borrow overnight to satisfy liquidity requirements set by regulators. Banks then pass that rate to its clients affecting short term lending:
- Car loans
- Credit cards
- HELOCs Home equity line of credit
- ARMs Adjustable Rate Mortgages
Mortgage Interest Rates reference the yield on the 10-year Treasury bonds.
When the Fed raises rates, Mortgage rates typically go down.
This is the 10 Year Treasury bond vs the Fed Rate.
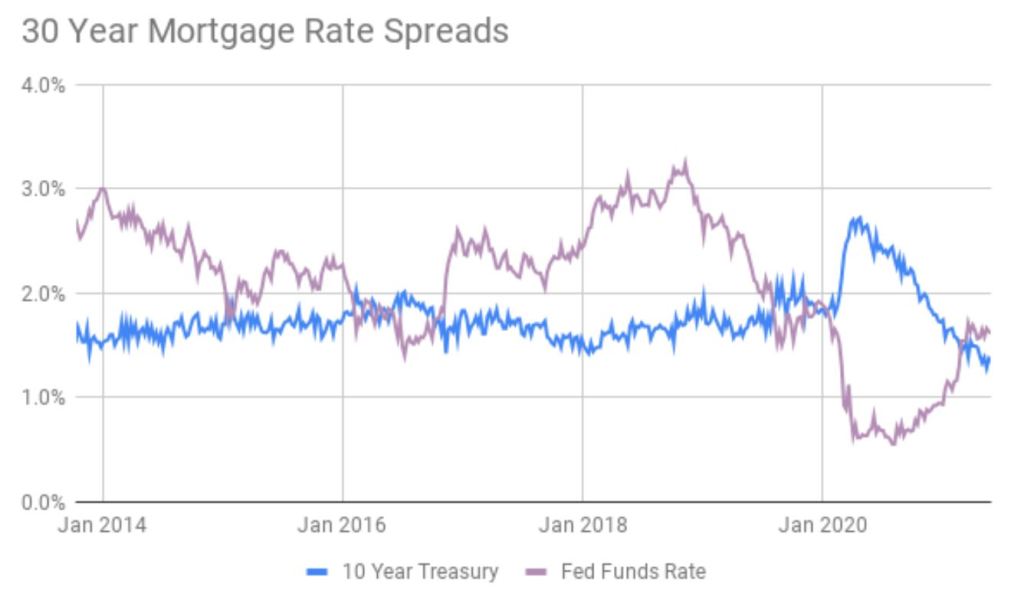
Let’s now look at the 30 Year Mortgage vs the 10 Year Treasury Rate
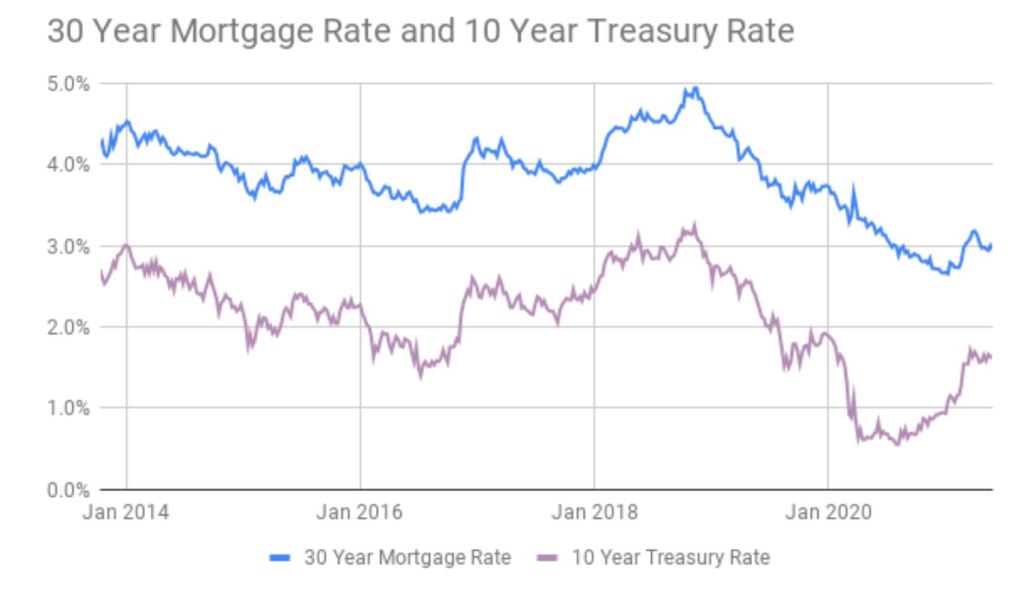
In conclusion…. When you hear the Feds are raising rates, run to your lender to get pre-qualified for a Mortgage or ask about refinancing your loan.
Have a great rest of your week and always feel free to reach out.
-
Inflation is coming down, Why the 25bp hike.
We just don’t know. Producer Price Index – PCE is down sharply from 11.7 to 2.7%. Inflation is down and the low and mid level regional bank issue that could create more strain and potential banking crisis. They make up 40% of all loans.

Rates have improved this week. I will hang onto that.
-
Is that a piece of Ice or an Iceberg in front of us?
With Sunday’s news of the downfall of First Republic Seized by regulators into FDIC receivership, my first thought was how is this going to affect the bond market.
Typically this type of disruption would mean bond prices drop as well as interest rates. This did not happen. We saw minimal change at best. The market is calling this a piece of Ice not an Iceberg.
The Feds are expected to raise the Fed rate by 0.25 basis points Wednesday.
Rate average this year.
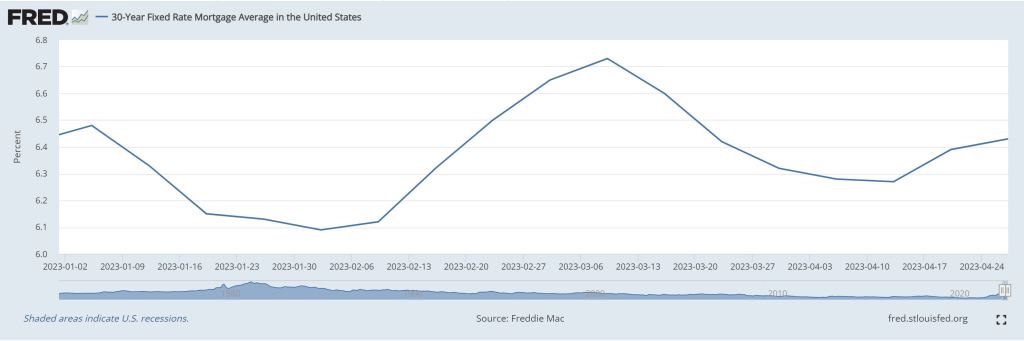
Headed into a meeting this morning, have a fantastic week.
-
Double Coincidence of Wants.
I want what you have and you want what I have. Money solves the challenge of barter.
First Republic was flying high borrowing money at very low interest rates and then turning around and lending to homeowners below market average rates. Tough to compete with a lender offering a half to a full point lower than the national average.
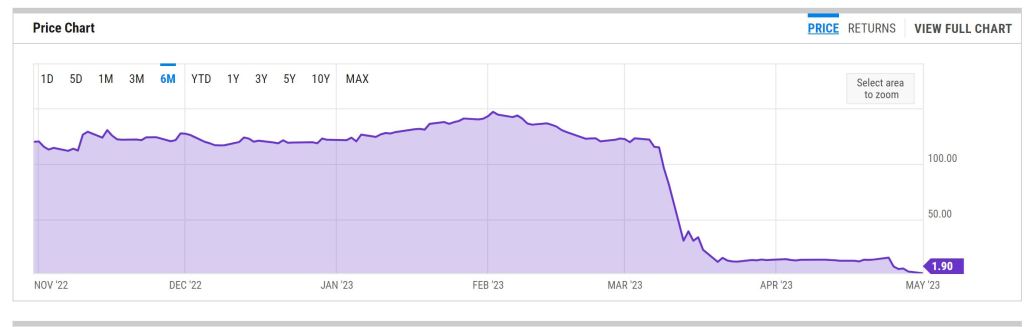
As the interest rates rose those mortgages at the low interest rates started to lose their value. This on top of Silicon Valley Bank collapse spooked depositors and we had another run on a bank. Fortunately JP Morgan stepped in last night after the Feds announced the seizure of the bank.
The FDIC believes this and the other smaller regional bank failures are Unique within the banking industry.
Have a fantastic Week.
-
What goes Up must come Down
Personal Consumption Expenditures (PCE) showed inflation rose .01% in March, less than the expected 0.3%. Year over Year we have a decline from 5.1% to 4.2%. Better than the Markets had expected.
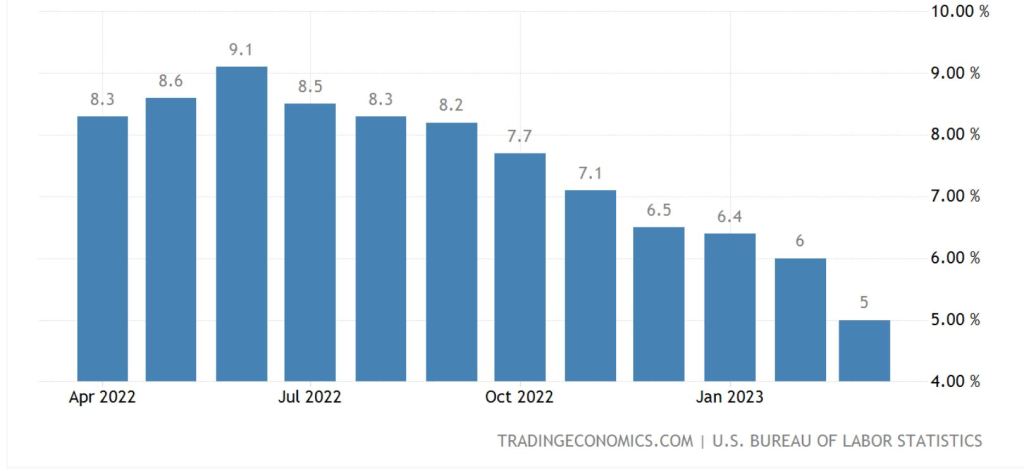
We have already seen some rate improvement. Lets see if the Feds are still driving looking at the rear view mirror.
It’s Friday, what a week. enjoy the weekend and always feel free to reach out.
-
We just need to break free
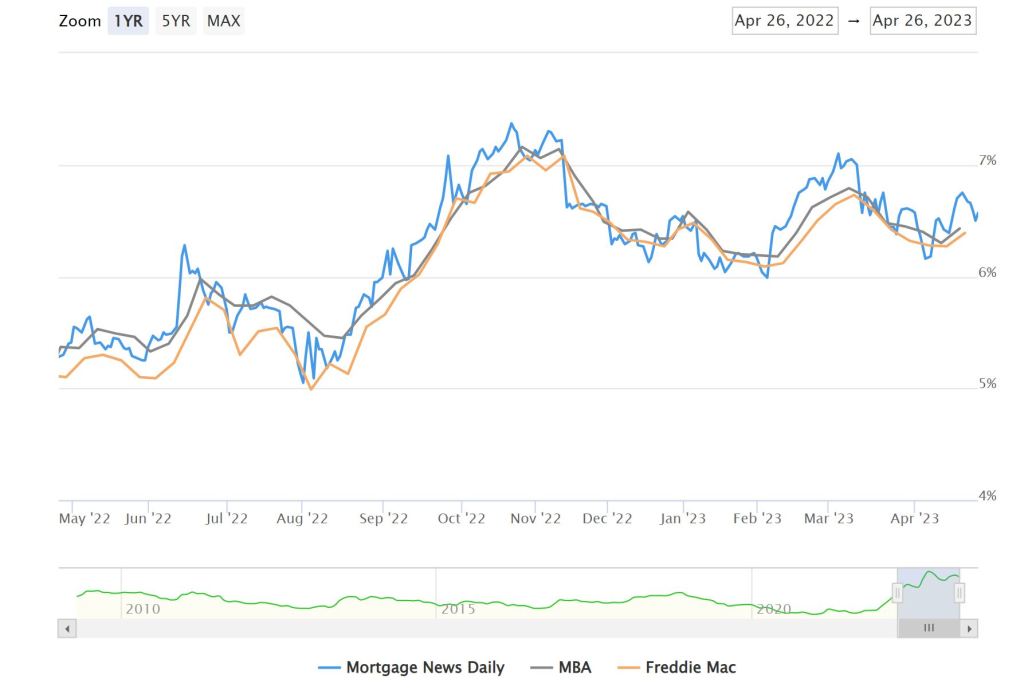
The graph displays the 30-year interest rates for a fixed term, spanning over 1 year. Despite reaching a peak in November and experiencing another smaller peak in March, we have been unable to surpass (drop below) the range of 6-7%.
As previously discussed in a recent post about payment disparities and interest rates, there is only a 30% increase in payment when going from a 3.5% to 6.5% loan, not double. Similarly, a shift from 3.5% to 5.125% results in approximately a 15% difference in payment.
These findings are crucial to inspire sellers to place their properties on the market.
I am off to three meetings this morning and just finished my second cup of coffee. Have a fantastic day, Friday is tomorrow.
-
What is Fannie Mae and Freddie Mac Up to. Low Credit better Rates???
Are you feeling confused about Fannie and Freddie’s actions with rates and credit scores?
This Video will provide clarity on the matter, revealing what’s really happening. Take just five minutes out of your day to gain a true understanding of loan pricing and credit risk mechanics.
We’ve reached the midweek mark and the sun is shining bright. Wishing you a fantastic rest of the week!
-
10% rise in Signed Contracts
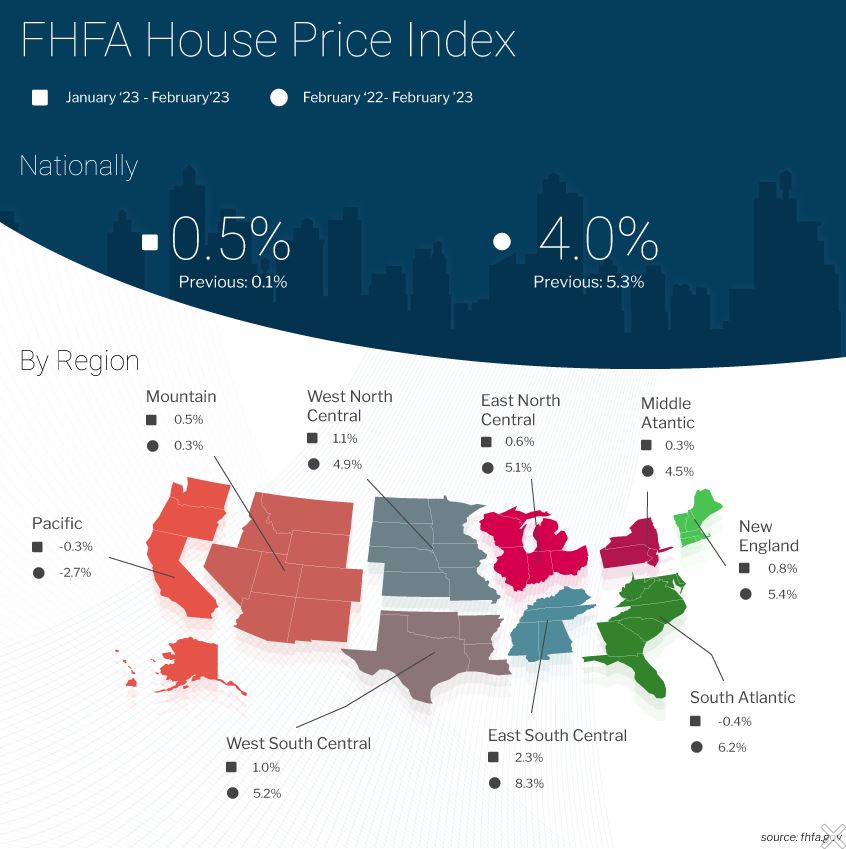
Spring has Sprung and buyers are out in force. We have the strongest new homes sales data in 13 months. The median home price also rose 3.8% last month to $449,800. This is the forth strong report in a row.
Below is the YouTube Video with a deep dive regarding Fannie Mae and Freddie Mac Low Credit score Risk pricing change and its real impact.
Have a great rest of your week.
-
Is There Really a New Unfair Mortgage Tax on those with High Credit?
In the last week my inbox and on the internet has been flooded with this “new” unfair tax on mortgage borrowers with higher credit scores.
Before you Stop paying your bills to cash in on better pricing, let’s separate fact from fiction.
- You will absolutely NOT get a better deal on a mortgage rate if your credit score is lower.
- Low credit borrowers are not paying less than a high credit borrower.
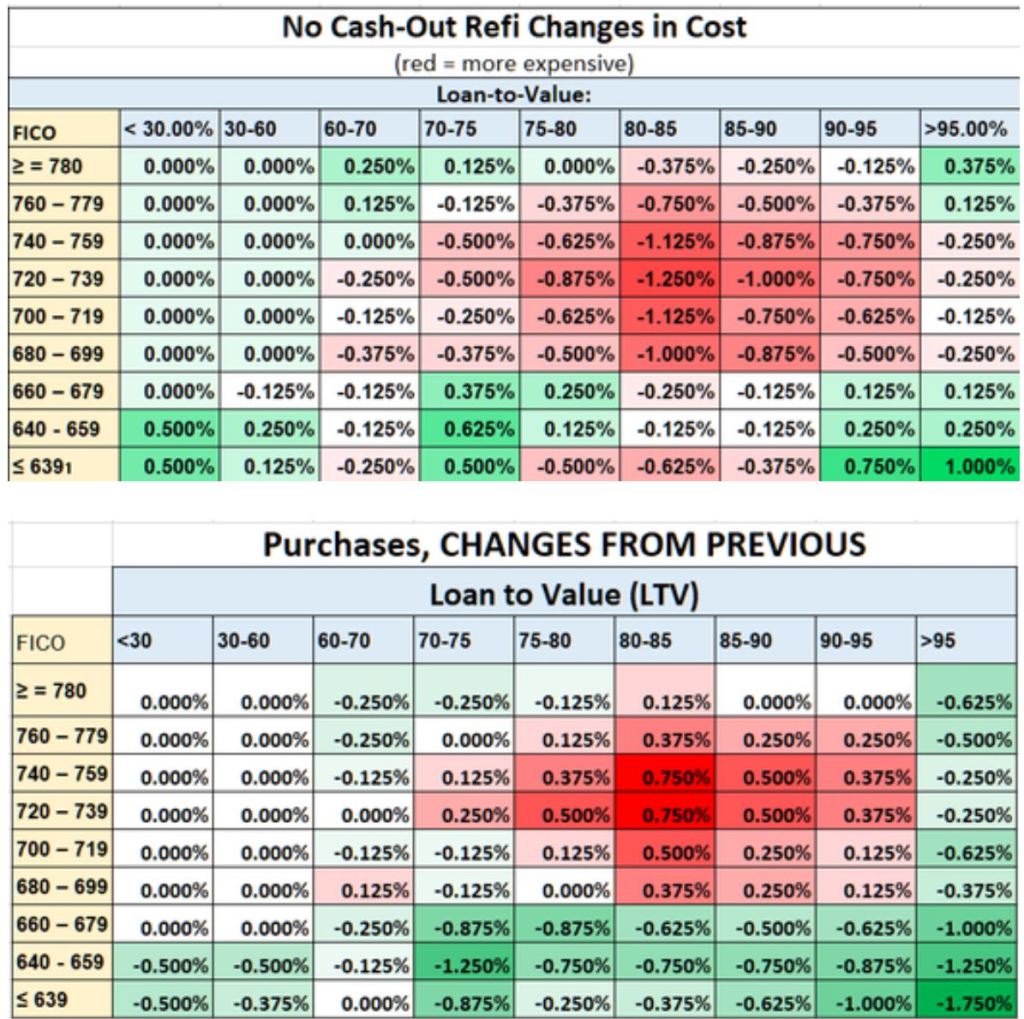
Let’s look at some charts. Red = rising costs. Green= Falling costs.
If you saw the first two charts or it’s your first time seeing them, you can be forgiven to think a low credit borrower is paying less than a high credit borrower.
*LLP is Loan Level Pricing , % cost of the loan amount. That is the % reference in the charts below.
Let’s now look at the ACTUAL cost not the CHANGE.
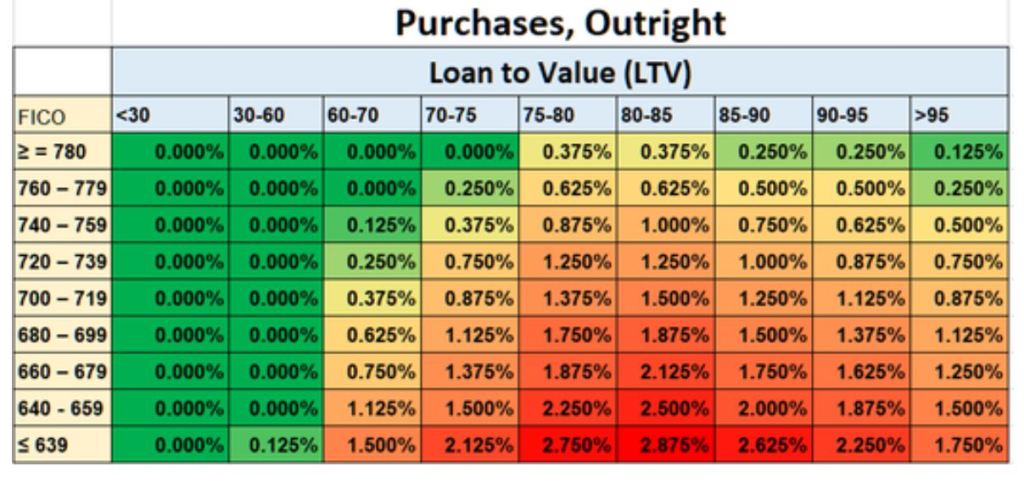
If you have a 640 credit score, You’ll be paying significantly more than if you had a 740 score.
Freddie and Fannie have a “mission” to promote affordable home ownership. Their comments in the link below.
https://www.fhfa.gov/Mhttps://www.fhfa.gov/Media/PublicAffairs/Pages/FHFA-Announces-Updates-to-Enterprises-SF-Pricing-
Its earnings week so be ready for a bit of a volatile week.
-
Subscribe
Subscribed
Have a WordPress.com account? Log in now.

